Modeling volatility using state space models
Related Experiment Videos
1Fakultät für Physik, Universität Freiburg, Germany. jeti@fdm.uni-freiburg.de

Abstract:
In time series problems, noise can be divided into two categories: dynamic noise which drives the process, and observational noise which is added in the measurement process, but does not influence future values of the system. In this framework, we show that empirical volatilities (the squared relative returns of prices) exhibit a significant amount of observational noise. To model and predict their time evolution adequately, we estimate state space models that explicitly include observational noise. We obtain relaxation times for shocks in the logarithm of volatility ranging from three weeks (for foreign exchange) to three to five months (for stock indices). In most cases, a two-dimensional hidden state is required to yield residuals that are consistent with white noise. We compare these results with ordinary autoregressive models (without a hidden state) and find that autoregressive models underestimate the relaxation times by about two orders of magnitude since they do not distinguish between observational and dynamic noise. This new interpretation of the dynamics of volatility in terms of relaxators in a state space model carries over to stochastic volatility models and to GARCH models, and is useful for several problems in finance, including risk management and the pricing of derivative securities. Data sets used: Olsen & Associates high frequency DEM/USD foreign exchange rates (8 years). Nikkei 225 index (40 years). Dow Jones Industrial Average (25 years).
Related Concept Videos
 01:27
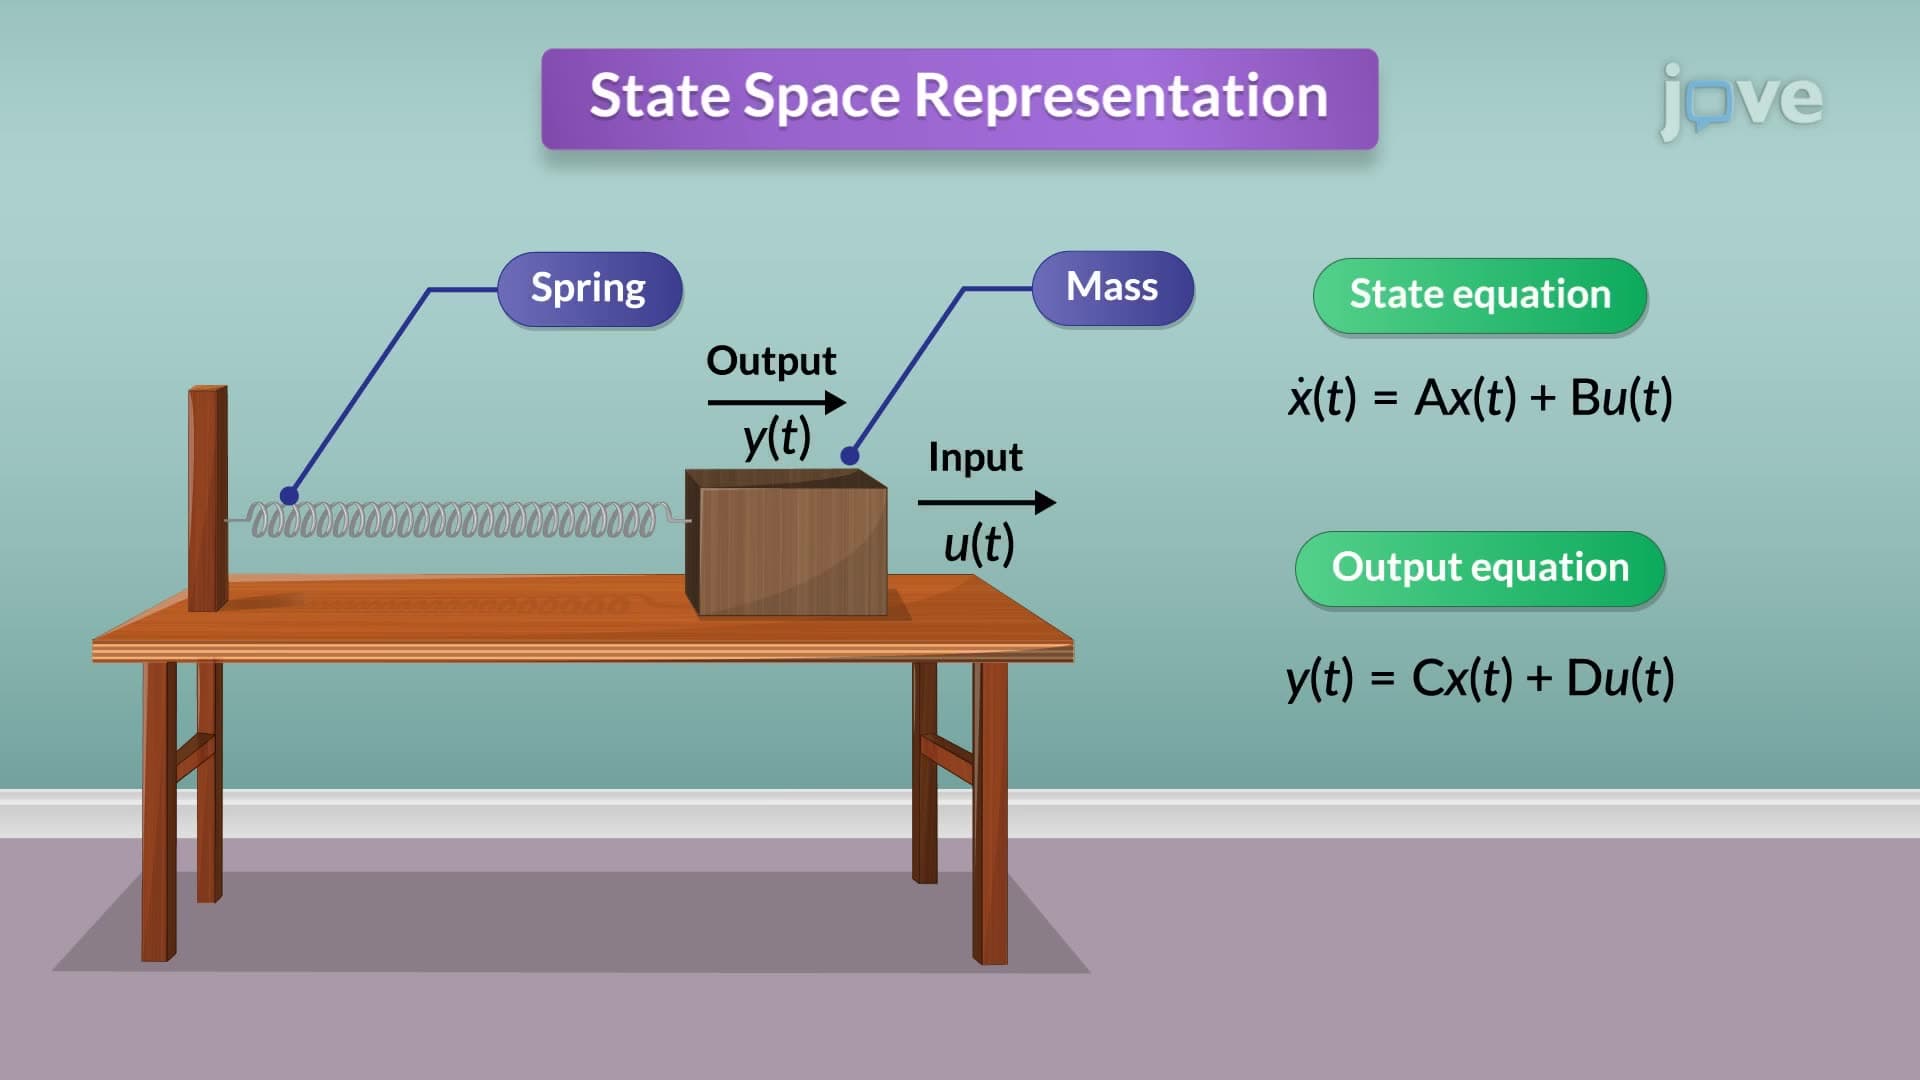
State Space Representation
Consider an RLC circuit, a...
 01:21
State Space to Transfer Function
The transformation process begins with the state-space representation, characterized by the state equation and the output equation. These equations are typically represented as:
 01:23
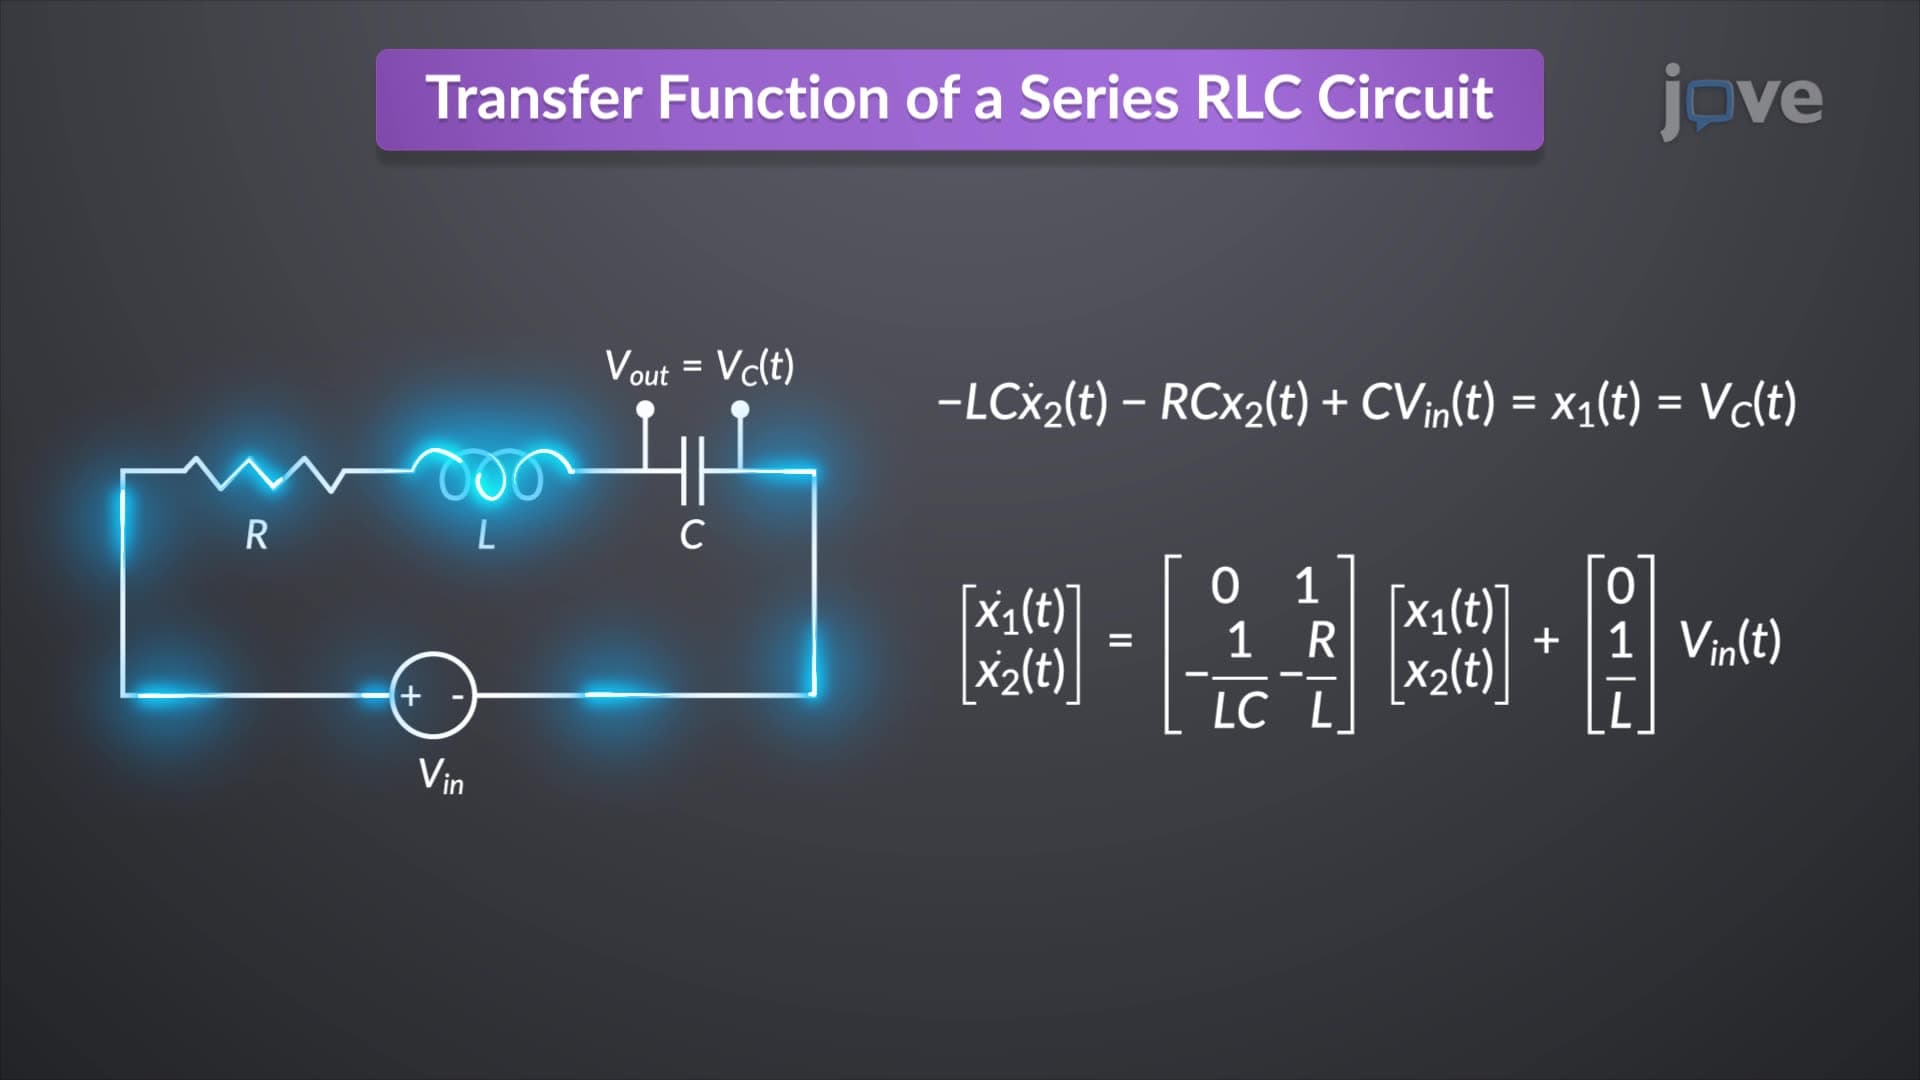
Transfer Function to State Space
In an RLC...
 01:21
Linear Approximation in Time Domain
For a simple pendulum with a mass evenly distributed along its length and the center of mass located at half the pendulum's length, the...
 01:25
Modeling with Differential Equations
 01:21
Mechanistic Models: Overview of Compartment Models