Value at risk estimation using independent component analysis-generalized autoregressive conditional heteroscedasticity (ICA-GARCH) models
Related Experiment Videos
Edmond H C Wu1, Philip L H Yu, W K Li
1Department of Statistics & Actuarial Science, University of Hong Kong. hcwu@hkusua.hku.hk

Abstract:
We suggest using independent component analysis (ICA) to decompose multivariate time series into statistically independent time series. Then, we propose to use ICA-GARCH models which are computationally efficient to estimate the multivariate volatilities. The experimental results show that the ICA-GARCH models are more effective than existing methods, including DCC, PCA-GARCH, and EWMA. We also apply the proposed models to compute value at risk (VaR) for risk management applications. The backtesting and the out-of-sample tests validate the performance of ICA-GARCH models for value at risk estimation.
Related Concept Videos
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 00:56
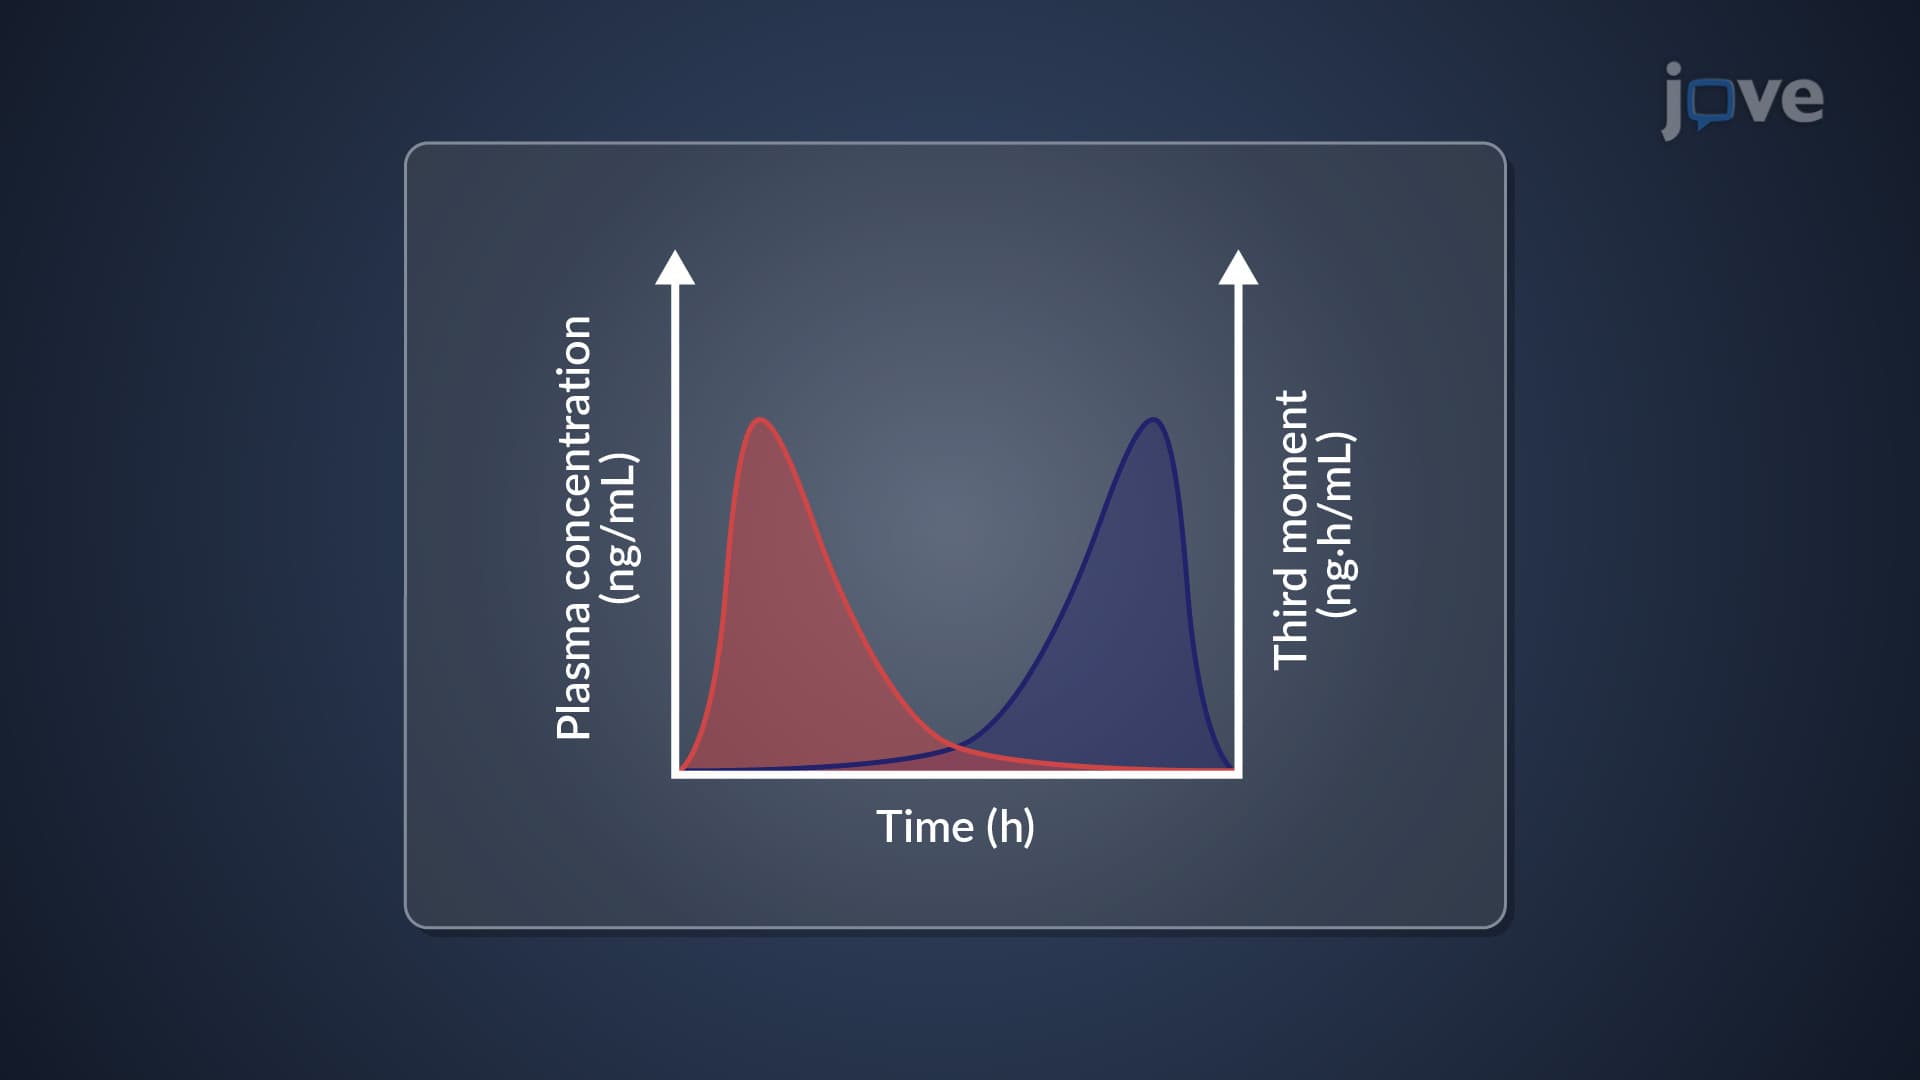
Noncompartmental Analysis: Statistical Moment Theory
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
The...
 01:29
Econometric Views (EViews)
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:17
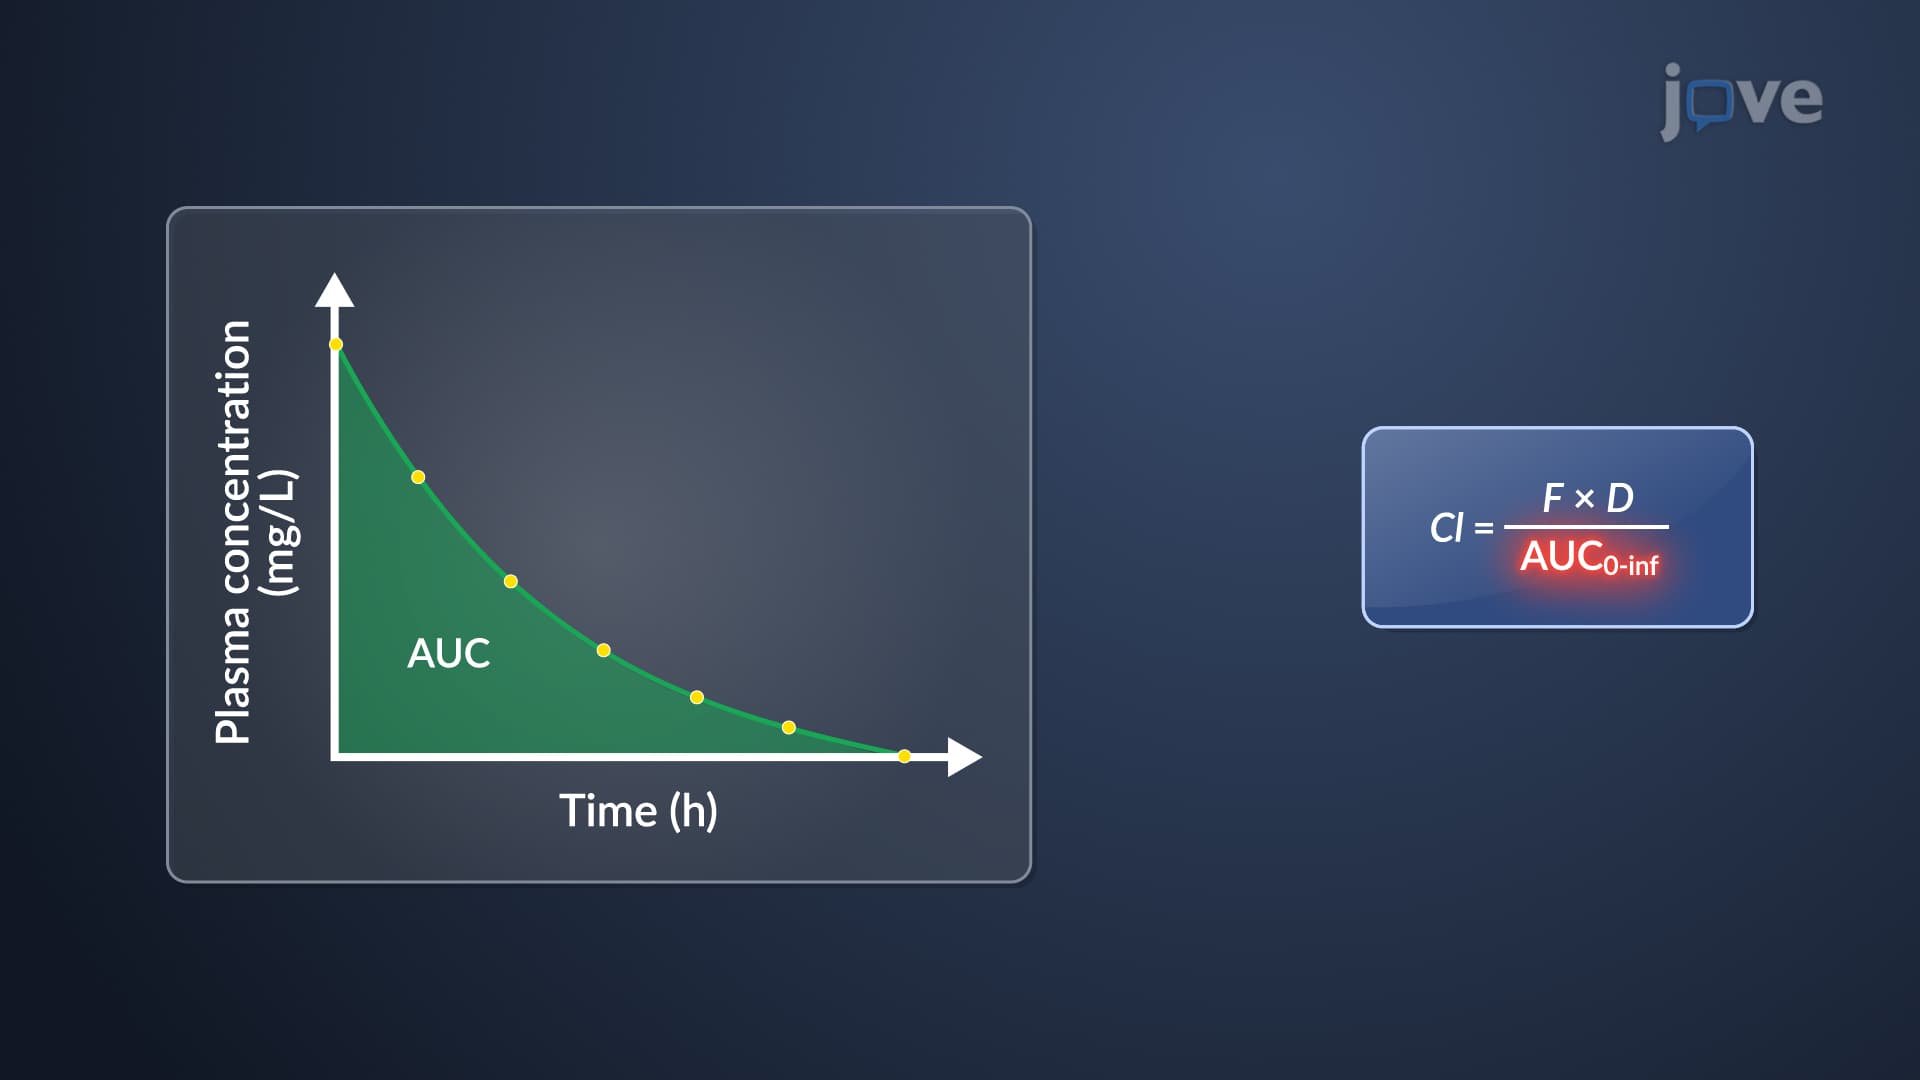
Clearance Models: Noncompartmental Models
The noncompartmental approach capitalizes on extensive sampling data, correlating the volume of distribution to systemic exposure and the administered dosage. This method enables...