Related Experiment Video
Updated: Jul 17, 2026
Age-dependent Dynamics of Locomotion in Caenorhabditis elegans: A Lyapunov Exponent Analysis
Published on: September 23, 2025
Extracting the scaling exponents of a self-affine, non-Gaussian process from a finite-length time series
K Kiyani1, S C Chapman, B Hnat
1Centre for Fusion, Space and Astrophysics, Department of Physics, University of Warwick, Coventry CV4 7AL, United Kingdom. k.kiyani@warwick.ac.uk

Abstract:
We address the generic problem of extracting the scaling exponents of a stationary, self-affine process realized by a time series of finite length, where information about the process is not known a priori. Estimating the scaling exponents relies upon estimating the moments, or more typically structure functions, of the probability density of the differenced time series. If the probability density is heavy tailed, outliers strongly influence the scaling behavior of the moments. From an operational point of view, we wish to recover the scaling exponents of the underlying process by excluding a minimal population of these outliers. We test these ideas on a synthetically generated symmetric alpha -stable Lévy process and show that the Lévy exponent is recovered in up to the 6th order moment after only approximately 0.1-0.5% of the data are excluded. The scaling properties of the excluded outliers can then be tested to provide additional information about the system.
Related Concept Videos
 01:24
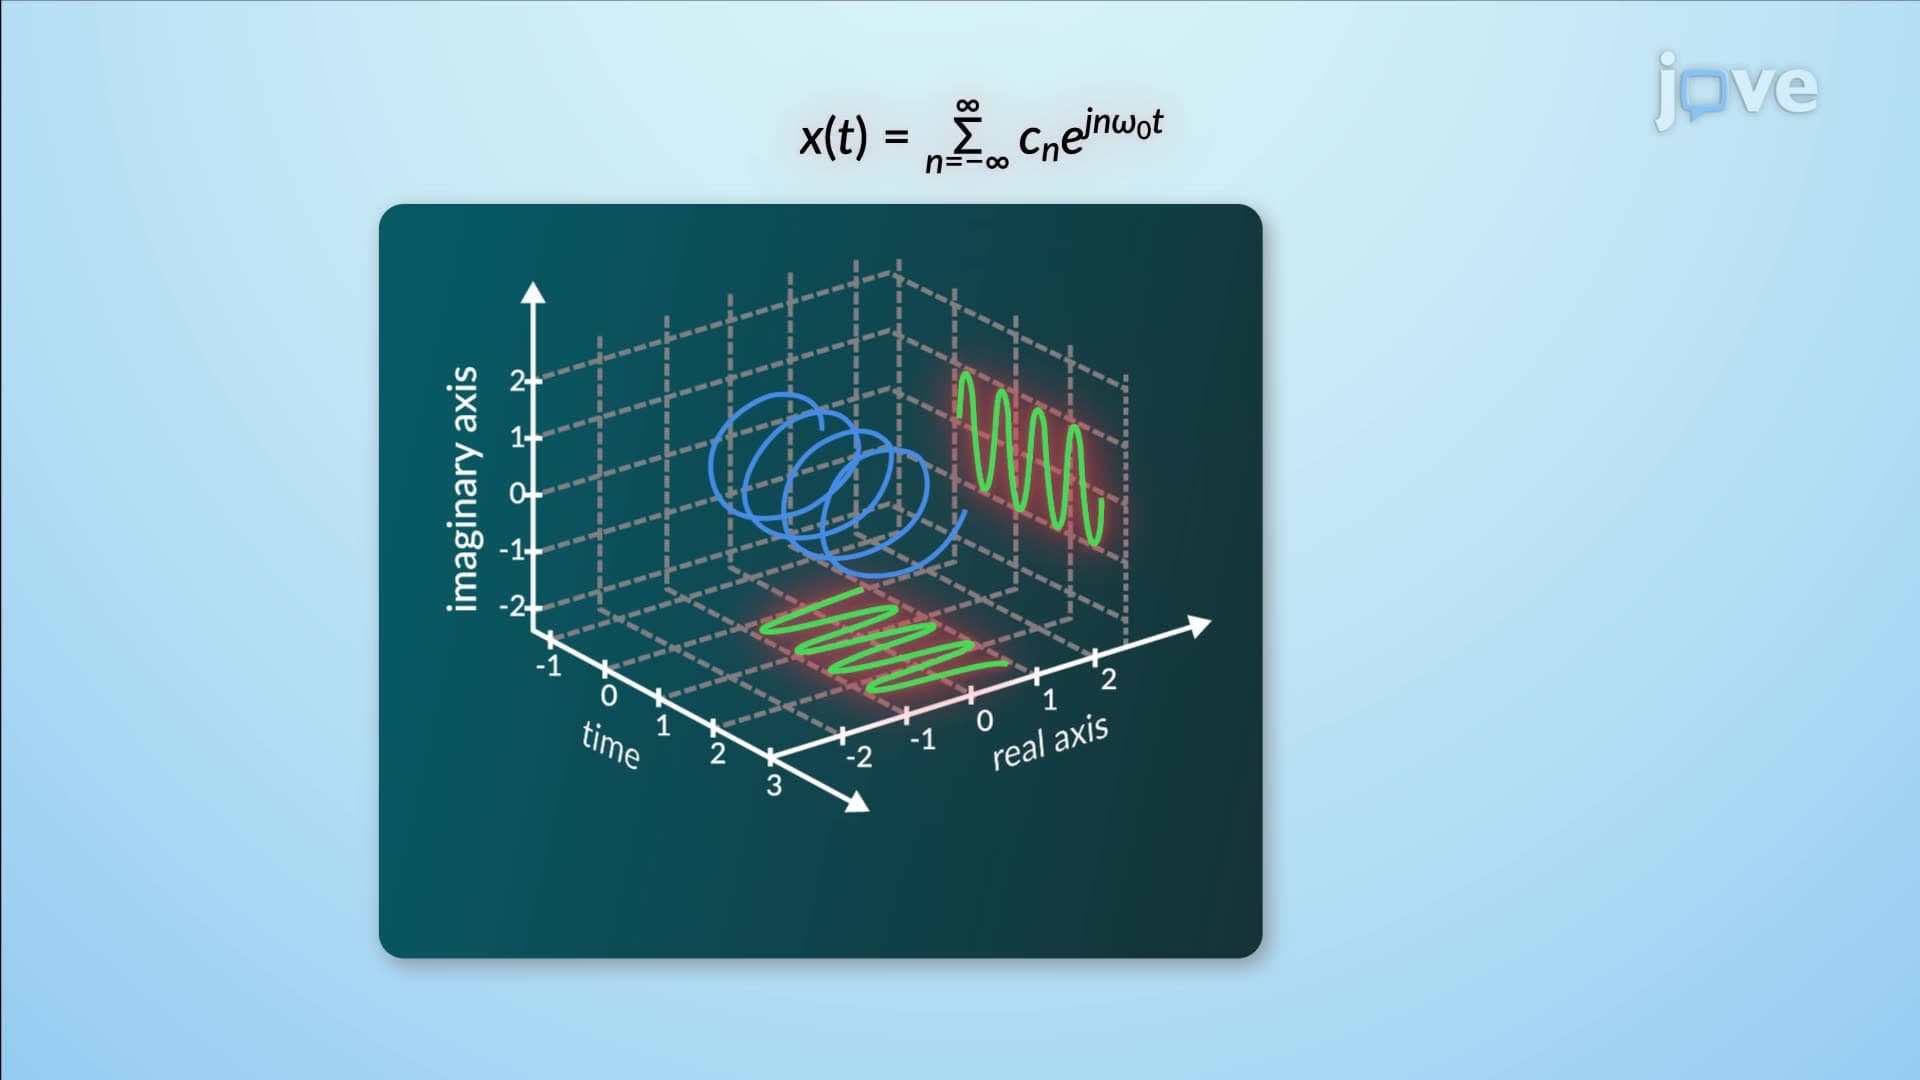
Exponential Fourier series
Euler's identity...
 01:26
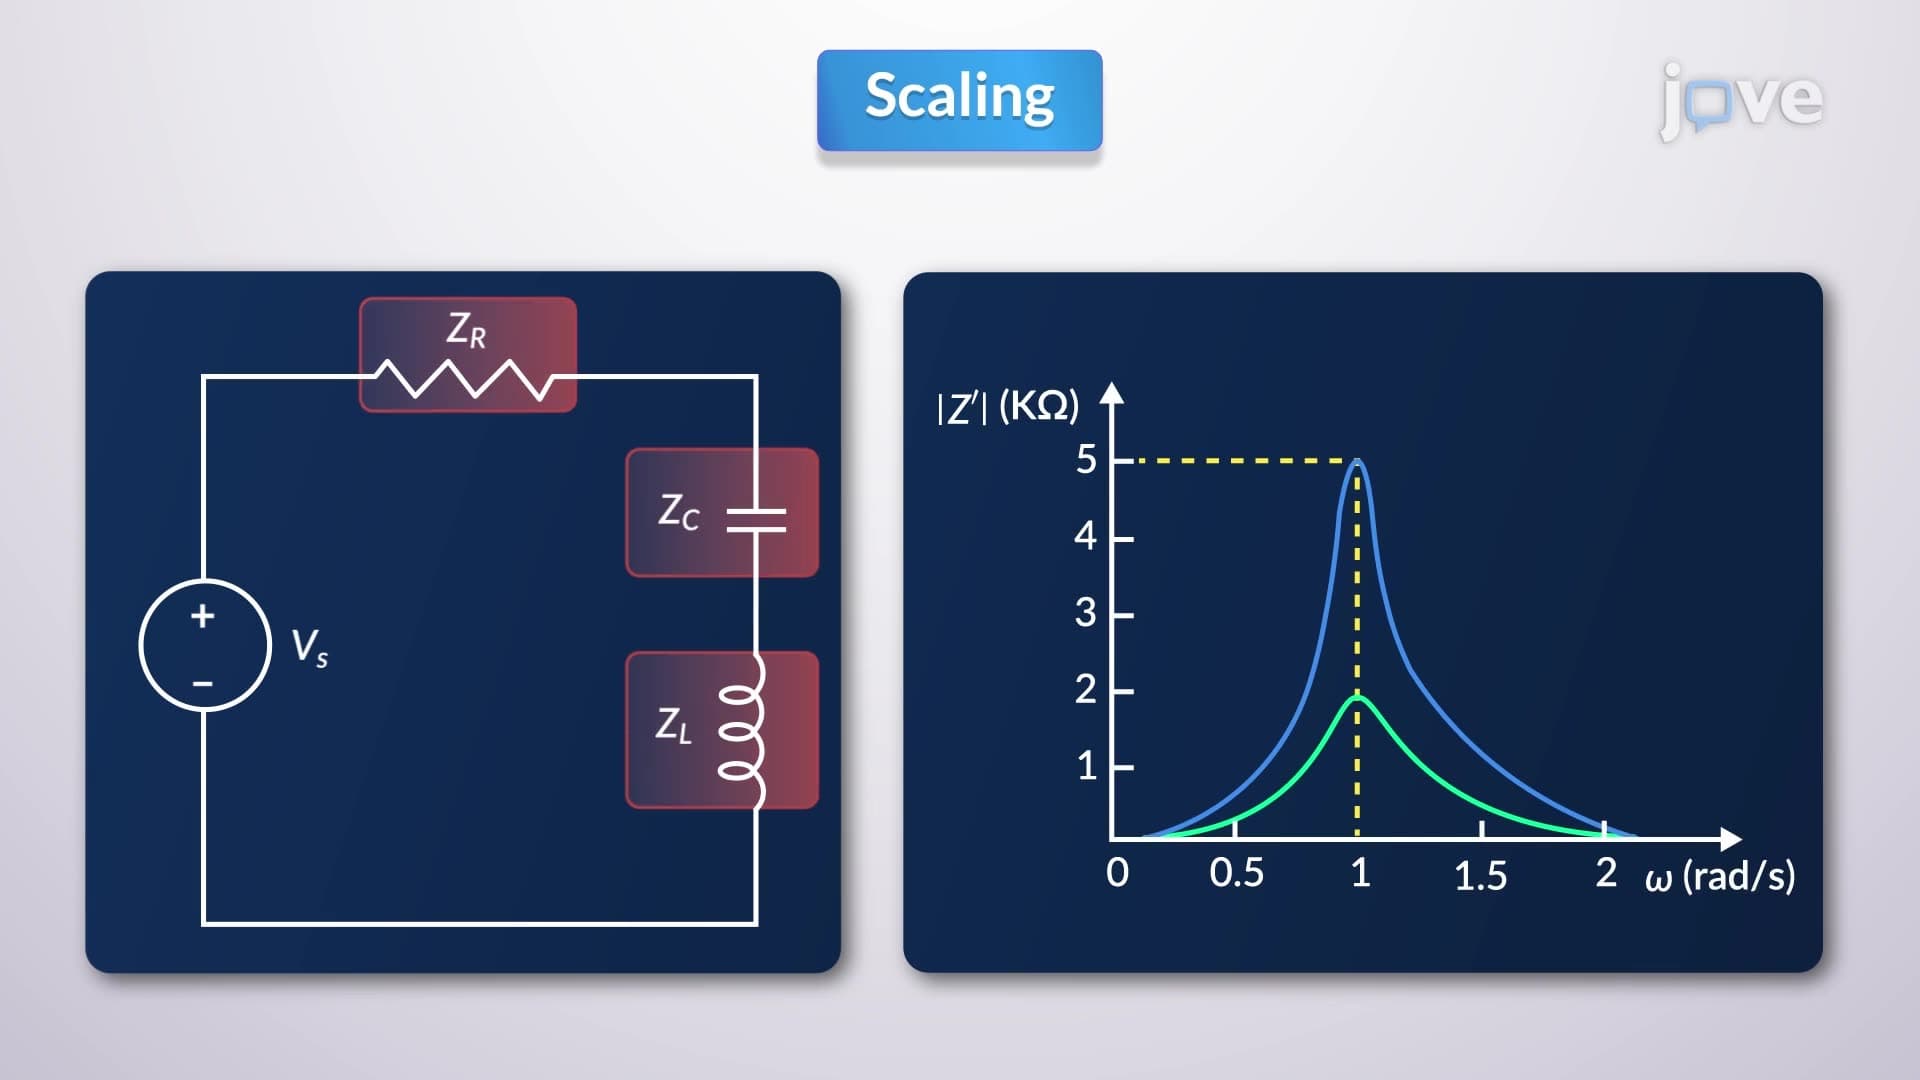
Scaling
 01:21
Properties of Fourier series II
A function f(t) is...
 01:18
Exponential and Sinusoidal Signals
 01:22
Basic Operations on Signals
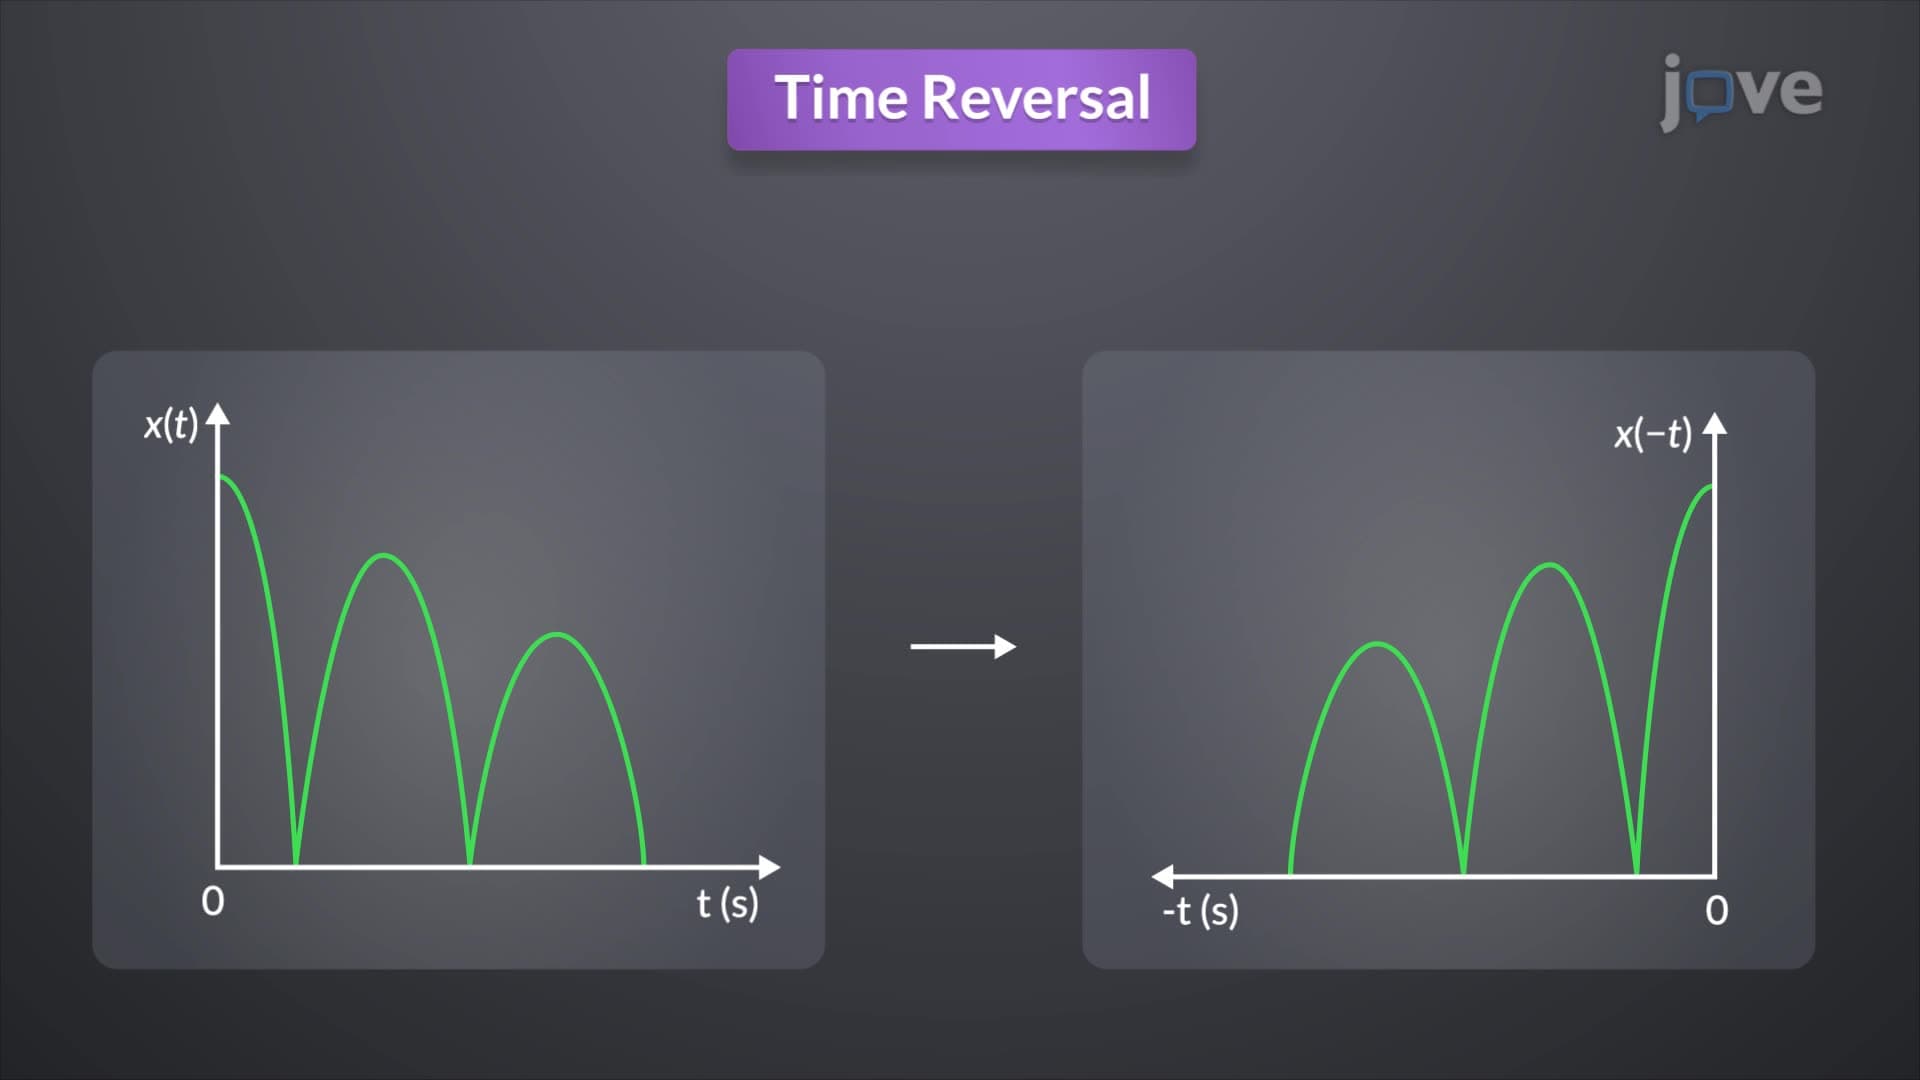
Time Reversal mirrors a continuous-time signal about the vertical axis at t=0. This is achieved by substituting t with −t. For example, if a signal x(t) is considered, the time-reversed signal is x(−t). This operation can be graphically represented, showing the mirrored signal.
 01:29
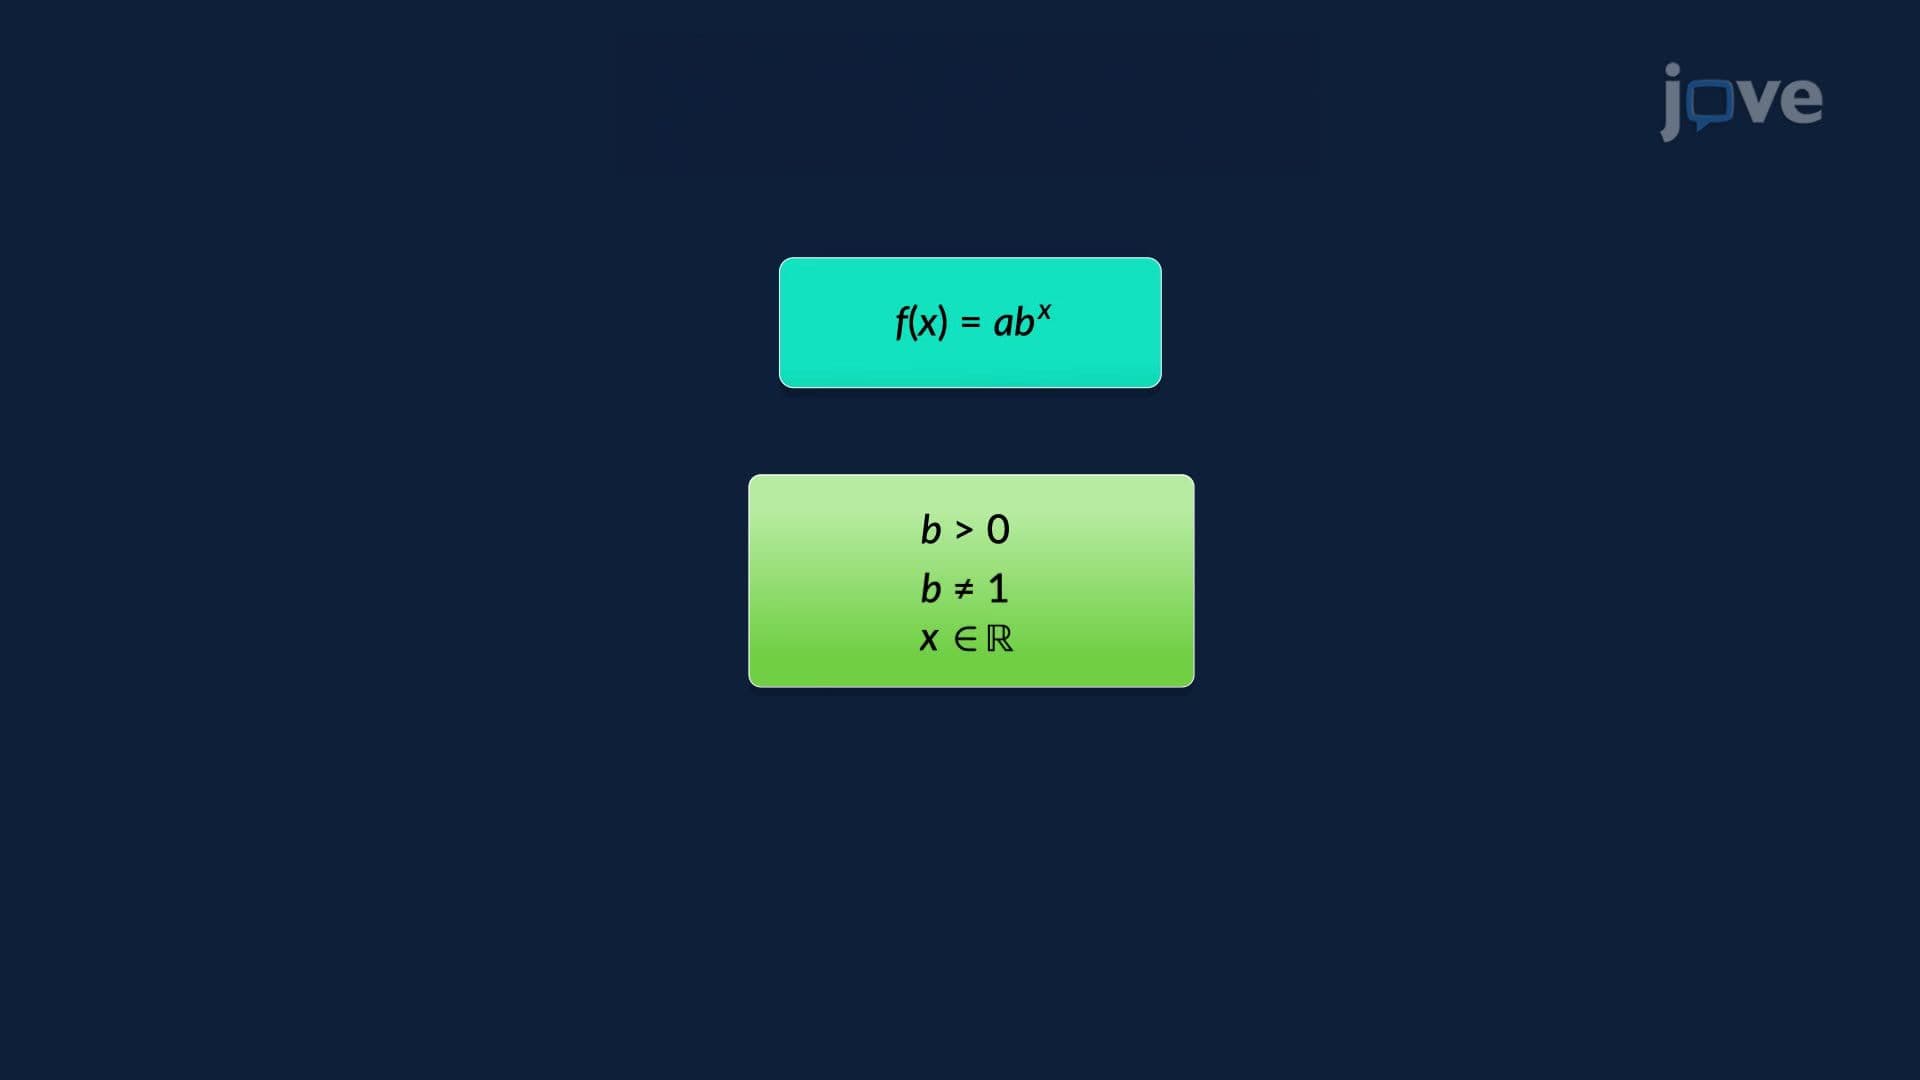
Introduction to Exponential Functions