Robust L1 principal component analysis and its Bayesian variational inference
Related Experiment Video
Updated: Jul 9, 2026

Basics of Multivariate Analysis in Neuroimaging Data
Published on: July 24, 2010
1School of Computer Science, Charles Sturt University, Bathurst, NSW, Australia. jbgao@csu.edu.au

Abstract:
We introduce a robust probabilistic L1-PCA model in which the conventional gaussian distribution for the noise in the observed data was replaced by the Laplacian distribution (or L1 distribution). Due to the heavy tail characteristics of the L1 distribution, the proposed model is supposed to be more robust against data outliers. In this letter, we demonstrate how a variational approximation scheme enables effective inference of key parameters in the probabilistic L1-PCA model. As the L1 density can be expanded as a superposition of infinite number of gaussian densities, we express the L1-PCA model as a marginalized model over the superpositions. By doing so, a tractable Bayesian inference can be achieved based on the variational expectation-maximization-type algorithm.

Related Concept Videos
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:11
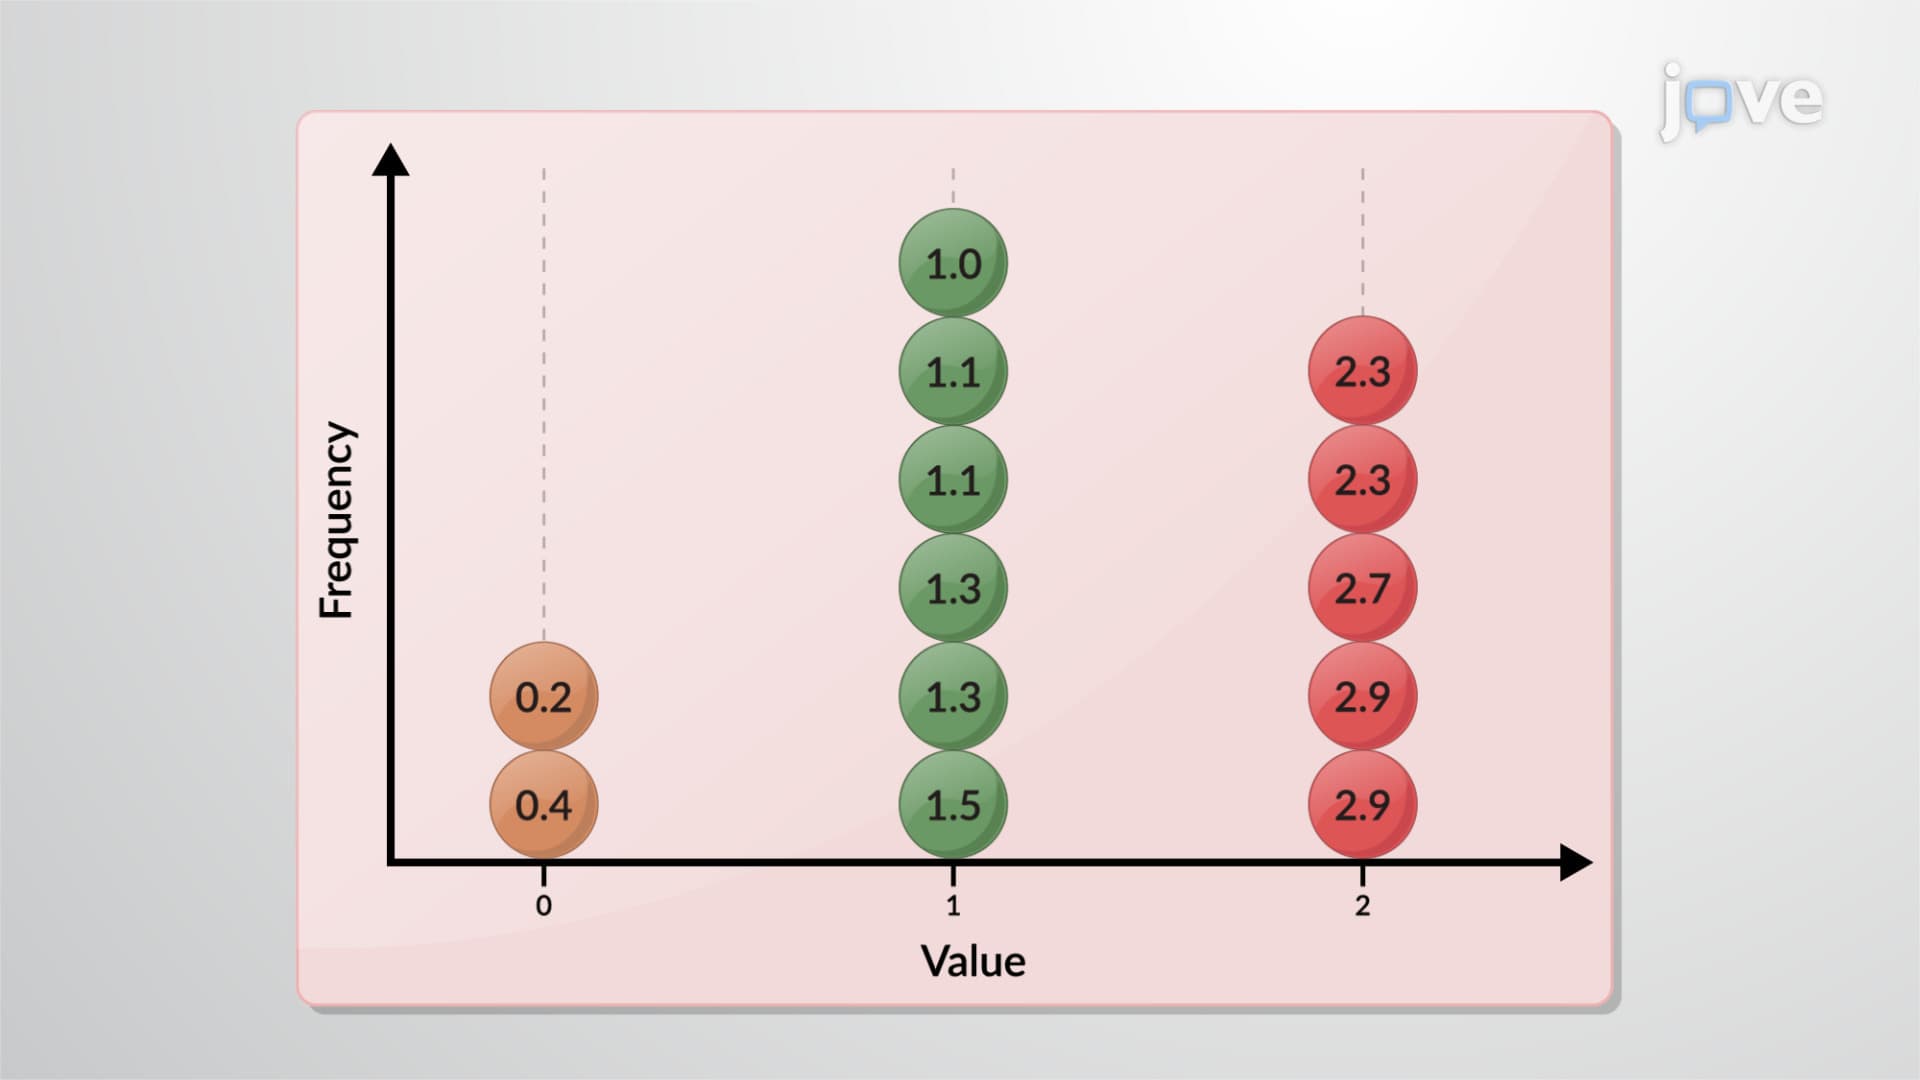
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:15
Variance
 01:14
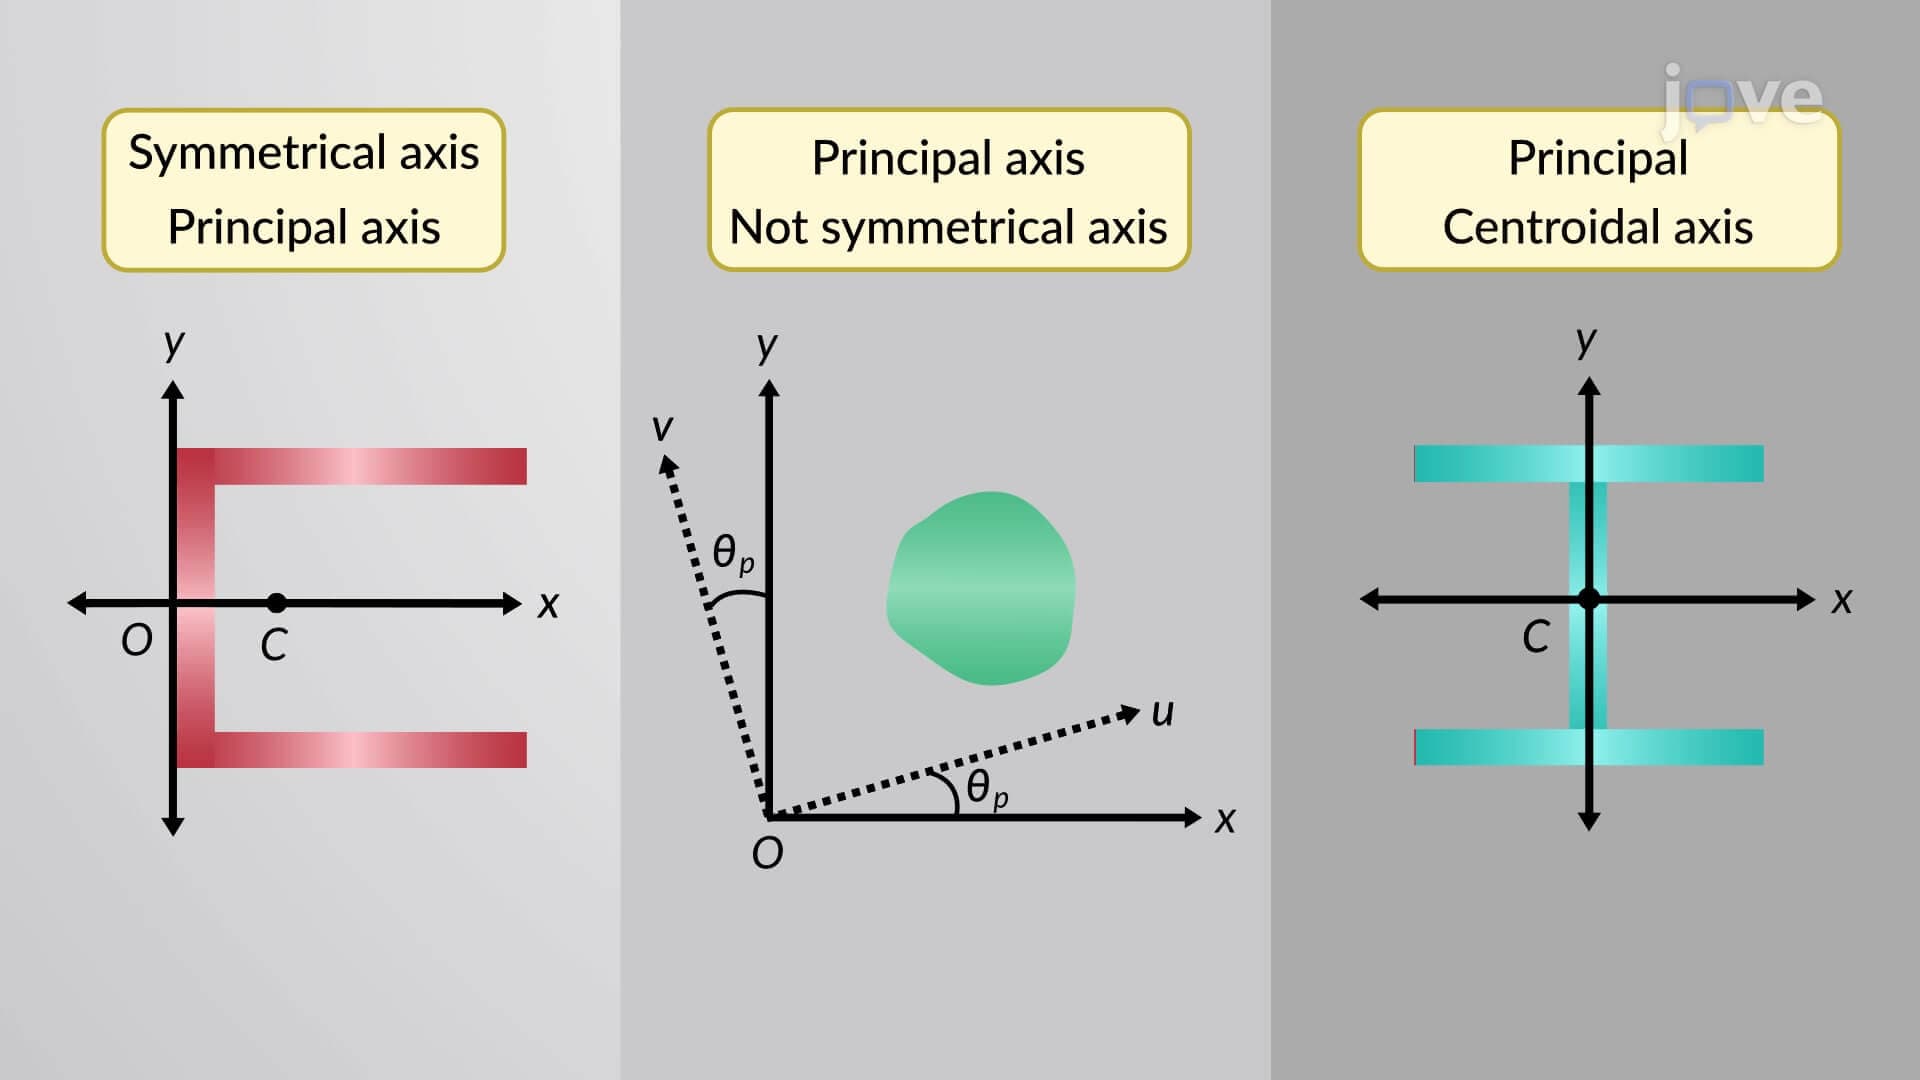
Principal Moments of Area
The principal moment of inertia axes are the...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...