Related Experiment Video
Updated: Jun 23, 2026

Age-dependent Dynamics of Locomotion in Caenorhabditis elegans: A Lyapunov Exponent Analysis
Published on: September 23, 2025
Pseudononstationarity in the scaling exponents of finite-interval time series
K H Kiyani1, S C Chapman, N W Watkins
1Department of Physics, Centre for Fusion, Space and Astrophysics, University of Warwick, Gibbet Hill Road, Coventry CV4 7AL, United Kingdom. k.kiyani@warwick.ac.uk

Abstract:
The accurate estimation of scaling exponents is central in the observational study of scale-invariant phenomena. Natural systems unavoidably provide observations over restricted intervals; consequently, a stationary stochastic process (time series) can yield anomalous time variation in the scaling exponents, suggestive of nonstationarity. The variance in the estimates of scaling exponents computed from an interval of N observations is known for finite variance processes to vary as approximately 1N as N-->infinity for certain statistical estimators; however, the convergence to this behavior will depend on the details of the process, and may be slow. We study the variation in the scaling of second-order moments of the time-series increments with N for a variety of synthetic and "real world" time series, and we find that in particular for heavy tailed processes, for realizable N , one is far from this approximately 1N limiting behavior. We propose a semiempirical estimate for the minimum N needed to make a meaningful estimate of the scaling exponents for model stochastic processes and compare these with some "real world" time series.

Related Concept Videos
 01:26
Scaling
 01:26
Exponential Equations for Modeling Growth
 01:18
Exponential and Sinusoidal Signals
 01:21
Properties of Fourier series II
A function f(t) is...
 01:29
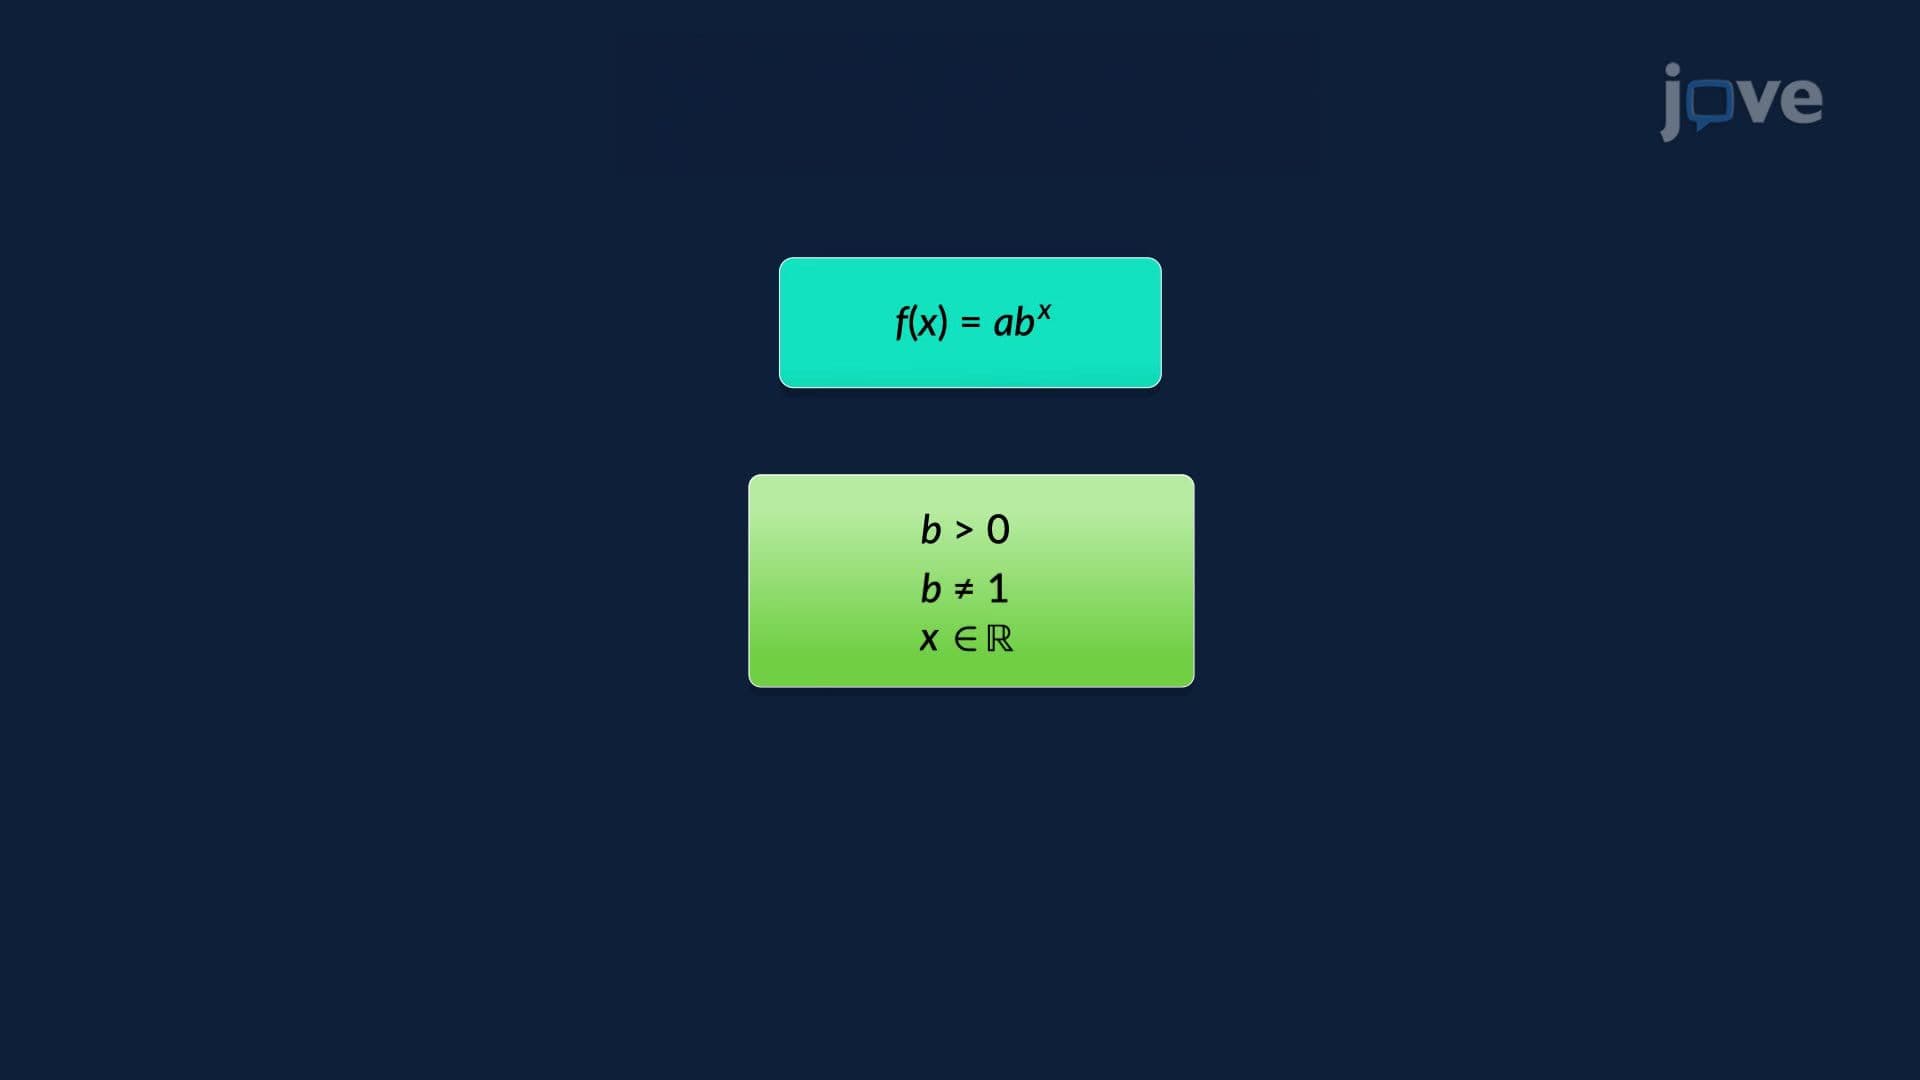
Introduction to Exponential Functions
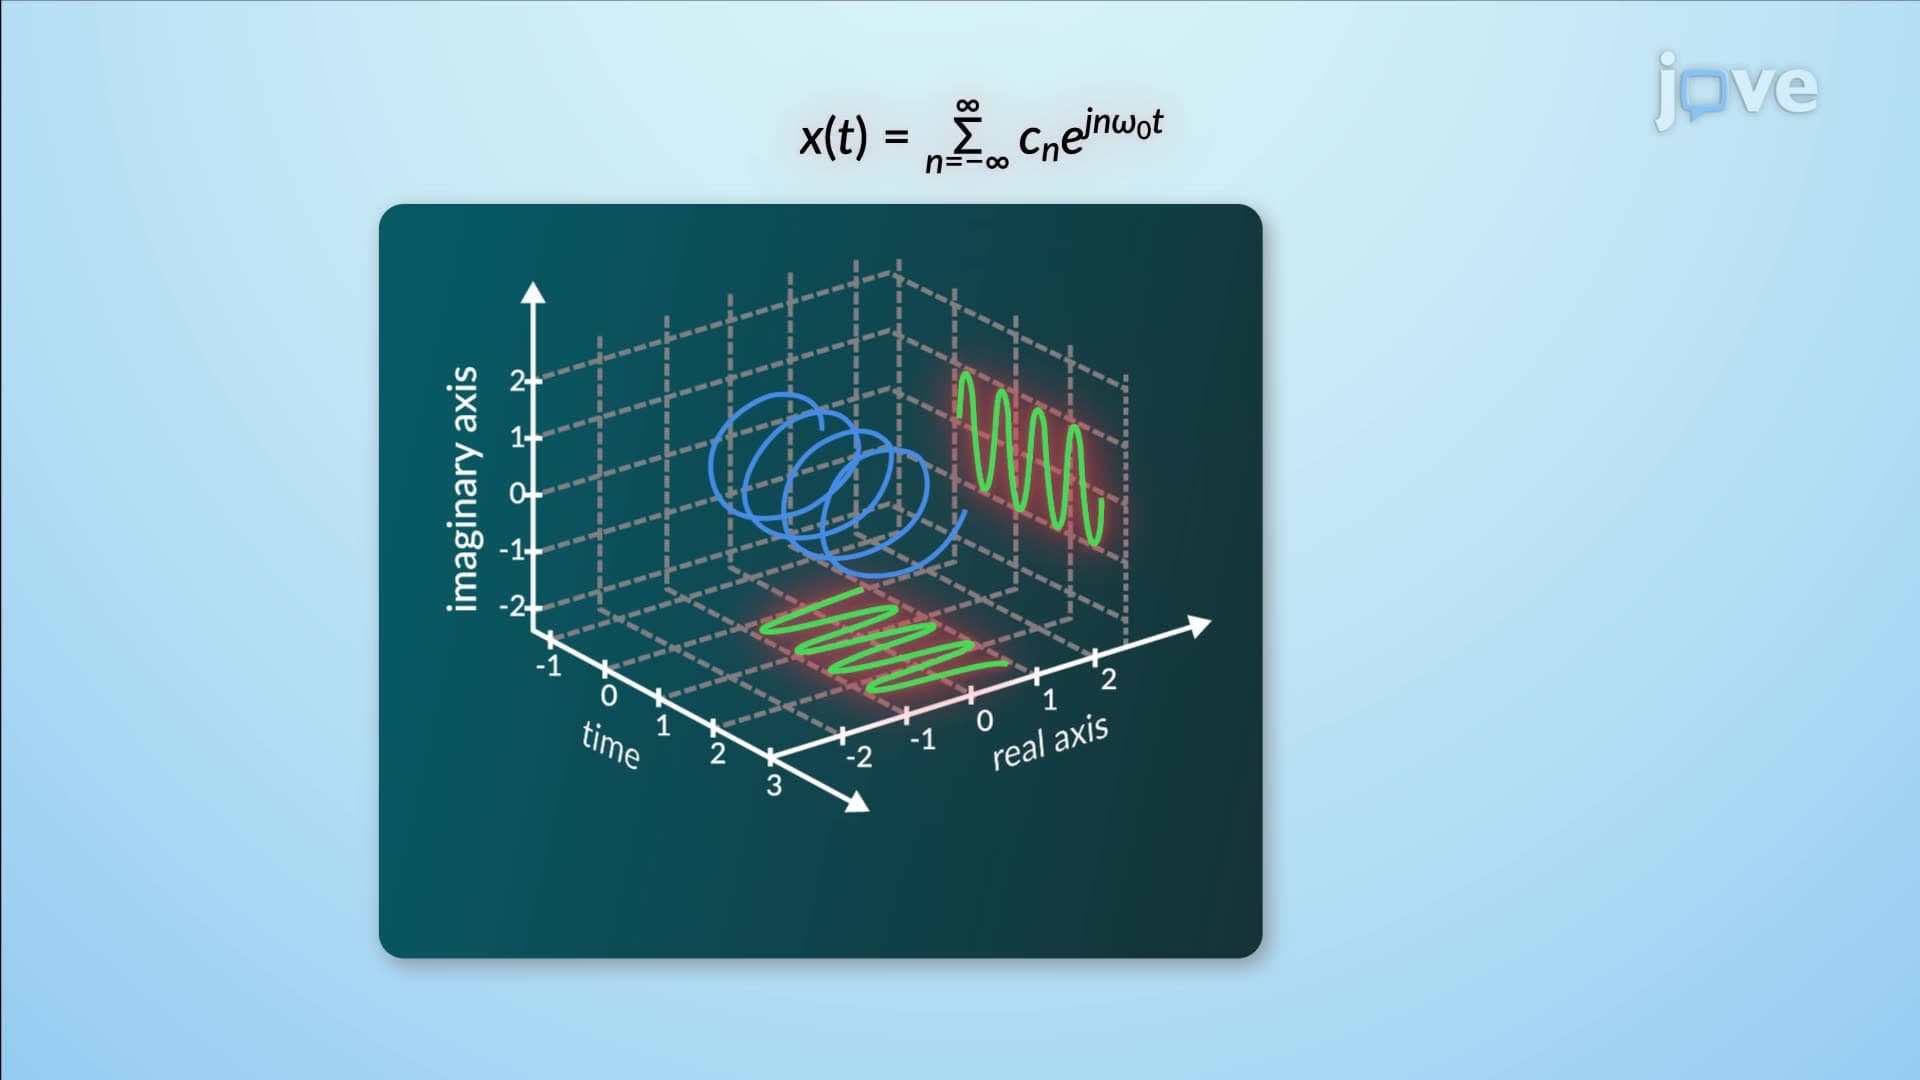 01:24
Exponential Fourier series
Euler's identity...