Related Experiment Videos
Density-weighted Nyström method for computing large kernel eigensystems
1Department of Computer Science and Engineering, Hong Kong University of Science and Technology, Clear Water Bay, Kowloon, Hong Kong. twinsen@cse.ust.hk

Abstract:
The Nyström method is a well-known sampling-based technique for approximating the eigensystem of large kernel matrices. However, the chosen samples in the Nyström method are all assumed to be of equal importance, which deviates from the integral equation that defines the kernel eigenfunctions. Motivated by this observation, we extend the Nyström method to a more general, density-weighted version. We show that by introducing the probability density function as a natural weighting scheme, the approximation of the eigensystem can be greatly improved. An efficient algorithm is proposed to enforce such weighting in practice, which has the same complexity as the original Nyström method and hence is notably cheaper than several other alternatives. Experiments on kernel principal component analysis, spectral clustering, and image segmentation demonstrate the encouraging performance of our algorithm.
Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:30
Gaussian Elimination: Problem Solving
 01:20
Maxwell-Boltzmann Distribution: Problem Solving
This distribution function f(v) is defined by saying that the expected number N (v1,v2) of particles with speeds between v1 and v2 is given by
 01:14
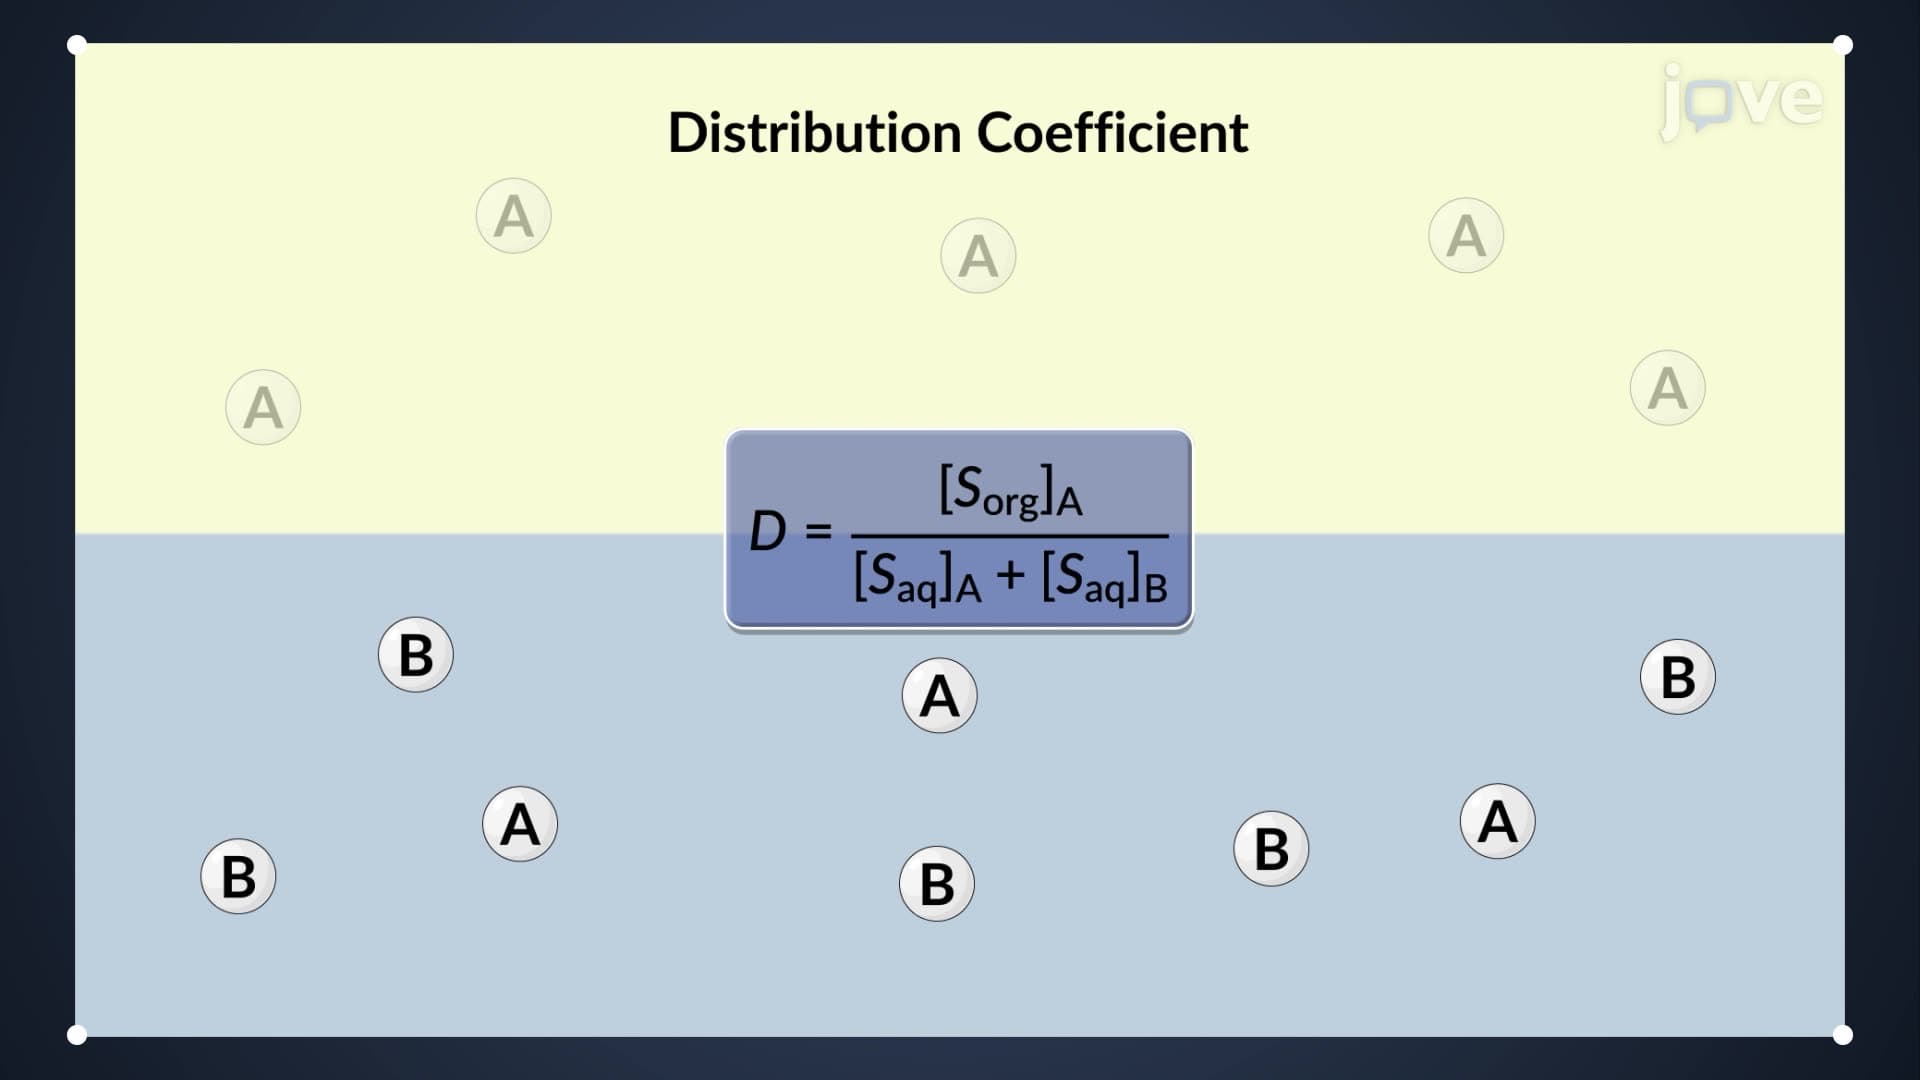
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an organic...
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...