Robust kernel principal component analysis
Related Experiment Video
Updated: Jun 20, 2026

Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Su-Yun Huang1, Yi-Ren Yeh, Shinto Eguchi
1Institute of Statistical Science, Academia Sinica, Taipei, Taiwan. syhuang@stat.sinica.edu.tw

Abstract:
This letter discusses the robustness issue of kernel principal component analysis. A class of new robust procedures is proposed based on eigenvalue decomposition of weighted covariance. The proposed procedures will place less weight on deviant patterns and thus be more resistant to data contamination and model deviation. Theoretical influence functions are derived, and numerical examples are presented as well. Both theoretical and numerical results indicate that the proposed robust method outperforms the conventional approach in the sense of being less sensitive to outliers. Our robust method and results also apply to functional principal component analysis.


Related Concept Videos
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...
 01:14
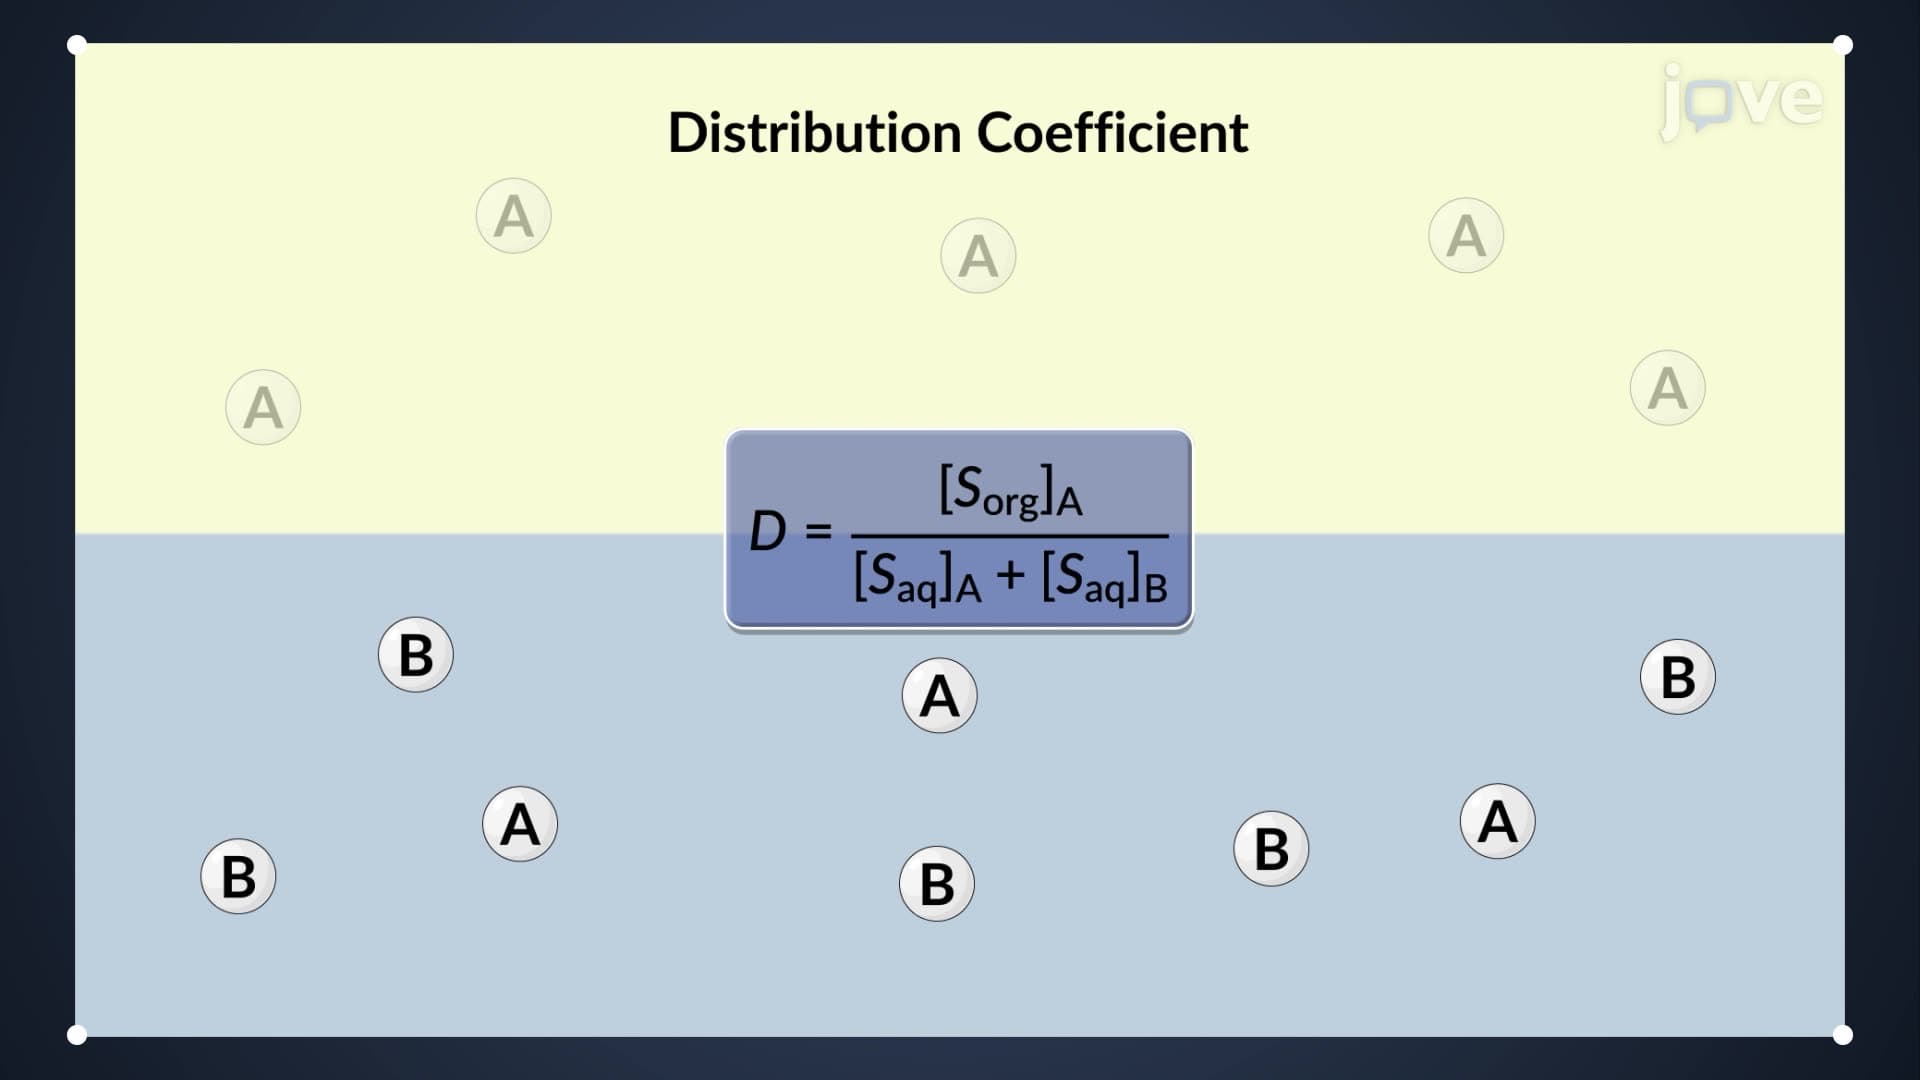
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an organic...
 01:02
Quantifying and Rejecting Outliers: The Grubbs Test
 01:14
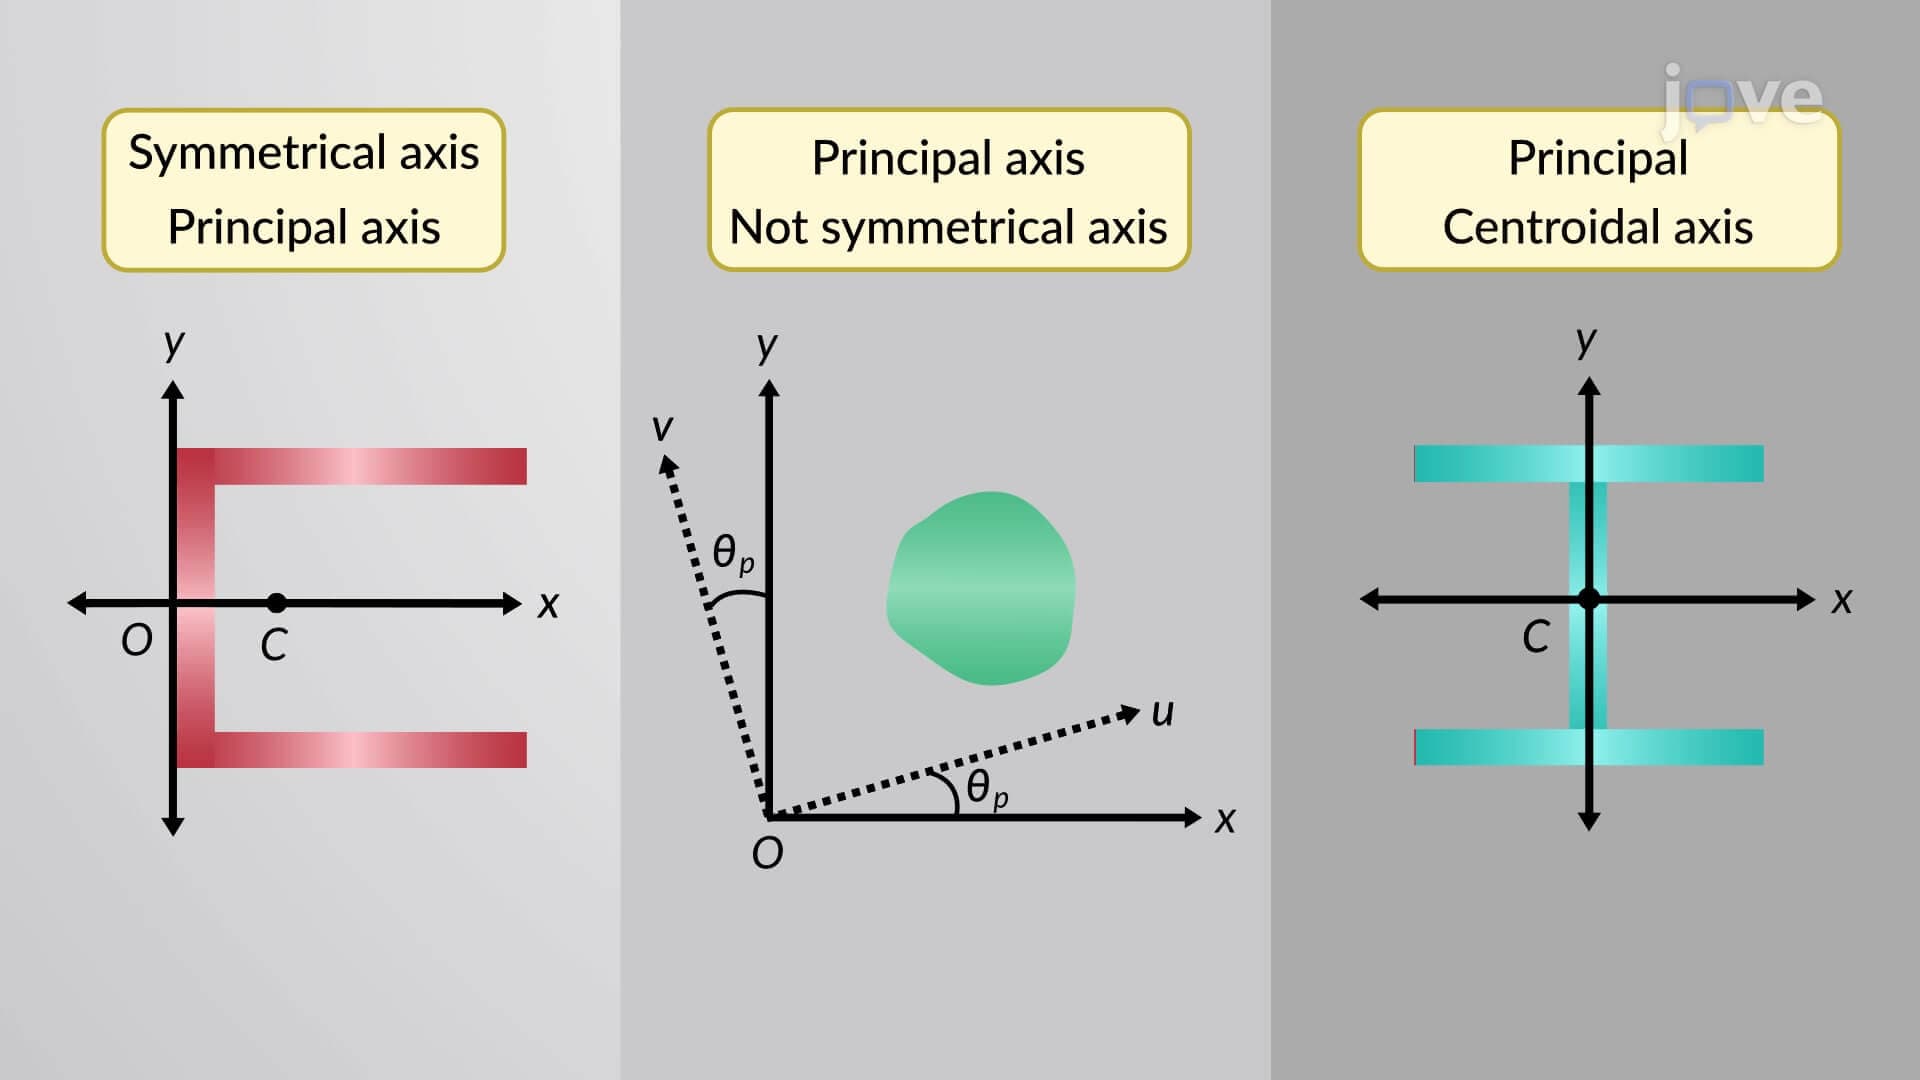
Principal Moments of Area
The principal moment of inertia axes are the...
 01:11
Statistical Analysis: Overview
One of the most commonly used statistical quantifiers is the mean, which is the ratio between the sum of the numerical values of all results and the...
 01:12
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the strength of the linear...