Related Experiment Video
Updated: Jun 3, 2026

Modeling the Size Spectrum for Macroinvertebrates and Fishes in Stream Ecosystems
Published on: July 30, 2019
Emergence of universal scaling in financial markets from mean-field dynamics
1Department of Physics, Indian Institute of Technology Madras, Chennai 600036, India.

Abstract:
Collective phenomena with universal properties have been observed in many complex systems with a large number of components. Here we present a microscopic model of the emergence of scaling behavior in such systems, where the interaction dynamics between individual components is mediated by a global variable making the mean-field description exact. Using the example of financial markets, we show that asset price can be such a global variable with the critical role of coordinating the actions of agents who are otherwise independent. The resulting model accurately reproduces empirical properties such as the universal scaling of the price fluctuation and volume distributions, long-range correlations in volatility, and multiscaling.
Related Concept Videos
 01:26
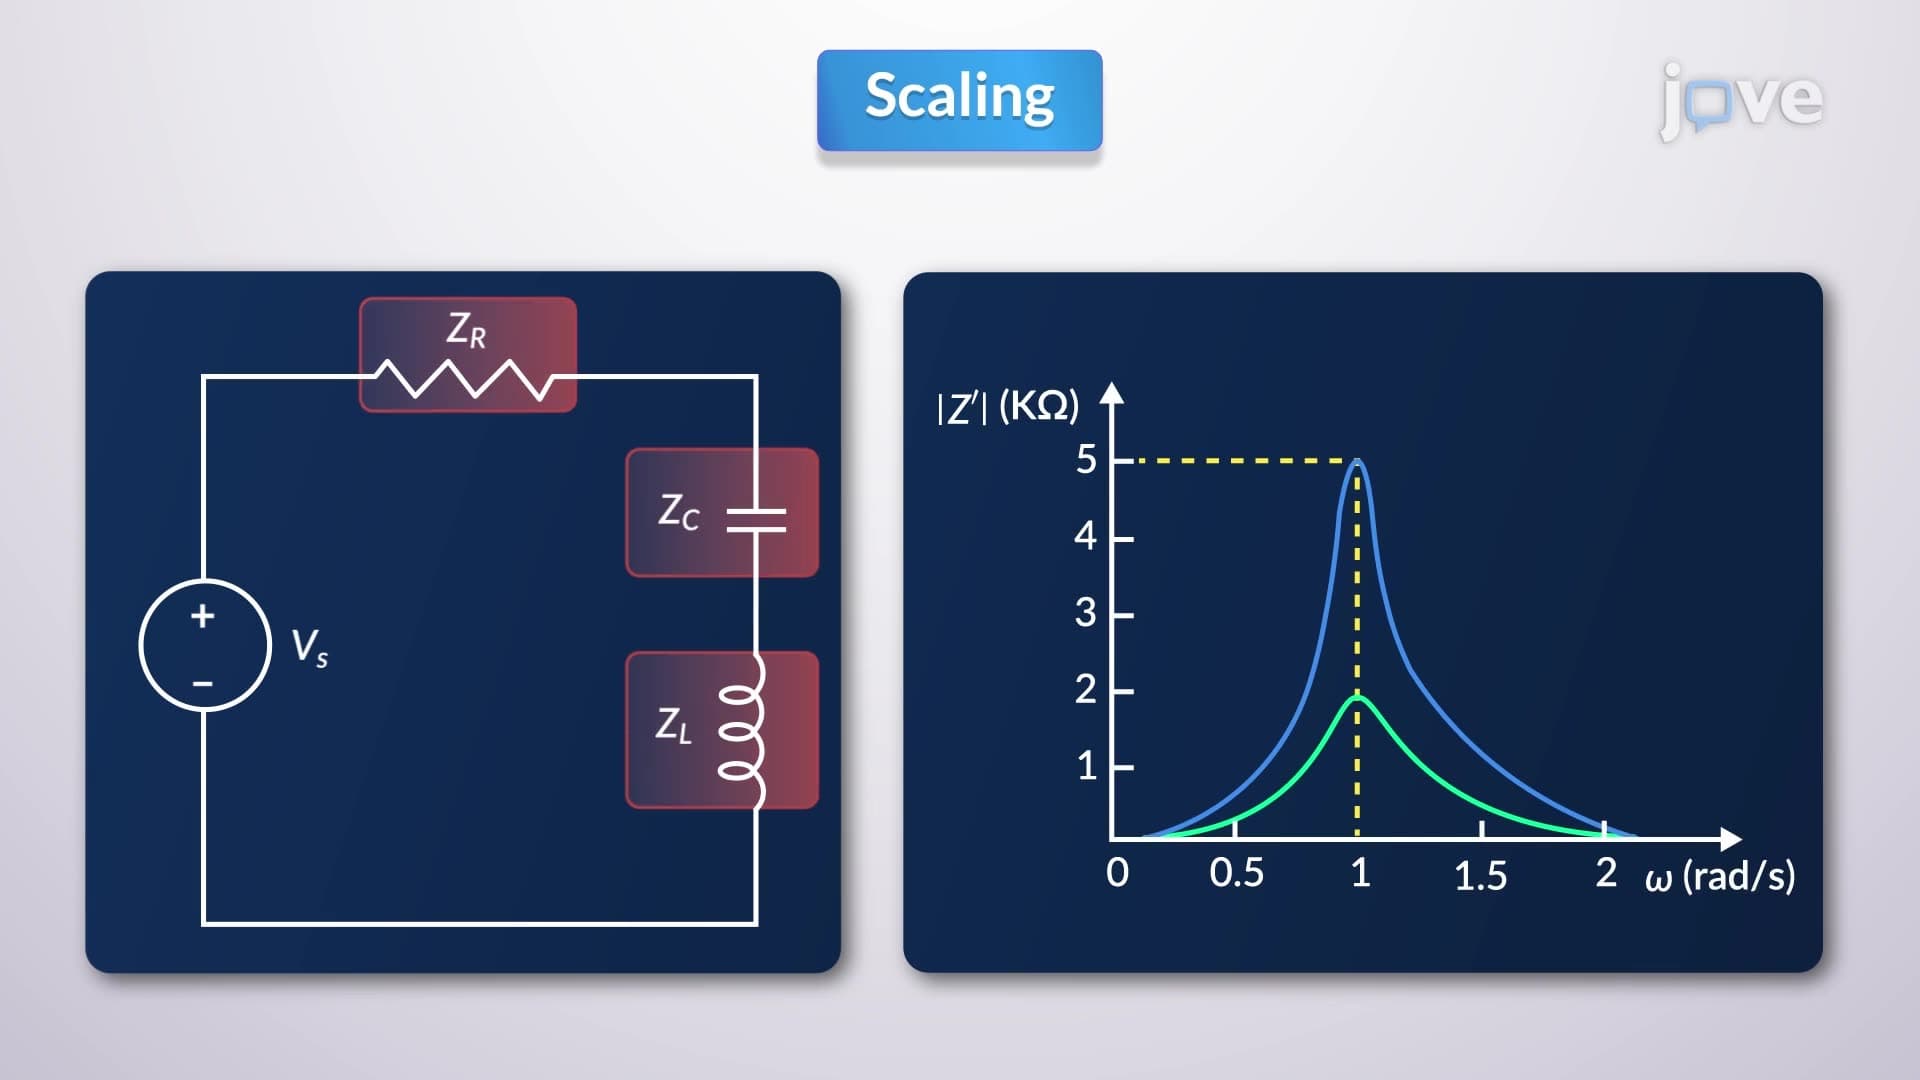
Scaling
 01:52
Regression Toward the Mean
 01:25
Modeling with Differential Equations
 01:30
Typical Model Studies
 01:30
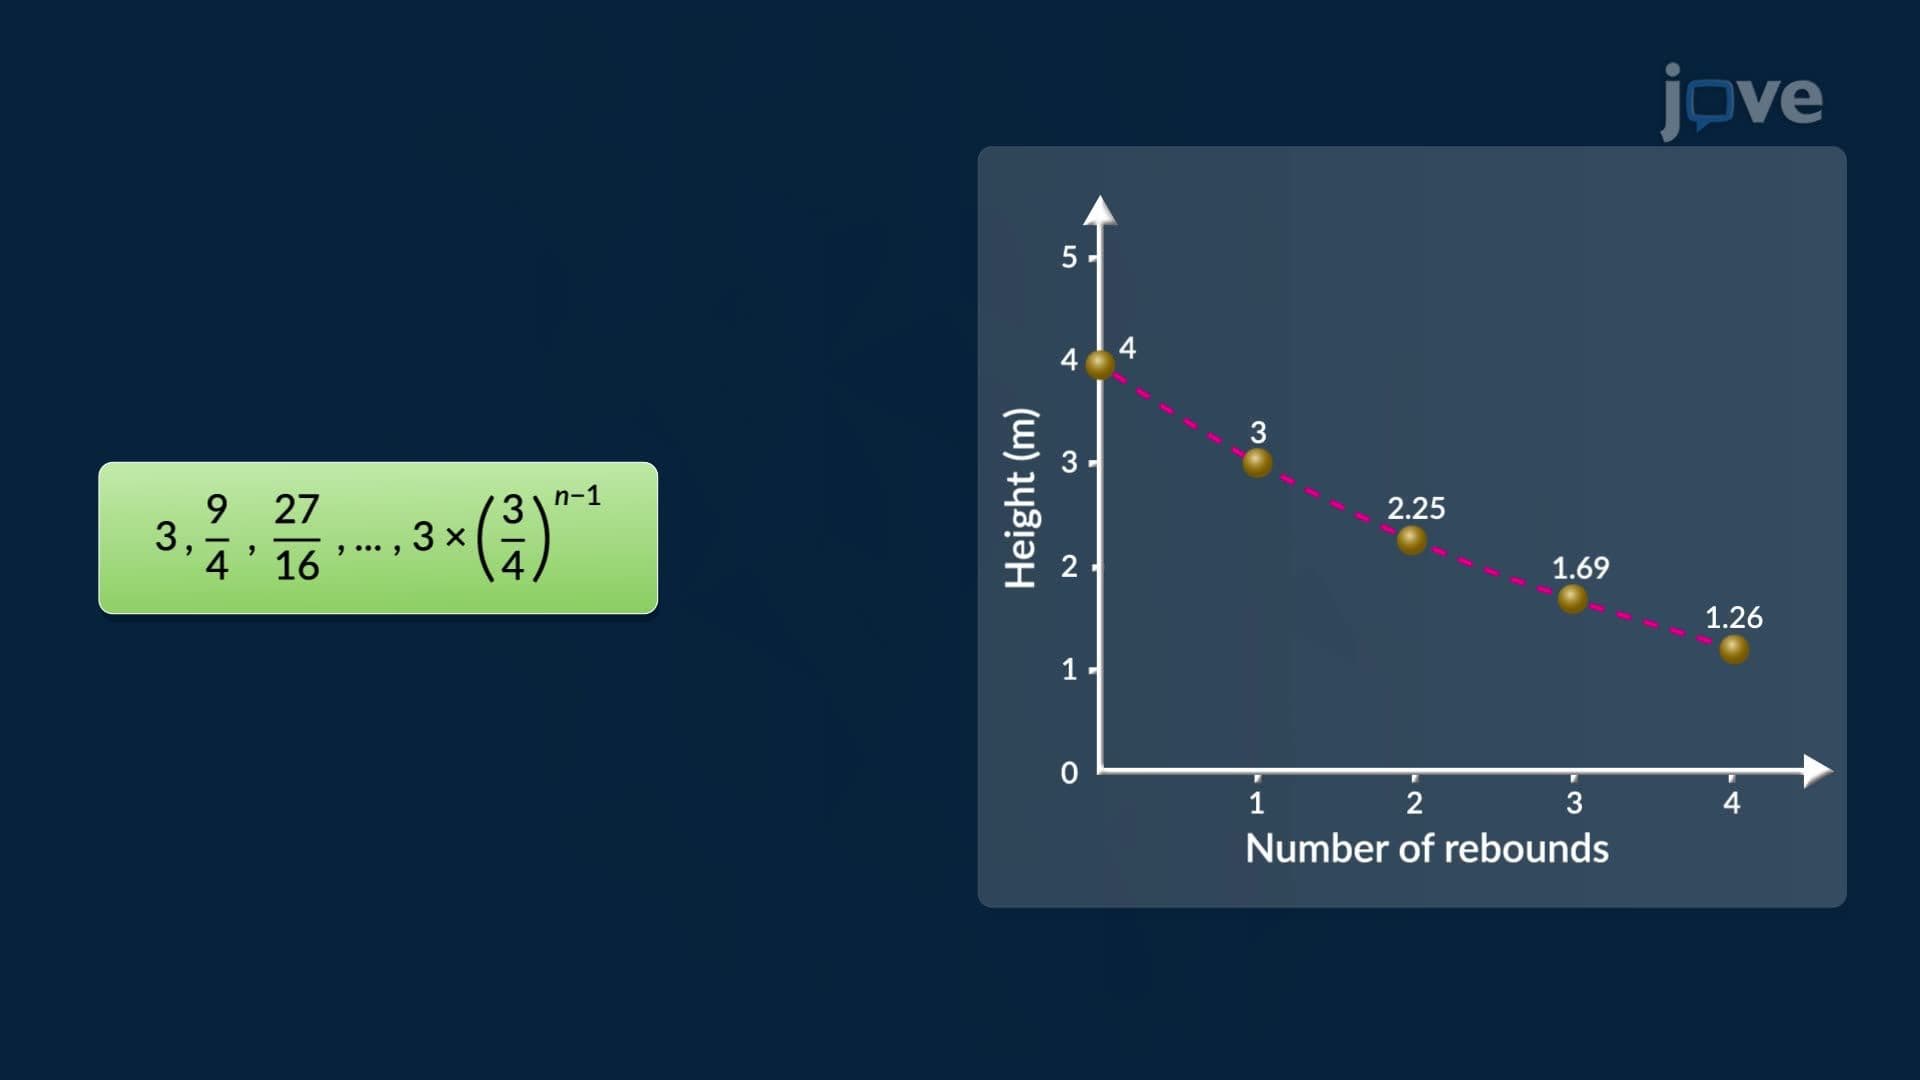
Geometric Sequences
 01:12
Modeling and Similitude