Related Experiment Video
Updated: May 17, 2026
Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Sparse estimation of a covariance matrix
Jacob Bien1, Robert J Tibshirani
1Departments of Statistics and Health, Research & Policy, Stanford University, Sequoia Hall, 390 Serra Mall, Stanford, California 94305-4065, U.S.A.

Abstract:
We suggest a method for estimating a covariance matrix on the basis of a sample of vectors drawn from a multivariate normal distribution. In particular, we penalize the likelihood with a lasso penalty on the entries of the covariance matrix. This penalty plays two important roles: it reduces the effective number of parameters, which is important even when the dimension of the vectors is smaller than the sample size since the number of parameters grows quadratically in the number of variables, and it produces an estimate which is sparse. In contrast to sparse inverse covariance estimation, our method's close relative, the sparsity attained here is in the covariance matrix itself rather than in the inverse matrix. Zeros in the covariance matrix correspond to marginal independencies; thus, our method performs model selection while providing a positive definite estimate of the covariance. The proposed penalized maximum likelihood problem is not convex, so we use a majorize-minimize approach in which we iteratively solve convex approximations to the original nonconvex problem. We discuss tuning parameter selection and demonstrate on a flow-cytometry dataset how our method produces an interpretable graphical display of the relationship between variables. We perform simulations that suggest that simple elementwise thresholding of the empirical covariance matrix is competitive with our method for identifying the sparsity structure. Additionally, we show how our method can be used to solve a previously studied special case in which a desired sparsity pattern is prespecified.
Related Concept Videos
 01:26
Estimating Population Standard Deviation
 01:22
Estimating Population Mean with Unknown Standard Deviation
William S. Gosset (1876–1937) of the Guinness...
 01:16
Estimating Population Mean with Known Standard Deviation
The confidence interval estimate will have the form as follows:
(point estimate - error bound, point estimate + error bound)
The...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:05
Estimation of the Physical Quantities
 01:14
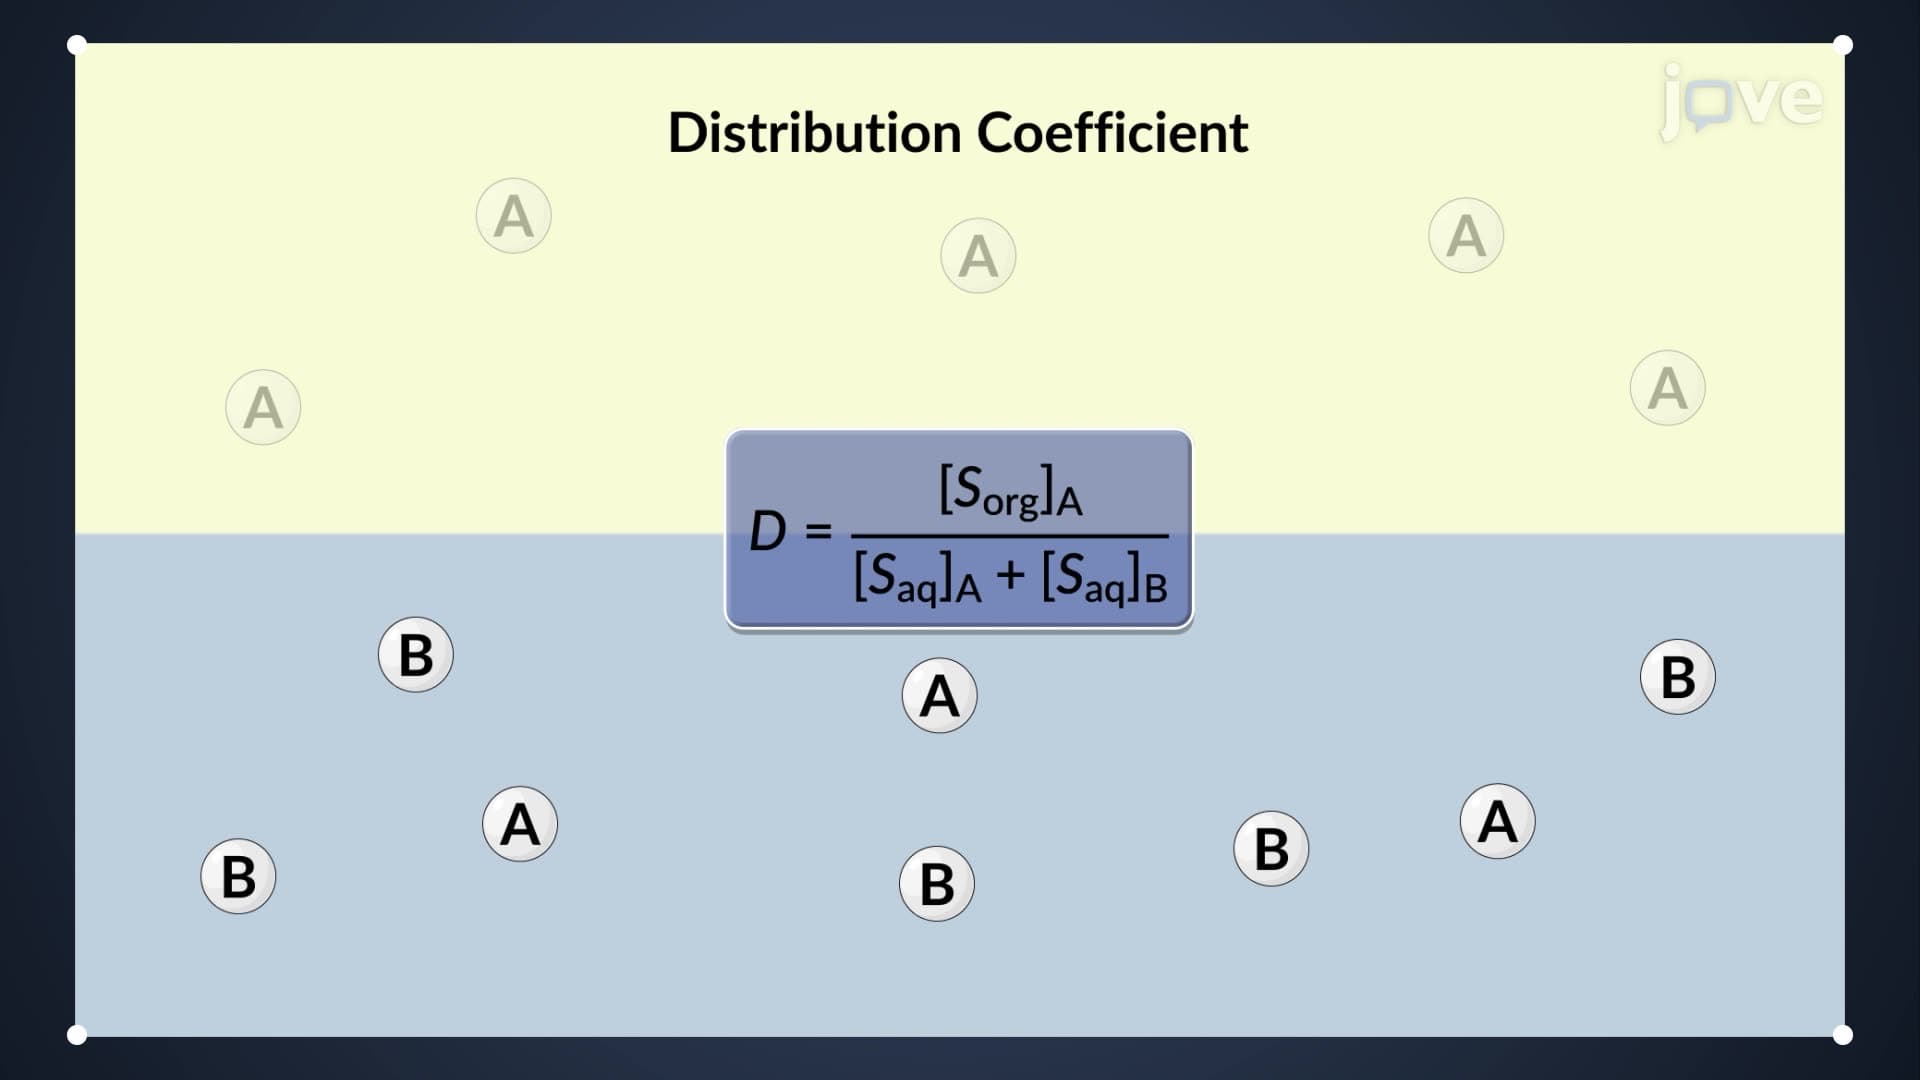
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an organic...