Related Experiment Video
Updated: May 3, 2026

Fast Imaging Technique to Study Drop Impact Dynamics of Non-Newtonian Fluids
Published on: March 5, 2014
Liquidity spillover in international stock markets through distinct time scales
Marcelo Brutti Righi1, Kelmara Mendes Vieira1
1Federal University of Santa Maria, Department of Business, Santa Maria, Rio Grande do Sul, Brazil.

Abstract:
This paper identifies liquidity spillovers through different time scales based on a wavelet multiscaling method. We decompose daily data from U.S., British, Brazilian and Hong Kong stock markets indices in order to calculate the scale correlation between their illiquidities. The sample is divided in order to consider non-crisis, sub-prime crisis and Eurozone crisis. We find that there are changes in correlations of distinct scales and different periods. Association in finest scales is smaller than in coarse scales. There is a rise on associations in periods of crisis. In frequencies, there is predominance for significant distinctions involving the coarsest scale, while for crises periods there is predominance for distinctions on the finest scale.
Related Concept Videos
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 01:07
Speciation Rates
 00:54
Distribution and Dispersion
 01:25
Drug Distribution: Volume of Distribution
 02:39
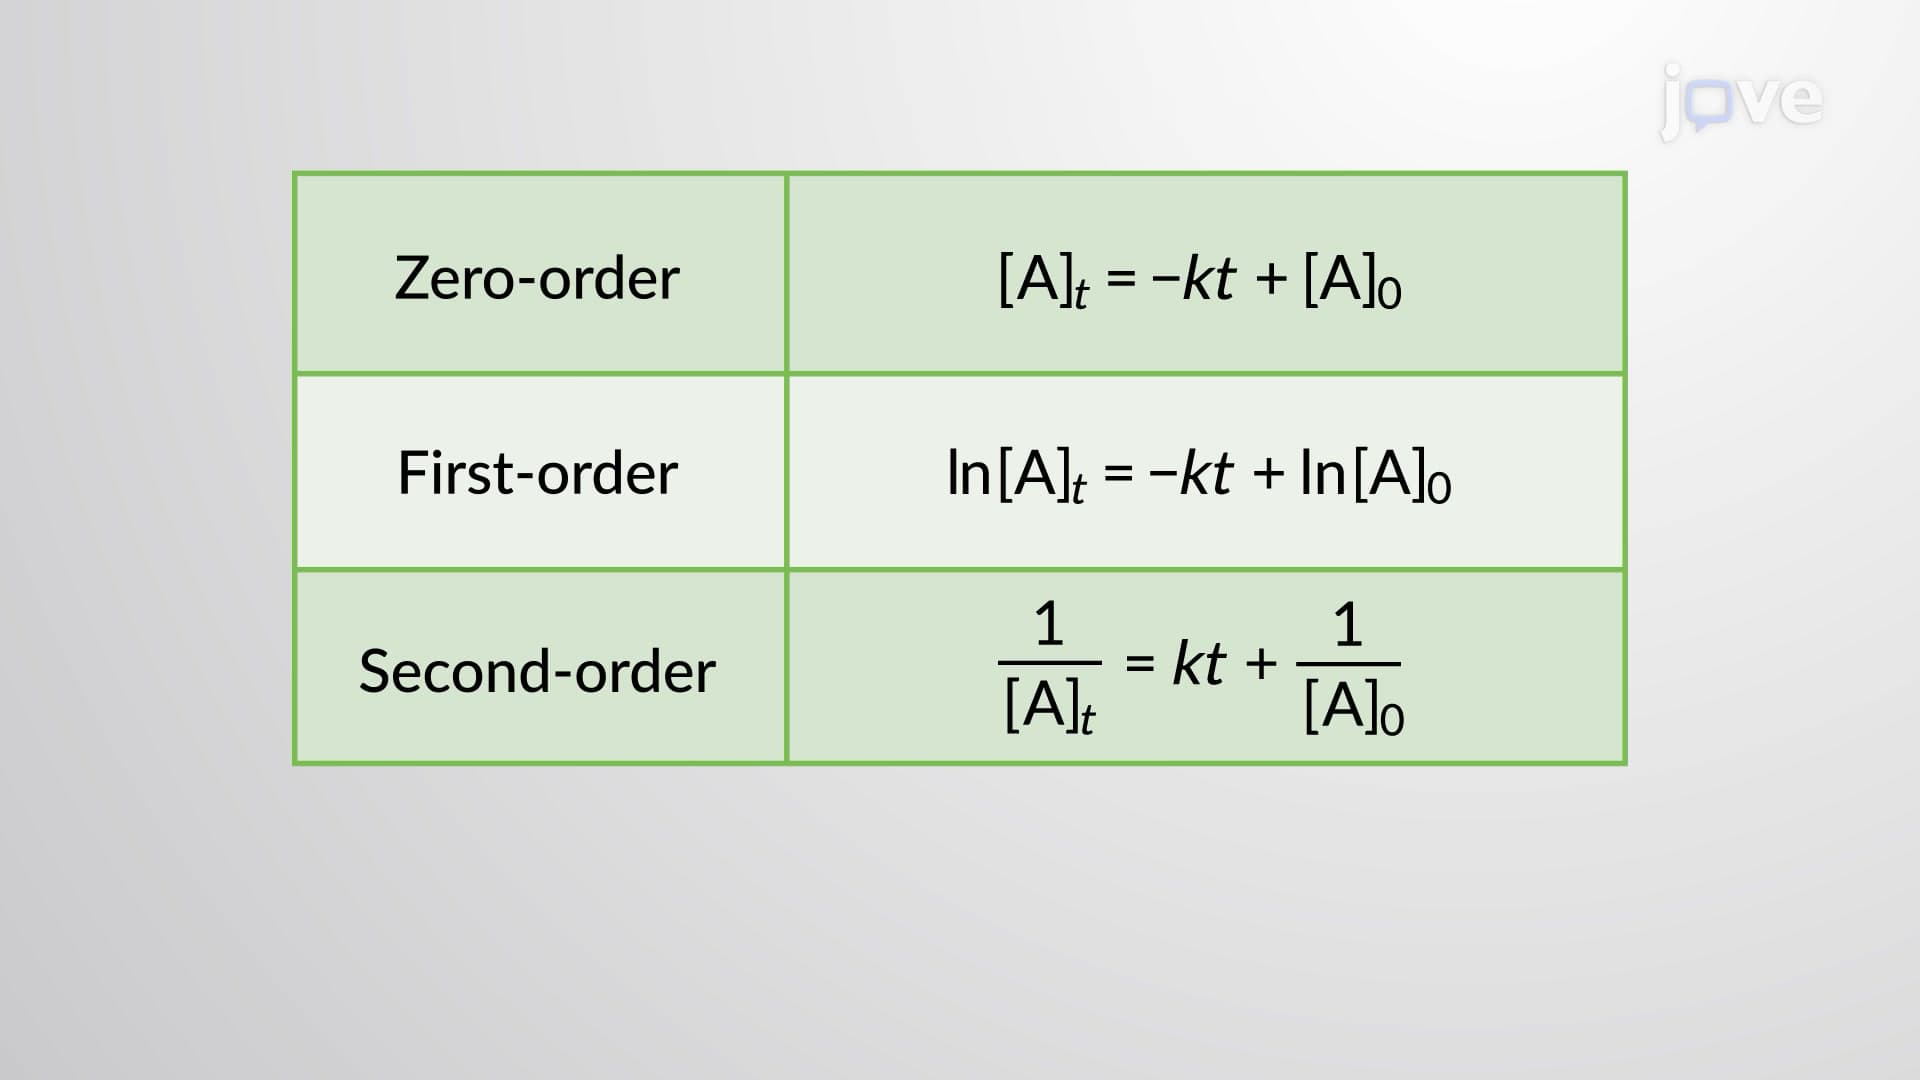
The Integrated Rate Law: The Dependence of Concentration on Time
 01:28
Capillary Exchange