Related Experiment Video
Updated: Mar 19, 2026


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Using Quantile and Asymmetric Least Squares Regression for Optimal Risk Adjustment
1Department of Economics, University of Trier, Trier, Germany.

Abstract:
In this paper, we analyze optimal risk adjustment for direct risk selection (DRS). Integrating insurers' activities for risk selection into a discrete choice model of individuals' health insurance choice shows that DRS has the structure of a contest. For the contest success function (csf) used in most of the contest literature (the Tullock-csf), optimal transfers for a risk adjustment scheme have to be determined by means of a restricted quantile regression, irrespective of whether insurers are primarily engaged in positive DRS (attracting low risks) or negative DRS (repelling high risks). This is at odds with the common practice of determining transfers by means of a least squares regression. However, this common practice can be rationalized for a new csf, but only if positive and negative DRSs are equally important; if they are not, optimal transfers have to be calculated by means of a restricted asymmetric least squares regression. Using data from German and Swiss health insurers, we find considerable differences between the three types of regressions. Optimal transfers therefore critically depend on which csf represents insurers' incentives for DRS and, if it is not the Tullock-csf, whether insurers are primarily engaged in positive or negative DRS. Copyright © 2016 John Wiley & Sons, Ltd.
Related Concept Videos
 01:12
Relative Risk
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast,...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:52
Regression Toward the Mean
 00:57
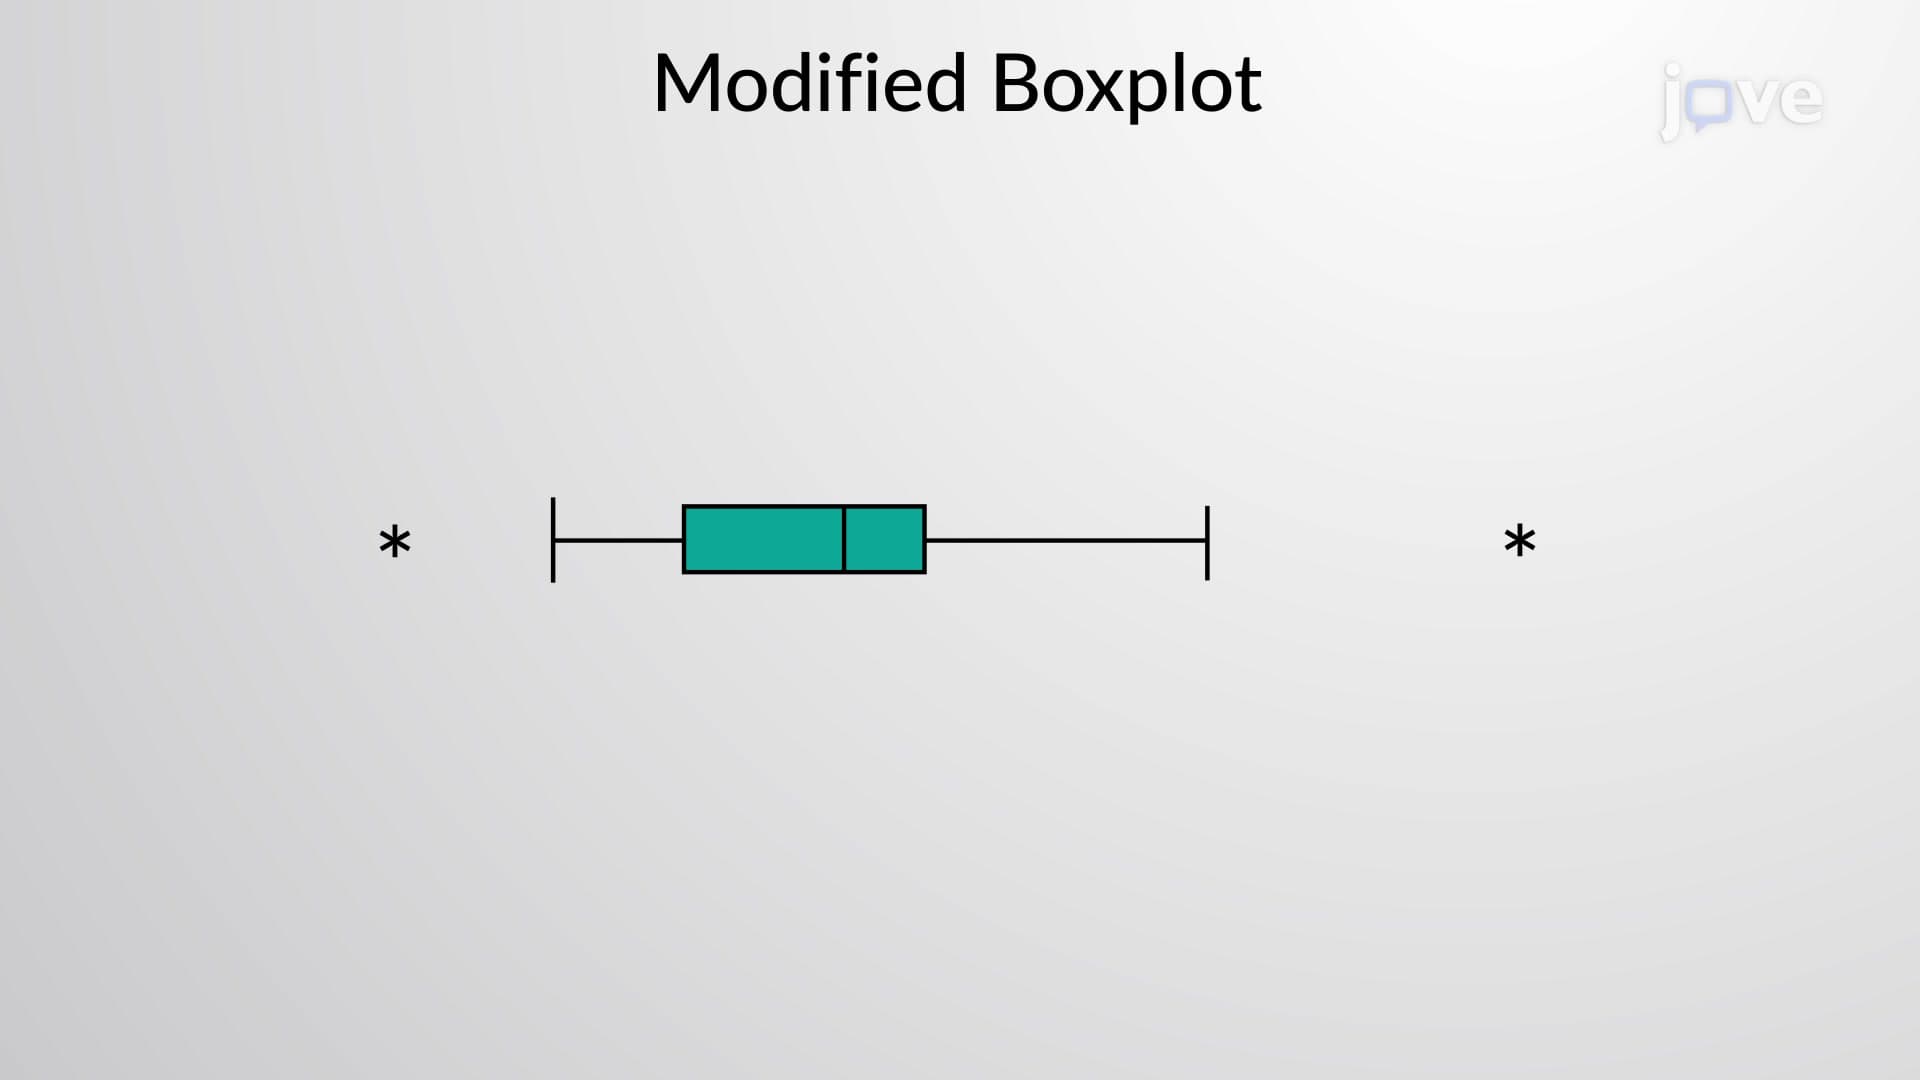
Modified Boxplots
However, the box plot does not tell the reader about outliers - values that lie far from the center of the data. We can modify the standard box and whisker plot to identify the outliers and visualize the actual spread of the data in a sample.
Initially, we calculate the adjusted...
 01:15
Quartile
1; 1; 2; 2; 4; 6; 6.8; 7.2; 8; 8.3; 9; 10; 10; 11.5
The median or second quartile is seven. The lower half of the...