Related Experiment Video
Updated: Dec 6, 2025

Measurement of the Directional Information Flow in fNIRS-Hyperscanning Data using the Partial Wavelet Transform Coherence Method
Published on: September 3, 2021
Stock market comovements among Asian emerging economies: A wavelet-based approach
Ijaz Younis1, Cheng Longsheng1, Muhammad Farhan Basheer2
1School of Economics and Management, Nanjing University of Science and Technology, Nanjing, PR China.

Abstract:
Stock market, is one of the most important financial market which has a close relationship with a country's economy, due to which it is often called the barometer of the economy. Over the past 25 years, the stock markets have been affected by different global economic shocks. Various researchers have analyzed different aspects of these effects one by one, however, this study is an assessment of stock market interrelationship of emeriging Asian economies which include most of the East Asian, and Southeast Asian emerging economies with special focus on China for past decades during which different crisis occurred. We used Morgan Stanley capital international (MSCI) daily indices data for each stock market and compared Chinese stock market with the stock markets of India, Pakistan, Malaysia, Singapore, and Indonesia. We analyzed the data through the individual wavelet power spectrum, cross-wavelet transform and wavelet coherence, to determine the correlation and volatility among the selected stock markets. These model have the power to analyze co-movements among these countries with respect to both frequency and time spaces. Our findings show that there are co-movement patterns of higher frequencies during the crises periods of 1997, 2008 and 2015. The dependency strength among the considered economies is noted to increase in the crisis periods, which implies increased short- and long-term benefits for the investors. From a financial point of view, it has been determined that the co-movement strength among the emerging economies of Asia may have an effect on the VaR (Value at Risk) levels of a multi-country portfolio. Furthermore, the stock market of China shows a high correlation with the other six Asian stock emerging markets in both high and low-frequency spectrums. The association of the south and east Asian stock market with Chinese stock markets show the interconnection of these economies with the economy of China since past two decades. These findings are useful for investors, portfolio managers and the policymaker around the globe.
Related Concept Videos
 01:26
Equity Theory
 01:29
Econometric Views (EViews)
 01:07
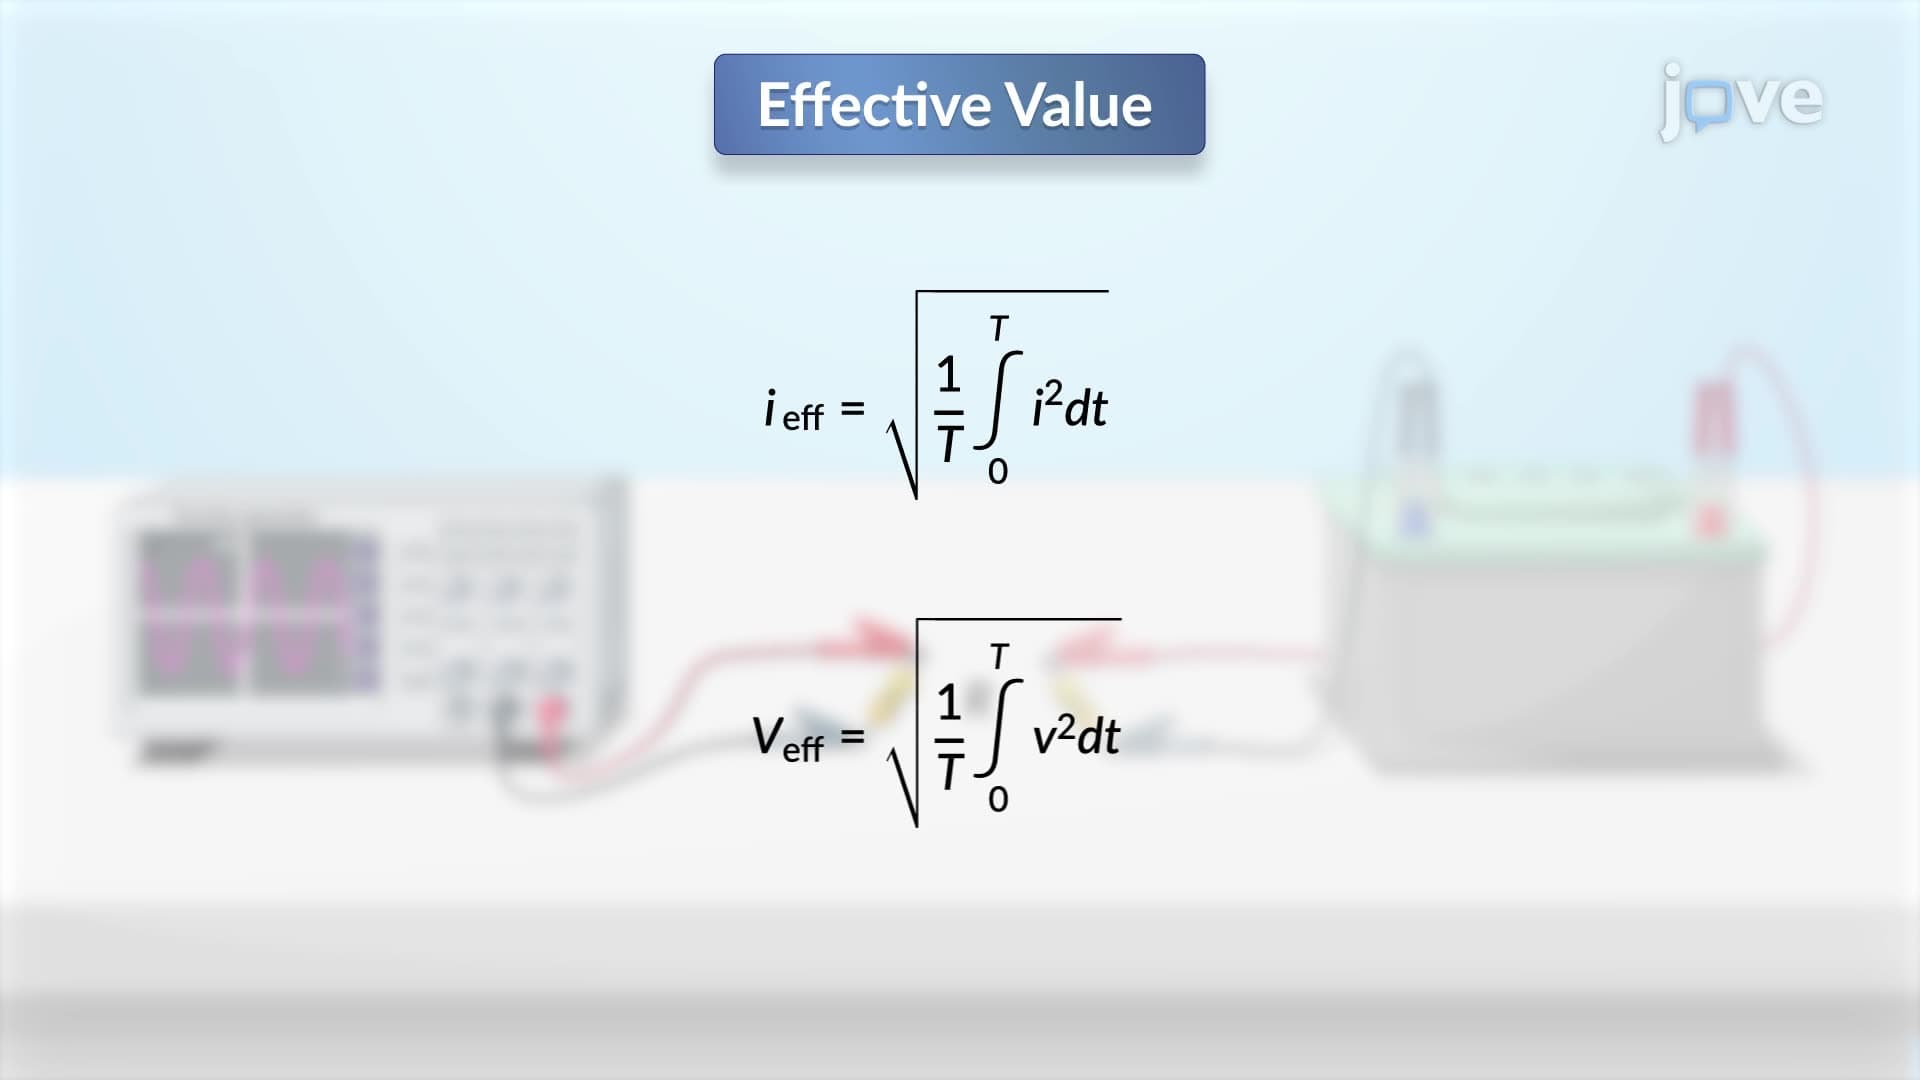
Effective Value of a Periodic Waveform
The effective value of a periodic current represents the direct current (DC) that conveys the same average power to a resistor as the periodic current itself. This concept is crucial when assessing AC circuits. To determine the...
 01:10
Central Tendency: Analysis
The mean is one such measure, calculated by totaling all values in a dataset and dividing by the number of values. For instance, the mean blood pressure reading (120, 130, 140, 150) would be 135. However, the mean can be affected by extreme values or outliers.
The median, another measure,...
 01:12
Quantitative Analysis
In quantitative analysis, two key measurements are made: the sample quantity and a property proportional to the amount of the analyte (the substance being analyzed). This forms the basis of the...
 01:09
Harmonic Mean
Take the example of the speed of a car, which is the measure of the rate of distance traveled. If the vehicle traverses the same distance back-and-forth, its average speed equals the total distance traveled divided by the total time taken. However, if the car moves with varying speeds, then the arithmetic mean is more skewed...