Related Experiment Video
Updated: Nov 10, 2025


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Robust Estimation for Bivariate Poisson INGARCH Models
Byungsoo Kim1, Sangyeol Lee2, Dongwon Kim2
1Department of Statistics, Yeungnam University, Gyeongsan 38541, Korea.

Abstract:
In the integer-valued generalized autoregressive conditional heteroscedastic (INGARCH) models, parameter estimation is conventionally based on the conditional maximum likelihood estimator (CMLE). However, because the CMLE is sensitive to outliers, we consider a robust estimation method for bivariate Poisson INGARCH models while using the minimum density power divergence estimator. We demonstrate the proposed estimator is consistent and asymptotically normal under certain regularity conditions. Monte Carlo simulations are conducted to evaluate the performance of the estimator in the presence of outliers. Finally, a real data analysis using monthly count series of crimes in New South Wales and an artificial data example are provided as an illustration.
Related Concept Videos
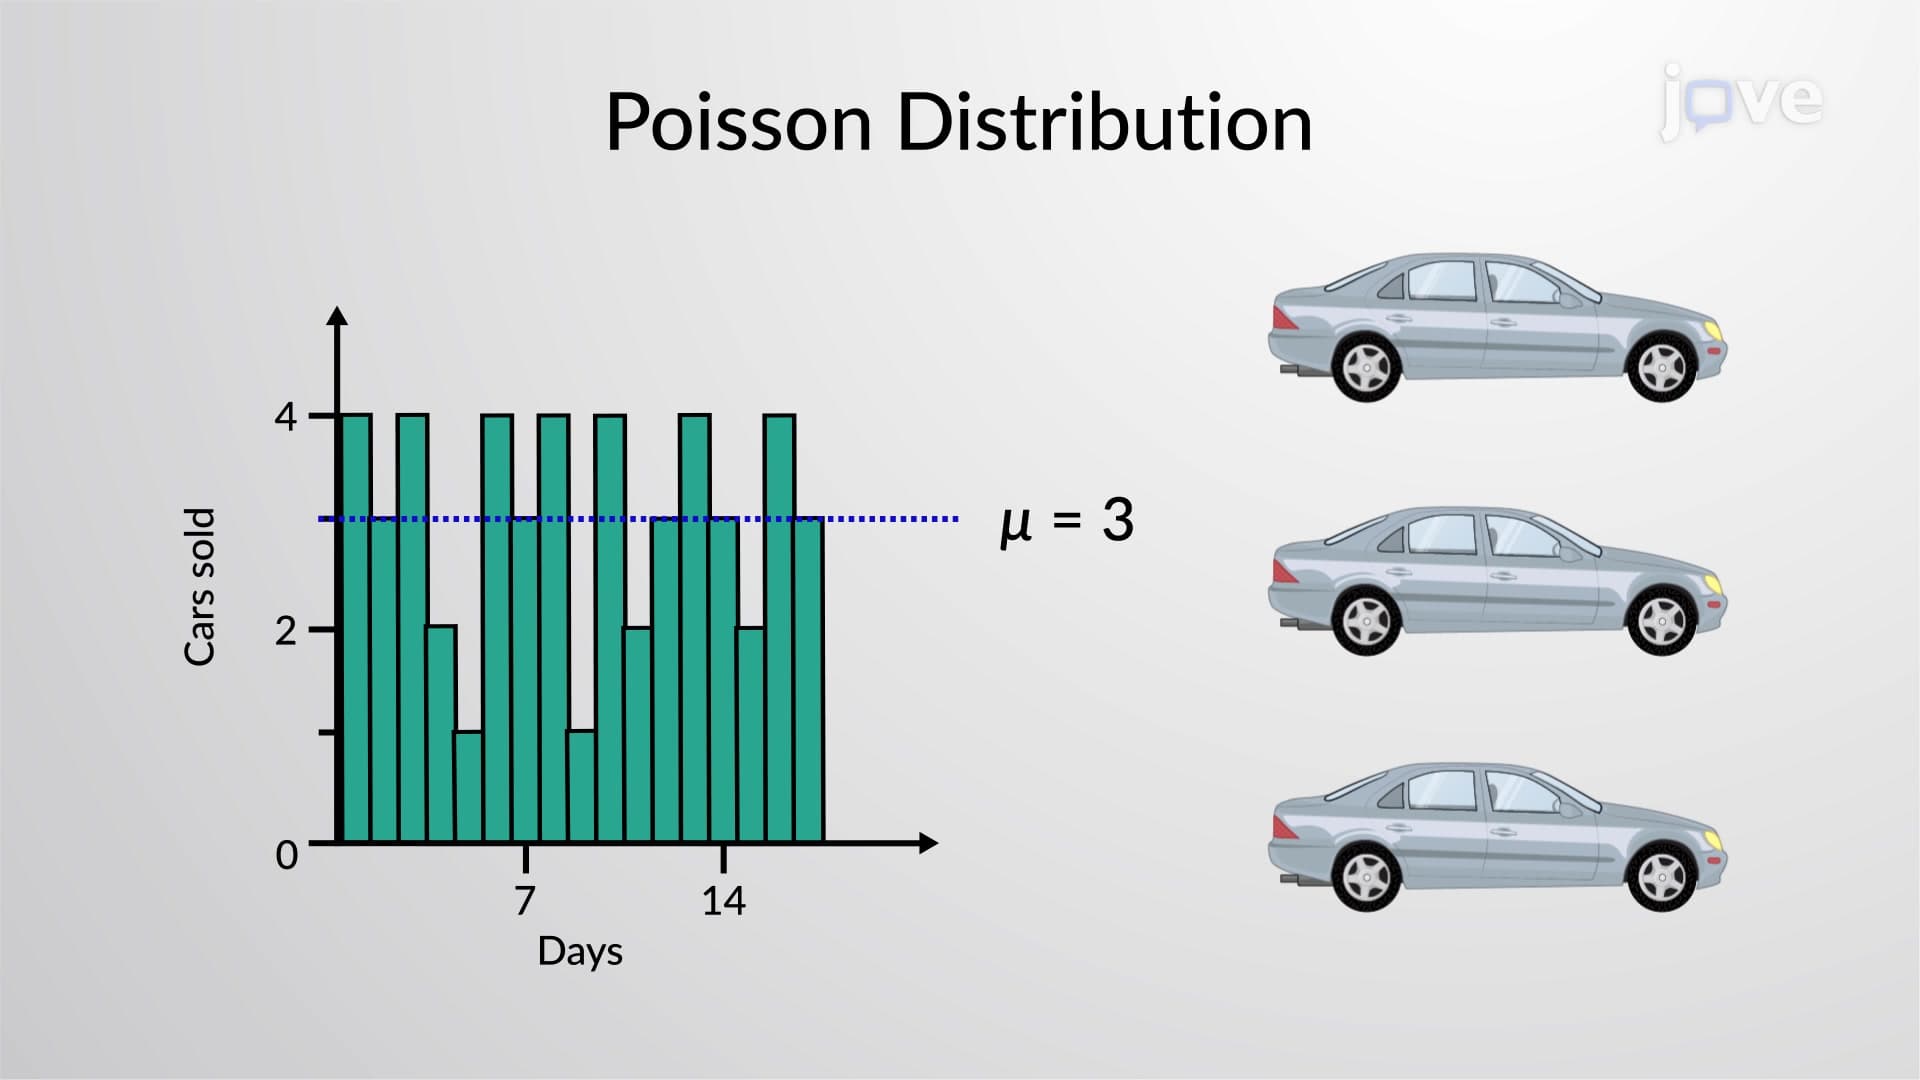 01:09
Poisson Probability Distribution
The...
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 01:26
Distributions to Estimate Population Parameter
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:22
Estimating Population Mean with Unknown Standard Deviation
William S. Gosset (1876–1937) of the...
 01:26
Estimating Population Standard Deviation