Related Experiment Video
Updated: Oct 13, 2025

Applications of EEG Neuroimaging Data: Event-related Potentials, Spectral Power, and Multiscale Entropy
Published on: June 27, 2013
Asymmetric dependence of intraday frequency components in the Brazilian stock market
Marcela de Marillac Carvalho1, Luiz Otávio de Oliveira Pala1, Gabriel Rodrigo Gomes Pessanha2
1Department of Statistics, Federal University of Lavras, Lavras, Brazil.

Abstract:
The multivariate dependence plays an important role in financial instrument management. Due to the inherent characteristics in the financial market, such as heavy tails in the returns unconditional distribution and asymmetry between gain and loss, we obtained the asymmetric dependence structure in different short-term variation scales based on the wavelet technique MODWT. The study sought to capture the relations between financial returns represented by its frequency components. Intraday returns series was used in the 15-min sampling interval from stocks and applied the D-Vine pair-copula to decompose in trade frequencies of 15 min, 1 h, 1 day, and 1 week with margin adjustments of ARIMA-APARCH class and BB7 copula function, responsible for measuring the dependence on tails. The results indicated the prevalence of a high dependence during market upturns, rising over the analyzed frequencies. Being an important tool in financial management and allowing short-term strategies of diversification.
More Related Videos
Related Concept Videos
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 00:55
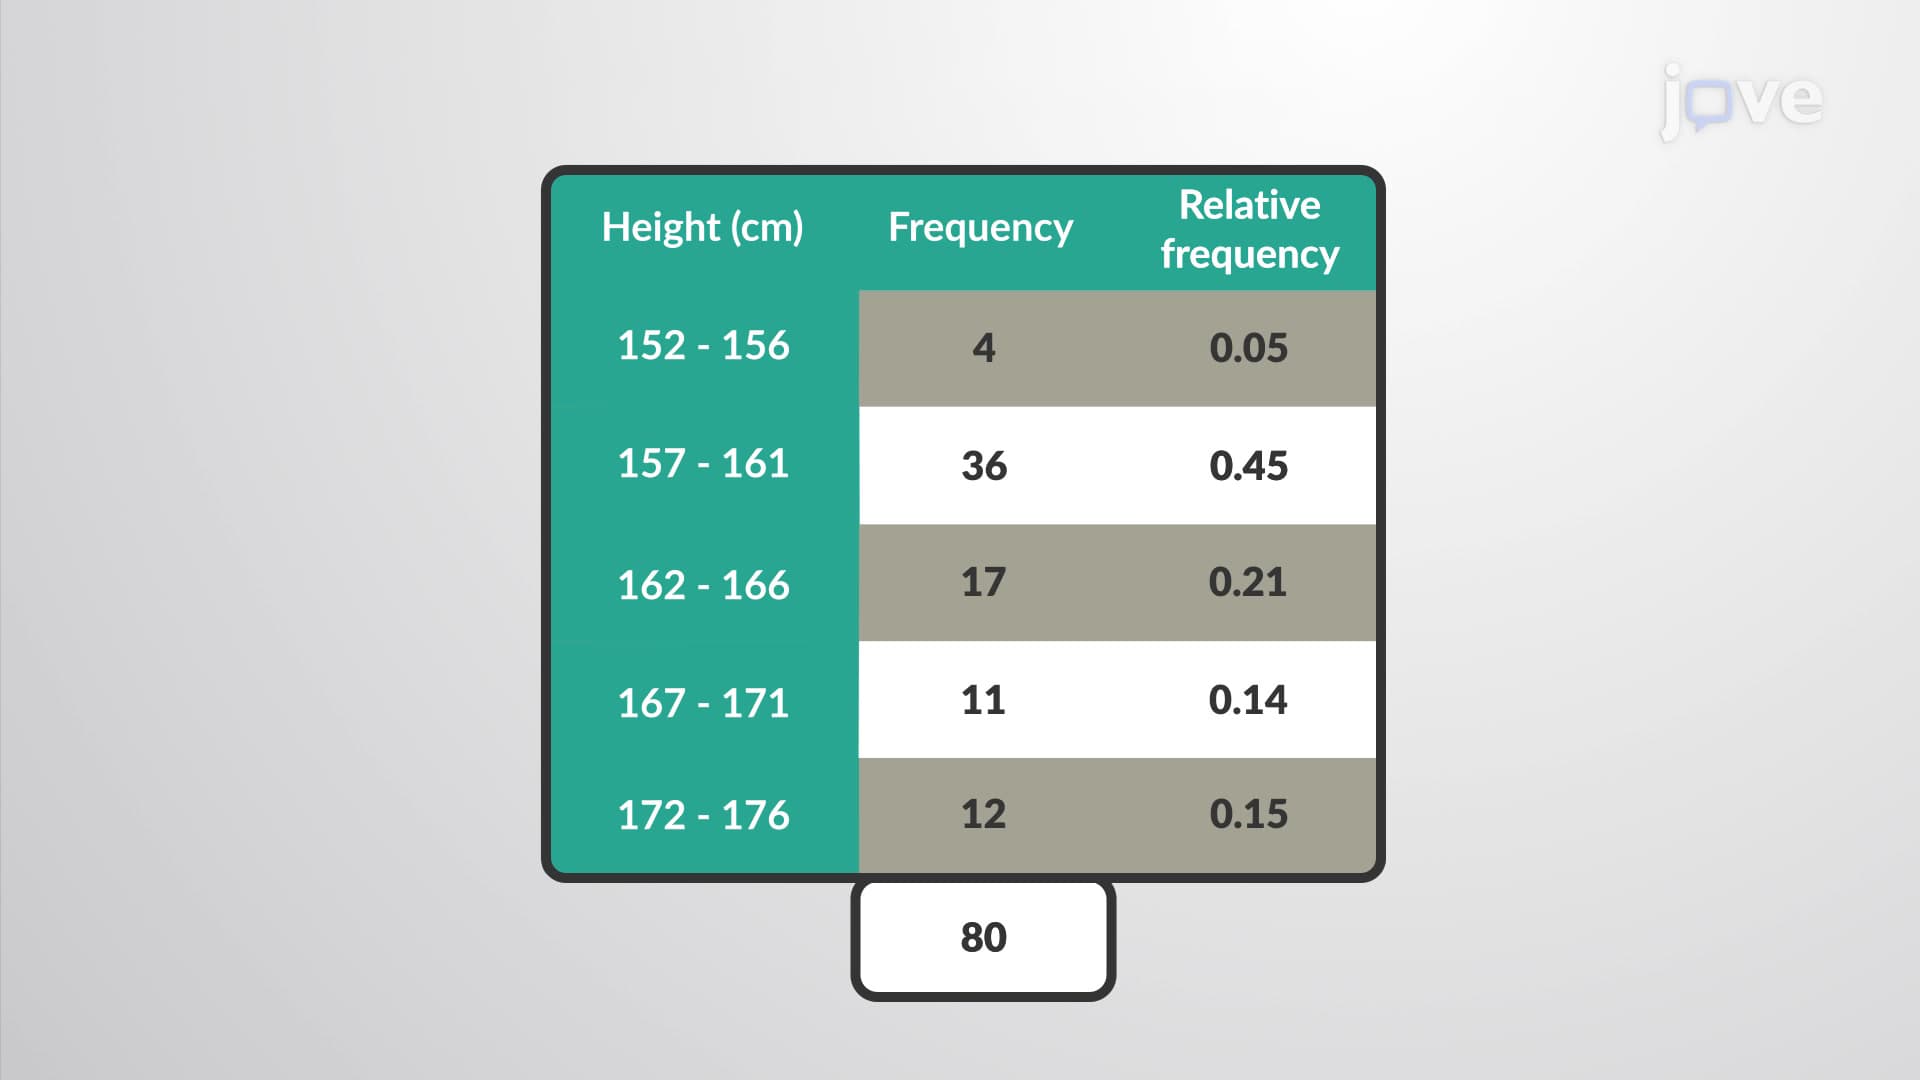
Relative Frequency Distribution
 01:08
Determination of Expected Frequency
 01:08
IR Spectrum Peak Splitting: Symmetric vs Asymmetric Vibrations
 01:14
Relative Frequency Histogram
 01:21
Frequency-dependent Selection