Related Experiment Video
Updated: Oct 10, 2025
Author Spotlight: Advancements in Multiplex Detection of Respiratory Viruses
Published on: November 10, 2023
COVID-19 impact on commodity futures volatilities
1School of Business and Research Academy of Belt & Road, Ningbo University, China.

Abstract:
COVID-19 pandemic has affected almost all aspects of the global economy, especially commodity futures markets, due to the disruption risk of global supply chains from the pandemic lockdown. This paper extends ARMA-GARCH models to investigate the pandemic impact on both long-run and short-term volatilities of four major commodity futures. Model-fitting results reveal that the pandemic event has enhanced long-run volatilities for all futures returns, while the daily COVID-19 infection speed has mixed effects on short-term (instantaneous) volatilities. Our extended models and research findings are useful in global supply chain risk management, commodity options trading and regulators' supervision of inflation risk.
More Related Videos
Related Concept Videos
 01:10
Volatilization
 01:11
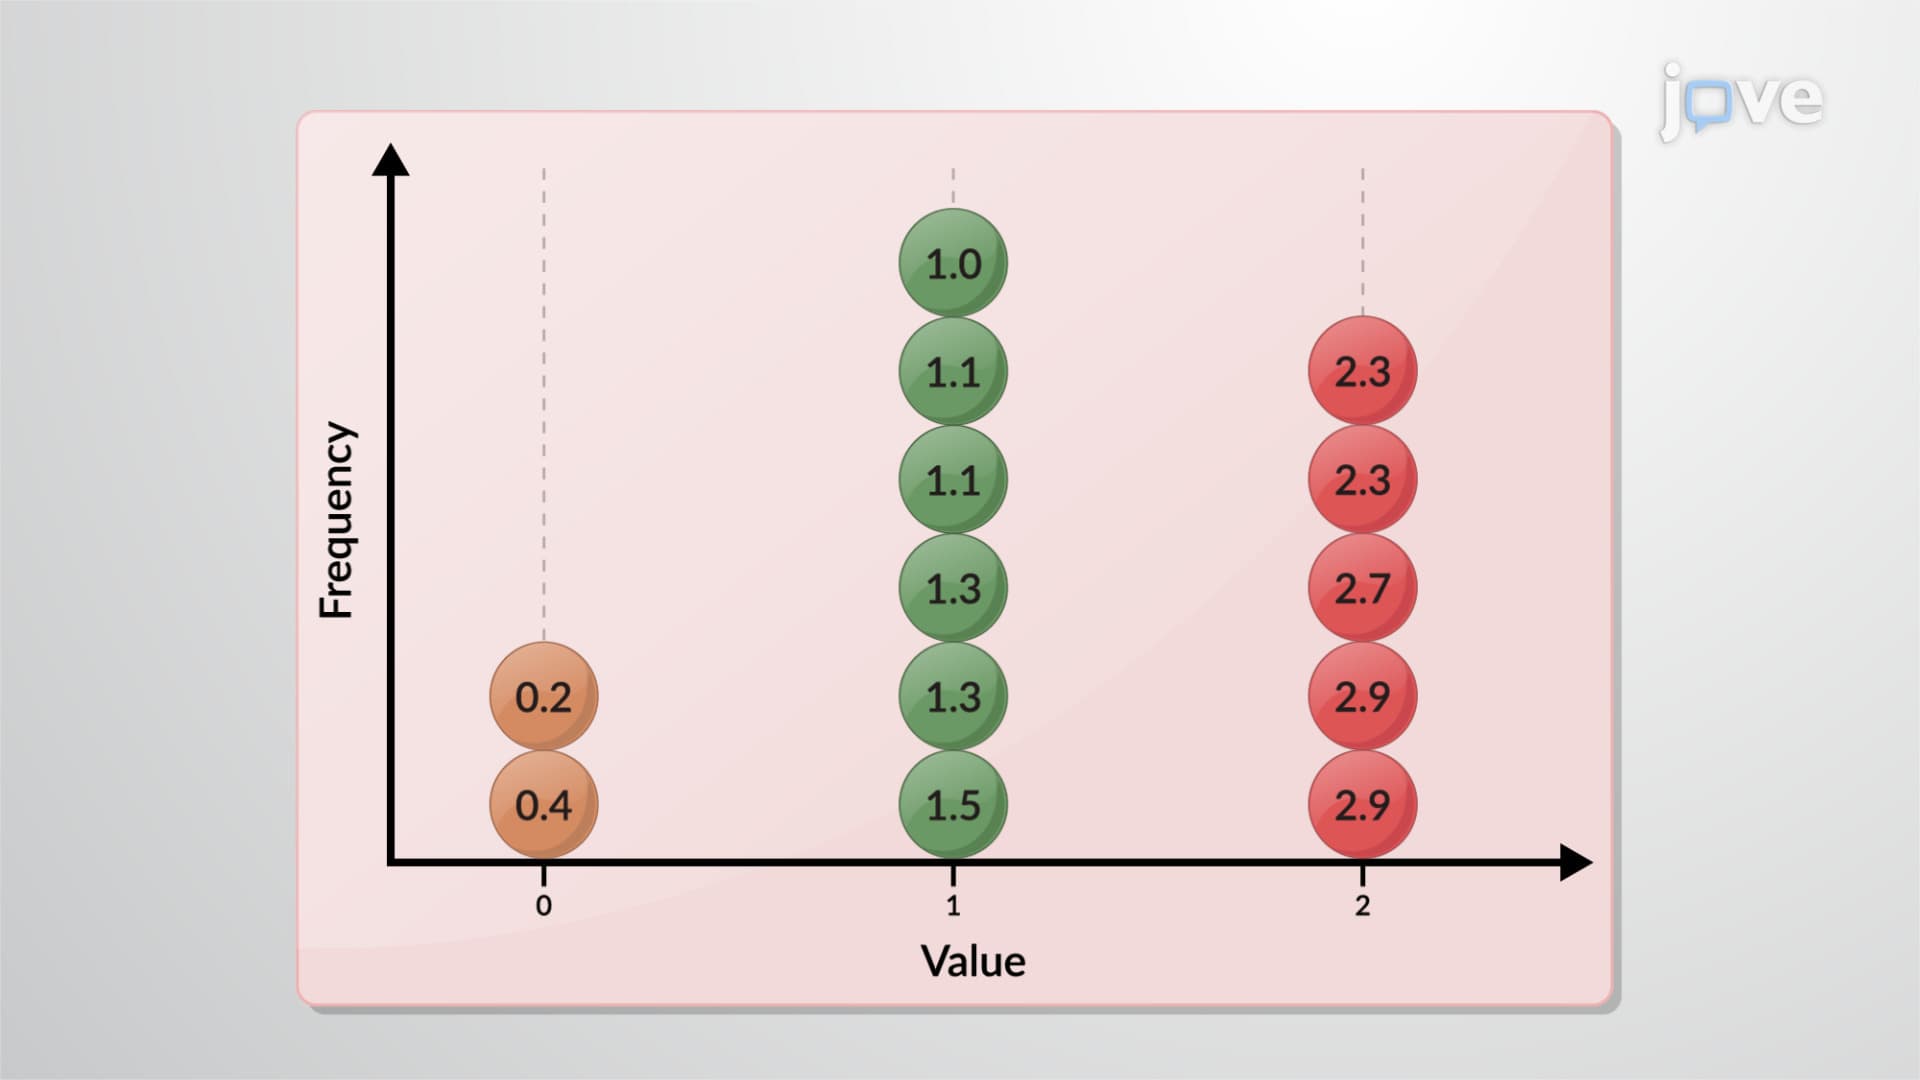
Variability: Analysis
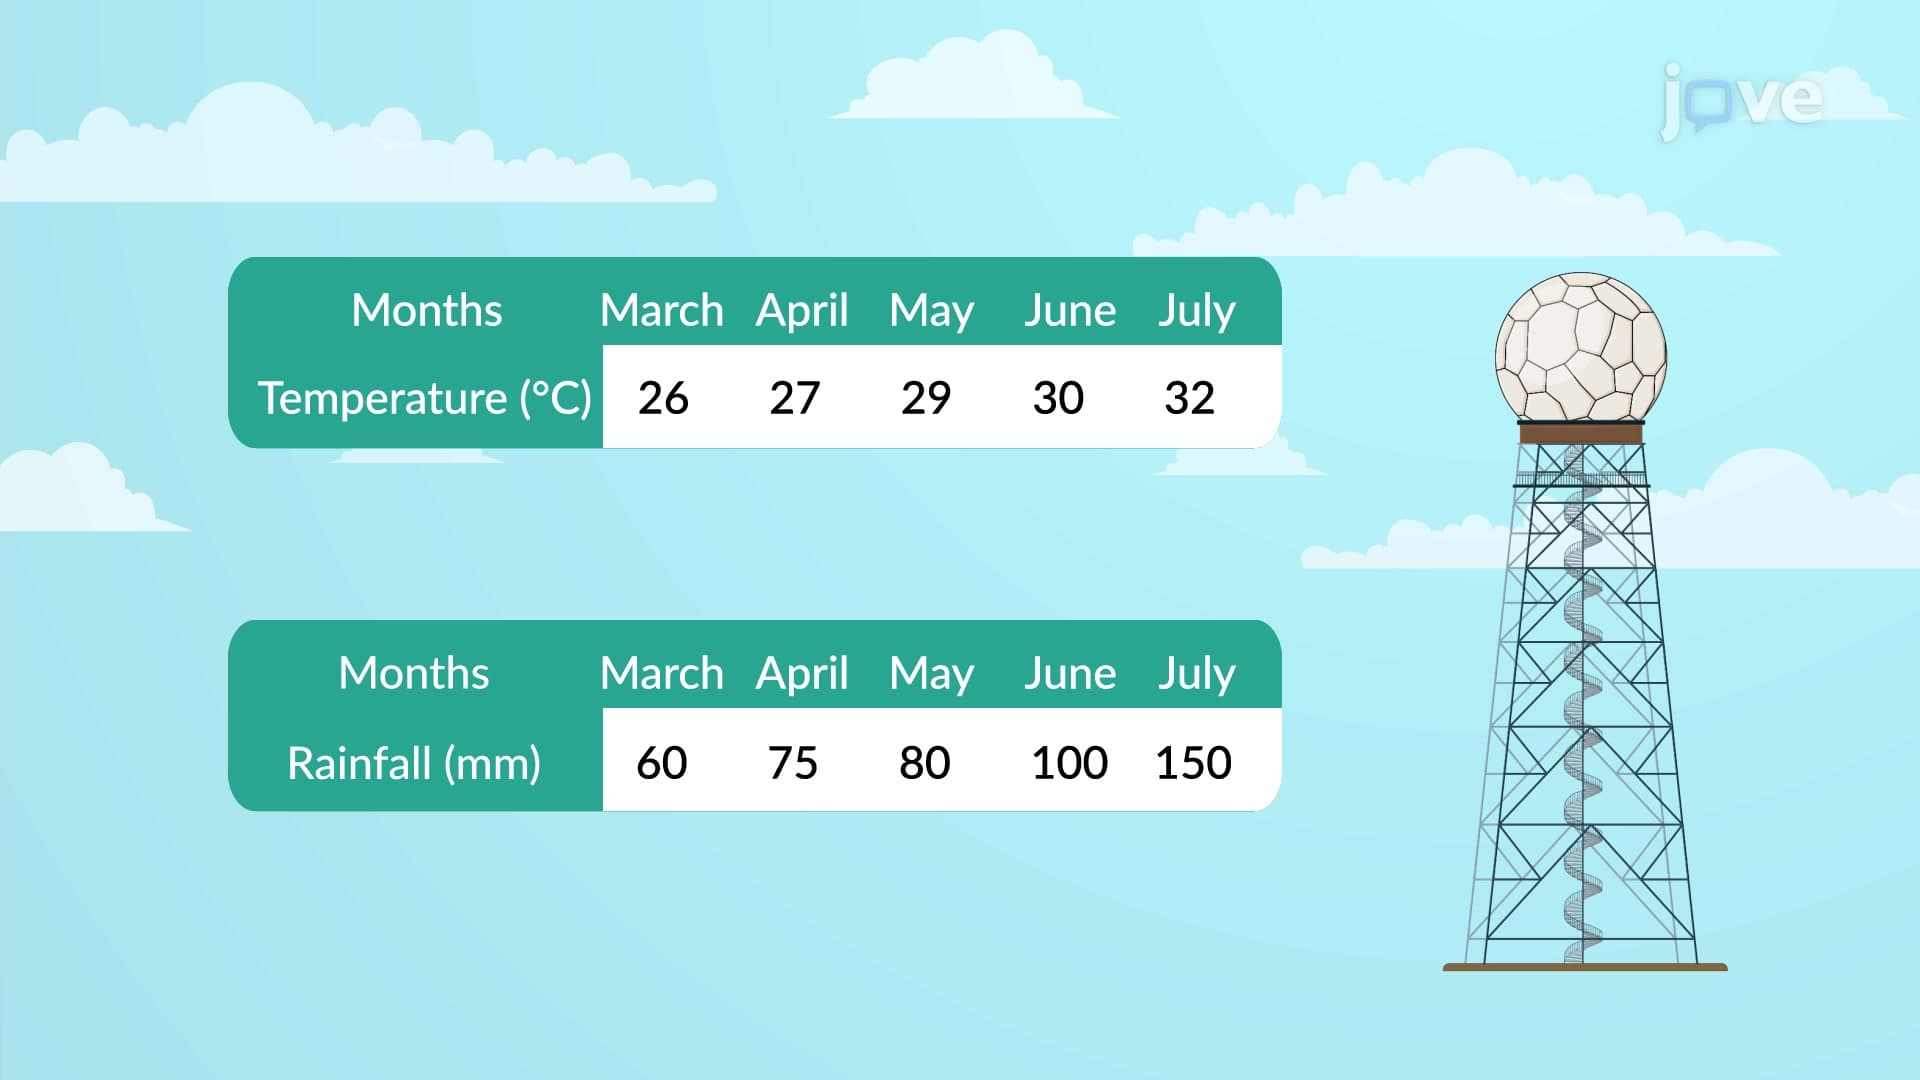
The range is a simple measure of variability, indicating the difference between the highest and...
 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 00:59
Uncertainty: Overview
 01:15
Chebyshev's Theorem to Interpret Standard Deviation
 01:26
Factors Affecting the Risk of Infection
The integrity and count of the white blood cells help the body resist pathogens and fight infection. When impaired, it reduces the body's resistance to pathogens. The acidic pH levels of the gastrointestinal, genitourinary tracts, and skin...