Related Experiment Video
Updated: Sep 8, 2025
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Forecasting interest rate volatility of the United Kingdom: evidence from over 150 years of data
Hossein Hassani1, Mohammad Reza Yeganegi2, Juncal Cuñado3
1Research institute for energy management and planning (RIEMP), University of Tehran, Tehran, Iran.

Abstract:
This study examines the very short, short, medium and long-term forecasting ability of different univariate GARCH models of United Kingdom (UK)'s interest rate volatility, using a long span monthly data from May 1836 to June 2018. The main results show the relevance of considering alternative error distributions to the normal distribution when estimating GARCH-type models. Thus, we obtain that the Asymmetric Power ARCH (A-PARCH) models with skew generalized error distribution are the most accurate models when forecasting UK interest rates, while for the short, medium and long-term term forecasting horizons, GARCH models with generalized error distribution for the error term are the most accurate models in forecasting UK's interest rates.
Related Concept Videos
 01:04
Random Error
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 01:15
Scatter Plot
 01:19
Variation
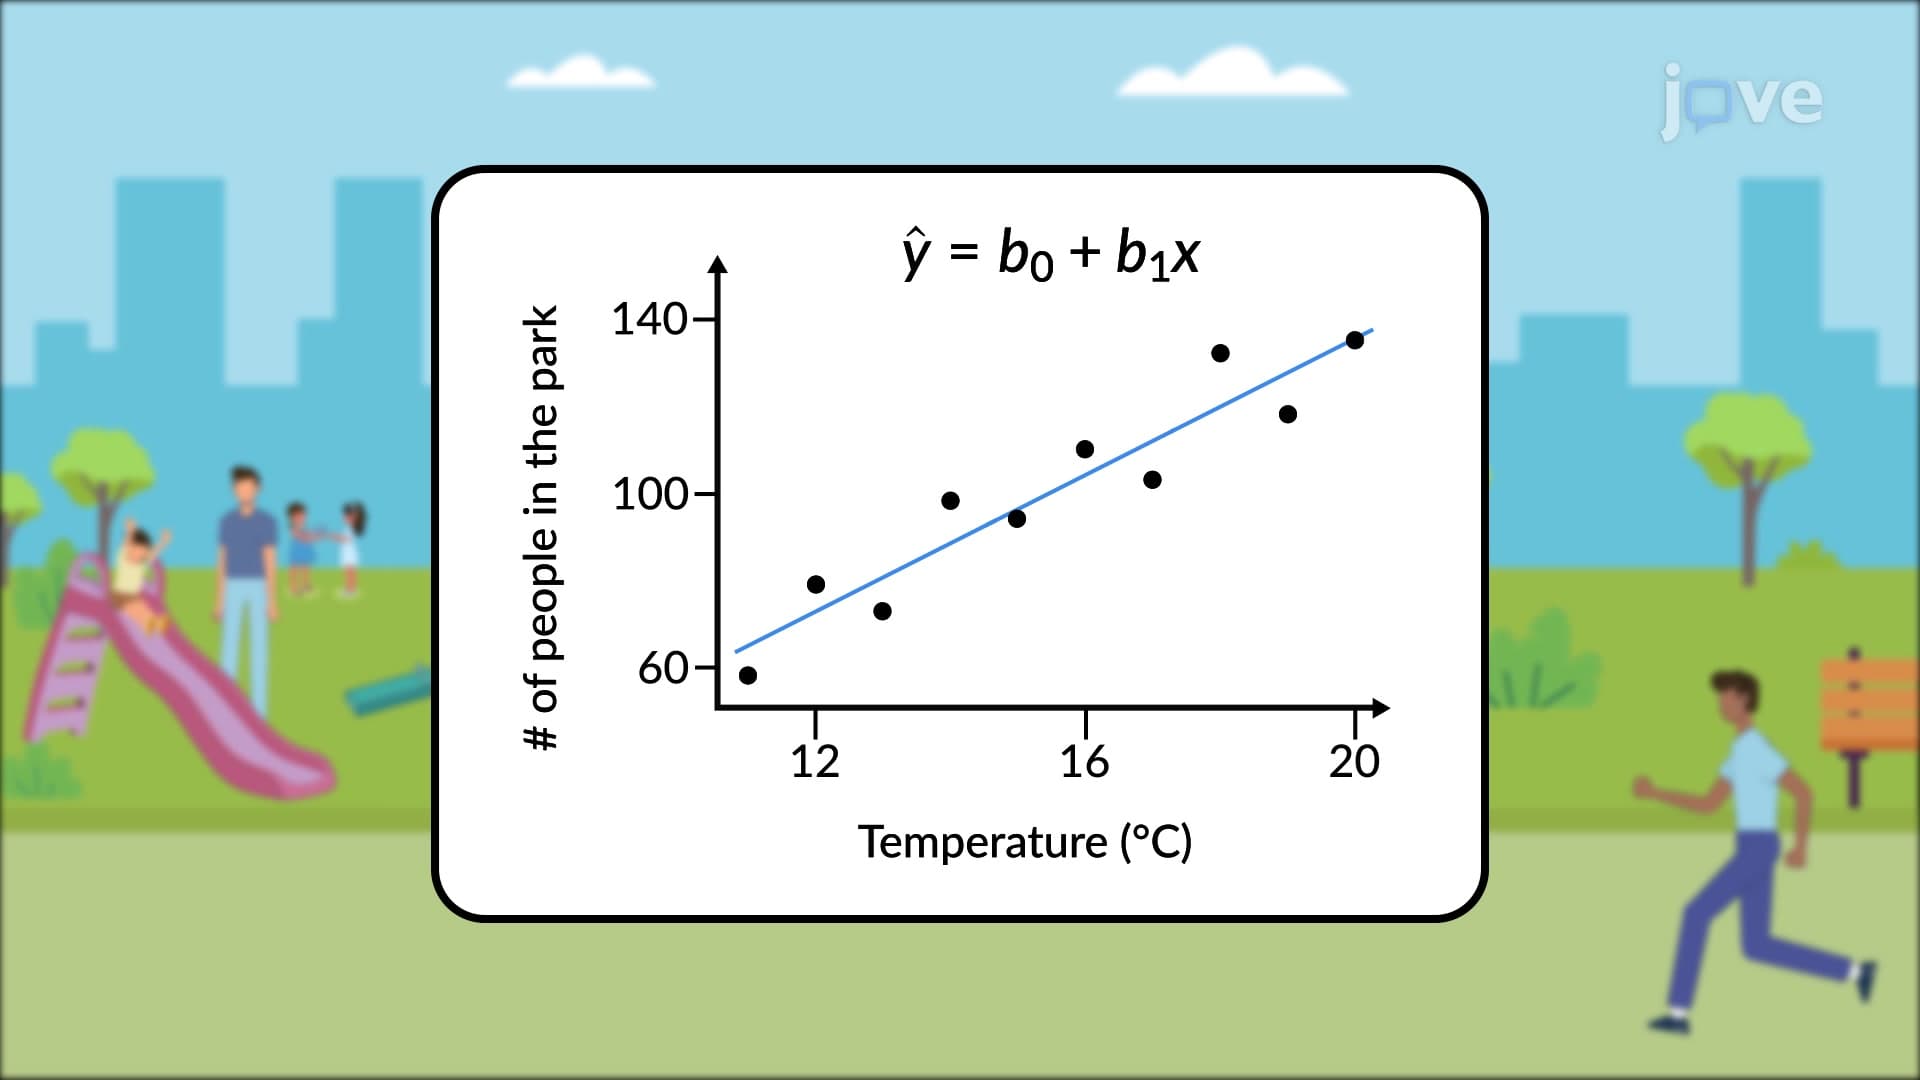
When independent and dependent variables are plotted on a scatter plot, the slope of a line is a value that describes the rate of change between the two...
 01:11
Hazard Rate