Related Experiment Video
Updated: Aug 25, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Economic events and the volatility of government bill rates
1School of Finance, Southwestern University of Finance and Economics, Chengdu, Sichuan, China.

Abstract:
Many studies show that in many countries (especially the G7), volatility in government bill rates far exceeds that in consumption growth rates. This volatility puzzle cannot be predicted by traditional disaster models, in which rare economic disasters are defined as a peak-to-trough percent fall in consumption (or real per capita GDP) by a high threshold (≥10%). For this purpose, we extend the traditional definition of rare economic disasters and propose a novel asset pricing model that models both good and bad events. We define a bad (or good) event as a peak-to-trough absolute decline (or a trough-to-peak absolute rise) in consumption growth rates by a low threshold (<10%). Compared to traditional disaster models, our model contains three improvements. First, model good and bad events, not just bad ones (e.g., rare economic disasters). Second, the event's impact lasts for multiple periods rather than one period. Third, model non-rare economic events. We calibrate the parameters in our model to match the moments from U.S. asset return data. Simulation results indicate that the model can successfully predict the volatility of U.S. government bill rates higher than that of U.S. consumption growth rates.

Related Concept Videos
 01:15
Scatter Plot
 01:09
Correlation
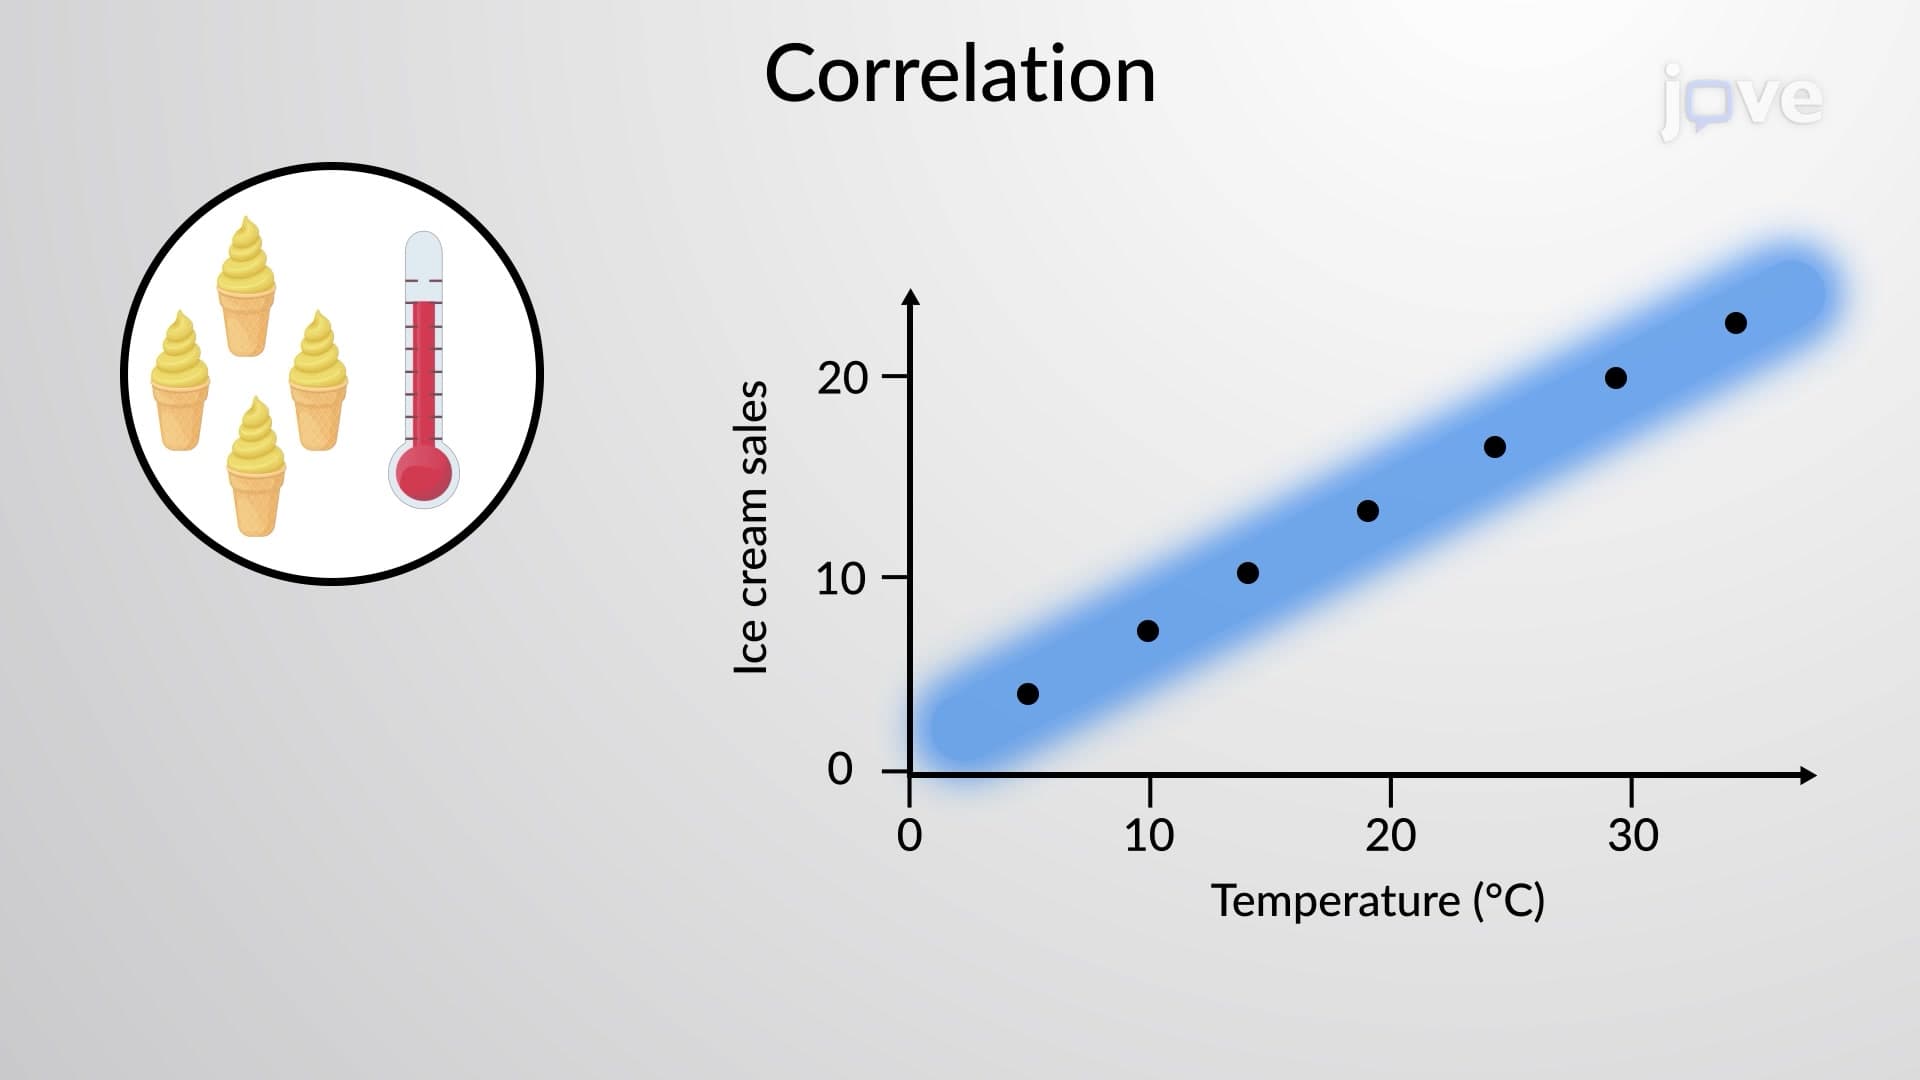
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 01:11
Hazard Rate
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:52
Regression Toward the Mean
 02:39
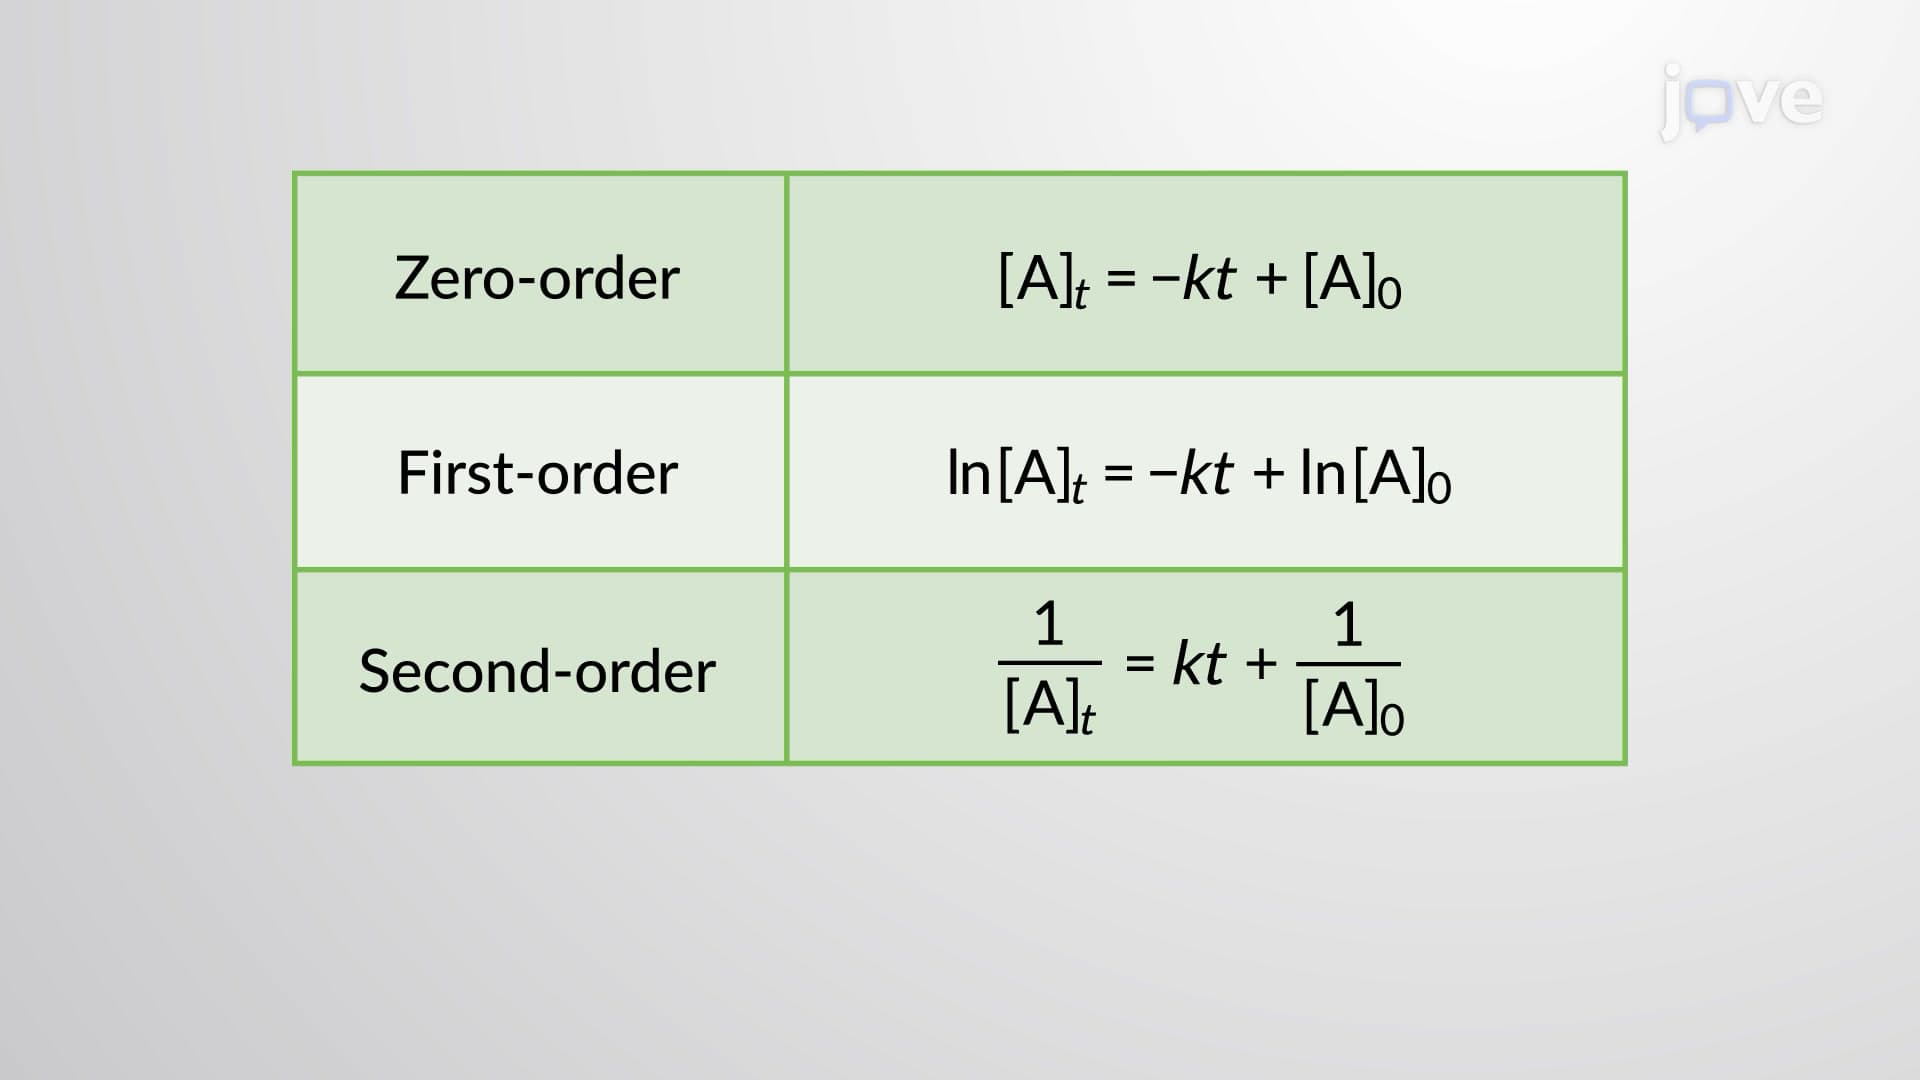
The Integrated Rate Law: The Dependence of Concentration on Time