Related Experiment Video
Updated: Jun 30, 2025

Probing Structural and Dynamic Properties of Trafficking Subcellular Nanostructures by Spatiotemporal Fluctuation Spectroscopy
Published on: August 16, 2021
Evolution of temporal fluctuation scaling exponent in nonstationary time series using supersymmetric theory of
1Universidad Nacional de Colombia, Departamento de Física, Bogotá D.C. 111321, Colombia.

Abstract:
Temporal fluctuation scaling (TFS) is an emergent property of complex systems that relates the variance (Ξ_{2}) and the mean (M_{1}) from an empirical data set in the form Ξ_{2}∼M_{1}^{α_{TFS}}, where the dispersion (fluctuation) of the data has been described in terms of Ξ_{2}. At present, it has been shown that this law of complex systems has different multidisciplinary applications such as characterizing the market rate based on its exponent, explaining the spatial spread of a pandemic or measuring dispersion in a counting process, among others, if it is known how the average value M_{1} of a representative quantity in a system changes. Then, using the path integral formalism and Parisi-Sourlas method, we propose an extension of path integral formalism to understand the origin of the temporal fluctuation scaling and the evolution of its exponent over time in nonstationary time series. To this end, we first show how the probability of transition between two states of a stochastic variable x(t) can be expressed once it is known its cumulant generating function. Also, we introduce a nonlinear term in a cumulant generating function of the form H^{(n)}(p,t;γ)∼p^{n} to obtain a model where the nth moment of the probability distribution evolves arbitrarily. Subsequently, in order to reproduce the temporal fluctuation scaling, a linear combination of H^{(n)}(p,t;γ) with n∈{1,2} is used. Therefore this allows describing how the mean M_{1}(t) and the variance Ξ_{2}(t) of empirical time series evolve. Thence, an analytical expression is deduced for the evolution of the temporal evolution of the temporal fluctuation scaling exponent α_{TFS}(t). Likewise, the validity of the expression found for α_{TFS}(t) is verified with a toy model based on white noise. Finally, this approach is verified in two stock indices (Dow Jones and Sao Paulo stock index) and two currencies (GBP-USD and EUR-USD) with daily data. It is found that this approach accurately captures the evolution of the mean and variance of these four financial derivatives after contrasting the results with a coefficient of determination that depends on H^{(n)}(p,t;γ). Also, it is shown that the temporal fluctuation scaling exponent is a measure of uncertainty or volatility in financial time series.
Related Concept Videos
 01:21
Properties of Fourier series II
A function f(t) is...
 01:24
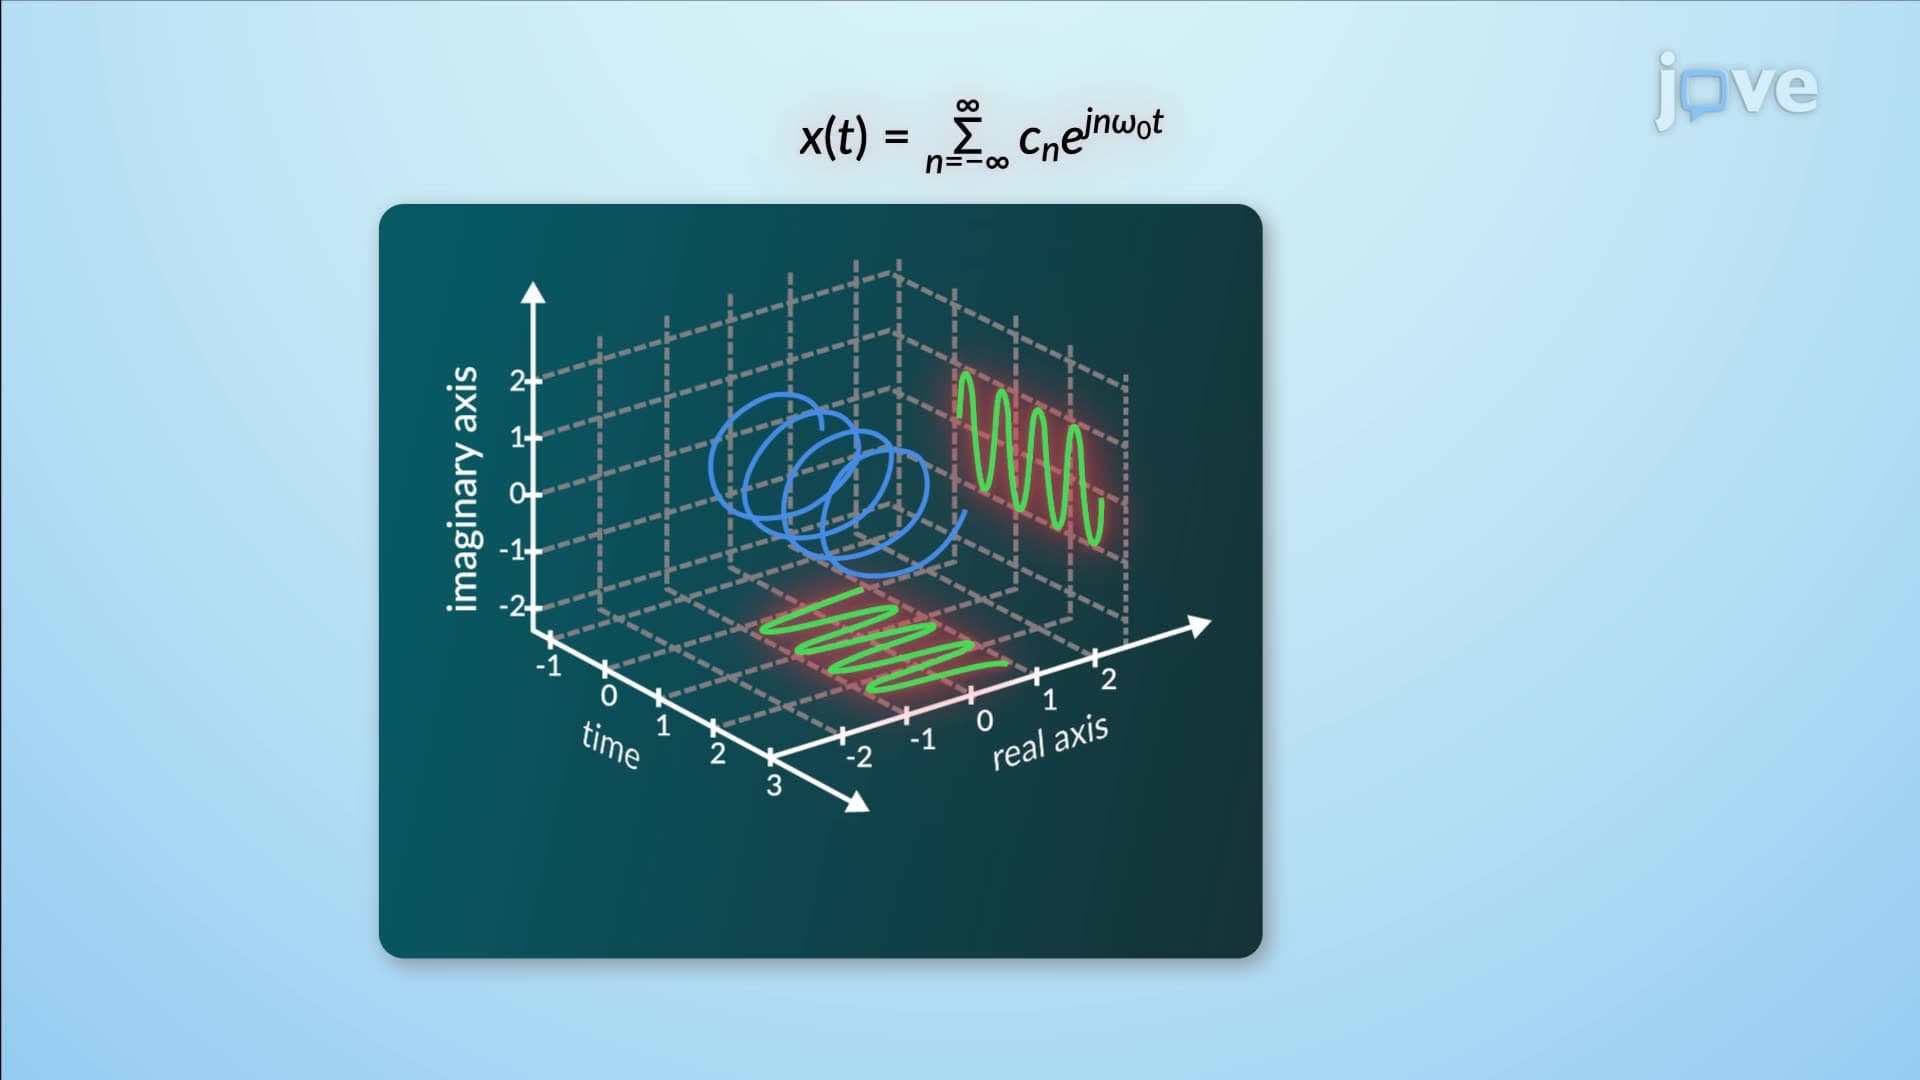
Exponential Fourier series
Euler's identity...
 01:18
Exponential and Sinusoidal Signals
 01:20
Discrete-Time Fourier Series
For a discrete-time periodic signal x[n]...
 01:21
The Swing Equation
In a steady-state operation, the mechanical torque (Τm) supplied to the generator is balanced by the electrical torque...
 01:16
Basic Discrete Time Signals
The unit impulse or sample sequence is mathematically expressed as zero for all n values except at n=0, where it is one. The unit impulse sequence, denoted by δ(n), is the first difference of the unit step sequence, while the unit step sequence u(n) is...