Related Experiment Video
Updated: Jun 28, 2025

A Rapid Method for Modeling a Variable Cycle Engine
Published on: August 13, 2019
A Gamma Ornstein-Uhlenbeck model driven by a Hawkes process
Guillaume Bernis1, Riccardo Brignone2, Simone Scotti3
1Natixis Assurances, Paris, France.

Abstract:
We propose an extension of the -OU Barndorff-Nielsen and Shephard model taking into account jump clustering phenomena. We assume that the intensity process of the Hawkes driver coincides, up to a constant, with the variance process. By applying the theory of continuous-state branching processes with immigration, we prove existence and uniqueness of strong solutions of the SDE governing the asset price dynamics. We propose a measure change of self-exciting Esscher type in order to describe the relation between the risk-neutral and the historical dynamics, showing that the -OU Hawkes framework is stable under this probability change. By exploiting the affine features of the model we provide an explicit form for the Laplace transform of the asset log-return, for its quadratic variation and for the ergodic distribution of the variance process. We show that the proposed model exhibits a larger flexibility in comparison with the -OU model, in spite of the same number of parameters required. We calibrate the model on market vanilla option prices via characteristic function inversion techniques, we study the price sensitivities and propose an exact simulation scheme. The main financial achievement is that implied volatility of options written on VIX is upward shaped due to the self-exciting property of Hawkes processes, in contrast with the usual downward slope exhibited by the -OU Barndorff-Nielsen and Shephard model.
More Related Videos
Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:19
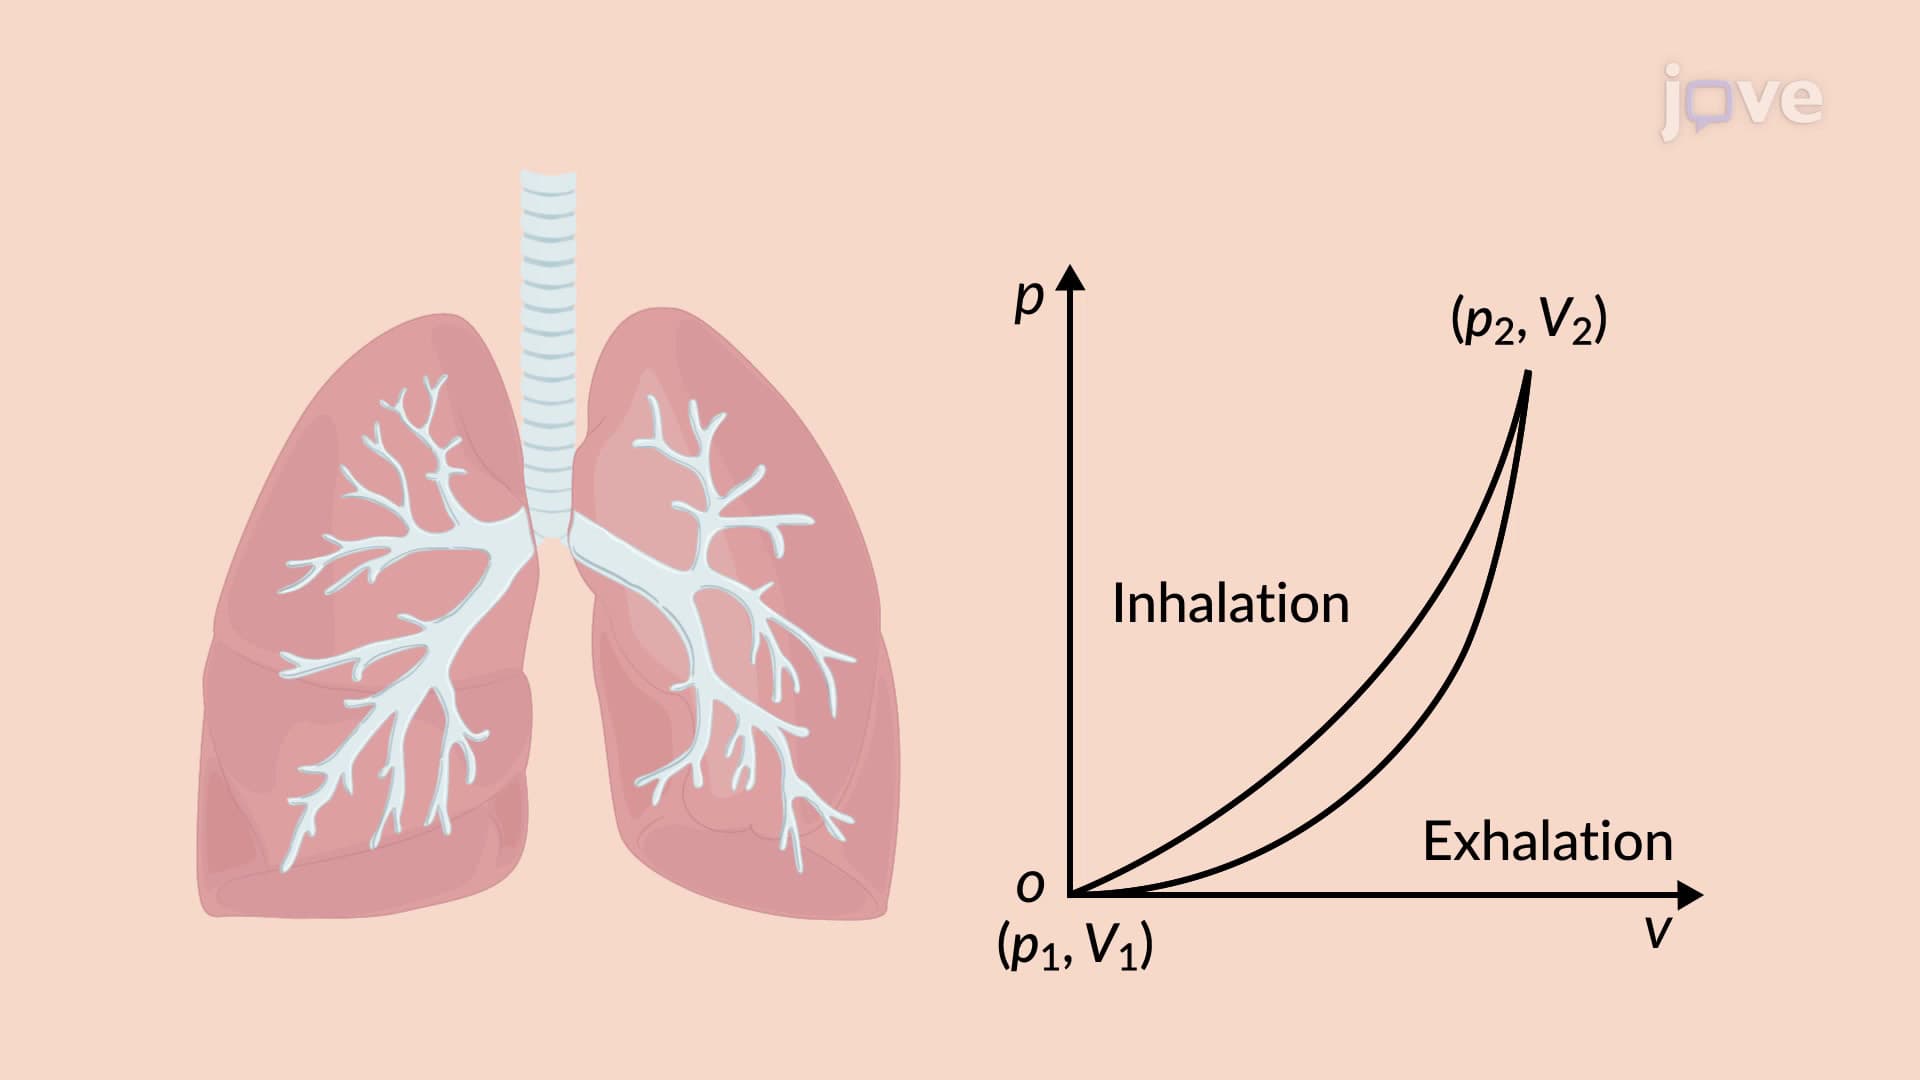
Cyclic Processes And Isolated Systems
In the case of a non-isolated system, the change in the internal energy is zero only if the process is cyclic. A thermodynamic process is considered cyclic if the system undergoes a series of changes and returns to its initial state.
Consider a cyclic process that returns to its initial state, undergoing a four-step process. The heat transfer along each...
 01:34
Woodward–Hoffmann Selection Rules and Microscopic Reversibility
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:10
Entropy Change in Reversible Processes
The statement can be further generalized to prove that entropy is a state function. Take a cyclic process between any two points on a p-V diagram.
 02:45
The Quantum-Mechanical Model of an Atom