Related Experiment Video
Updated: Jun 25, 2025


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Heteroscedasticity effects as component to future stock market predictions using RNN-based models
Aida Nabilah Sadon1, Shuhaida Ismail1, Azme Khamis1
1Universiti Tun Hussein Onn Malaysia, Johor, Malaysia.

Abstract:
Heteroscedasticity effects are useful for forecasting future stock return volatility. Stock volatility forecasting provides business insight into the stock market, making it valuable information for investors and traders. Predicting stock volatility is a crucial task and challenging. This study proposes a hybrid model that predicts future stock volatility values by considering the heteroscedasticity element of the stock price. The proposed model is a combination of Generalized Autoregressive Conditional Heteroskedasticity (GARCH) and a well-known Recurrent Neural Network (RNN) algorithm Long Short-Term Memory (LSTM). This proposed model is referred to as GARCH-LSTM model. The proposed model is expected to improve prediction accuracy by considering heteroscedasticity elements. First, the GARCH model is employed to estimate the model parameters. After that, the ARCH effect test is used to test the residuals obtained from the model. Any untrained heteroscedasticity element must be found using this step. The hypothesis of the ARCH test yielded a p-value less than 0.05 indicating there is valuable information remaining in the residual, known as heteroscedasticity element. Next, the dataset with heteroscedasticity is then modelled using an LSTM-based RNN algorithm. Experimental results revealed that hybrid GARCH-LSTM had the lowest MAE (7.961), RMSE (10.466), MAPE (0.516) and HMAE (0.005) values compared with a single LSTM. The accuracy of forecasting was also significantly improved by 15% and 13% with hybrid GARCH-LSTM in comparison to single LSTMs. Furthermore, the results reveal that hybrid GARCH-LSTM fully exploits the heteroscedasticity element, which is not captured by the GARCH model estimation, outperforming GARCH models on their own. This finding from this study confirmed that hybrid GARCH-LSTM models are effective forecasting tools for predicting stock price movements. In addition, the proposed model can assist investors in making informed decisions regarding stock prices since it is capable of closely predicting and imitating the observed pattern and trend of KLSE stock prices.
More Related Videos
 10:46
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
 13:04
Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Related Concept Videos
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:11
Regression Analysis
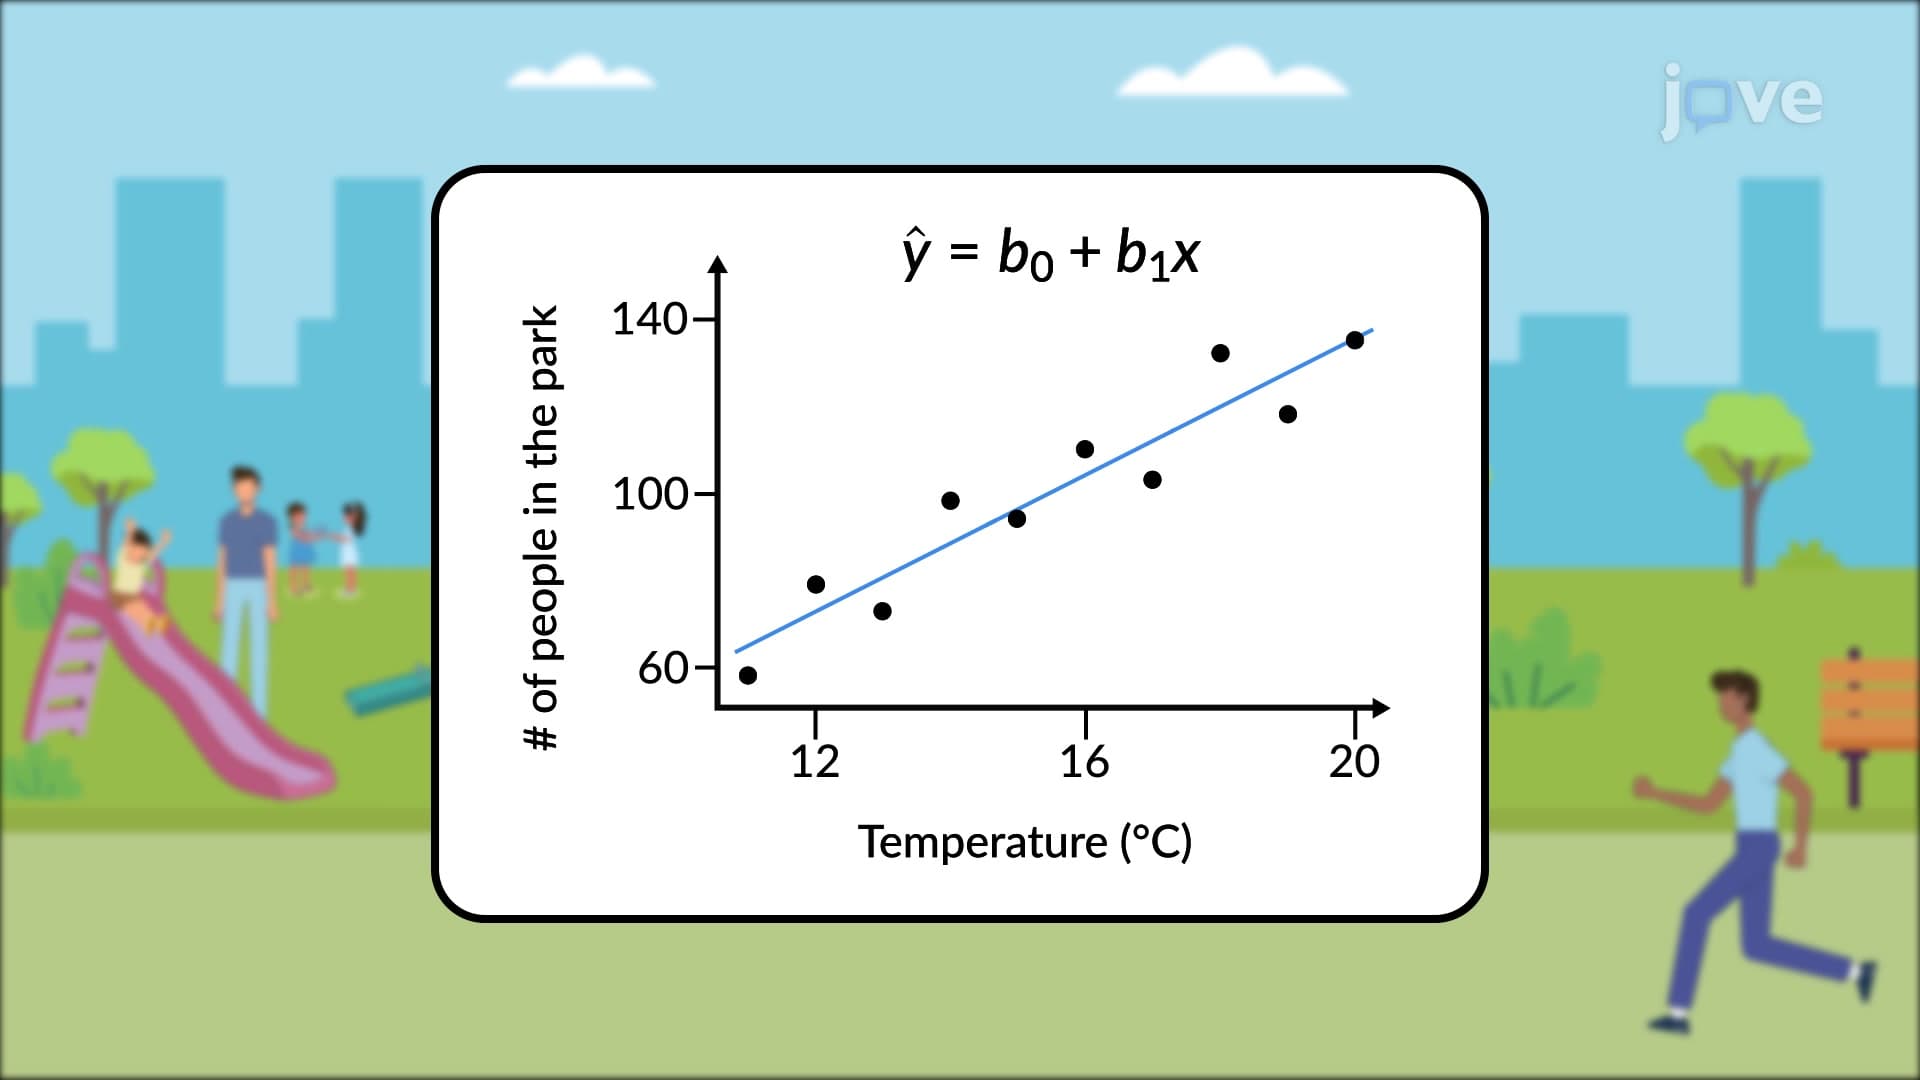
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as:
 01:25
Multiple Regression
Farmers can use multiple regression to determine the crop yield based on more than one factor, such as water availability, fertilizer, soil properties, etc. Here, the crop yield is the response or dependent variable as it depends on the other independent variables. The analysis requires the construction of a scatter plot...
 01:52
Regression Toward the Mean
 01:19
Variation
When independent and dependent variables are plotted on a scatter plot, the slope of a line is a value that describes the rate of change between the two...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...