Related Experiment Video
Updated: Jun 13, 2025
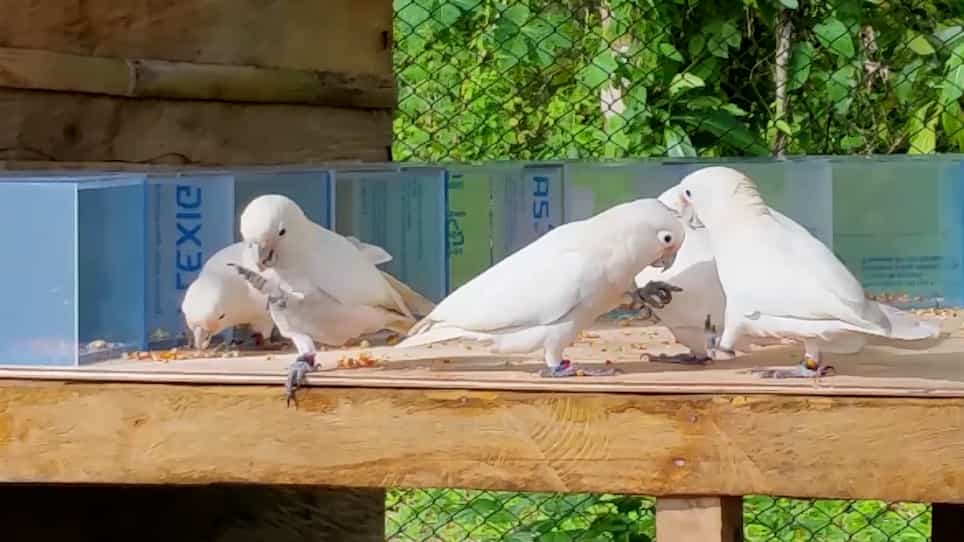

The Innovation Arena: A Method for Comparing Innovative Problem-Solving Across Groups
Published on: May 13, 2022
The impact of accounting conservatism on enterprise innovation investment
1Faculty of Accounting, Wuxi Taihu University, 214000, China.

Abstract:
This study investigates the influence of accounting conservatism on corporate innovation investment through the lens of information asymmetry theory. While existing literature acknowledges the importance of accounting conservatism in corporate decision-making, there remains a gap in understanding how it specifically affects innovation investment, particularly in varied market environments and regulatory contexts. Specifically, current research often overlooks the heterogeneity of the impact of accounting conservatism on innovation investment under different market environments and regulatory frameworks. Additionally, there is a lack of specialized studies on the unique group of Chinese listed companies. This study fills this gap by empirically analyzing data from Chinese A-share listed companies, revealing a negative correlation between accounting conservatism and corporate innovation investment. Through empirical analysis of the financial reports and research and development (R&D) investment data of Chinese A-share listed companies from 2015 to 2022, this study finds a significant negative correlation between accounting conservatism and corporate innovation investment. Specifically, as accounting conservatism increases, corporate investment in R&D shows a decreasing trend, with a correlation coefficient of -0.364. This result is further validated by hierarchical regression analysis, where the regression coefficient is -0.465, indicating that accounting conservatism has a significant inhibitory effect on corporate innovation investment. This study is pioneering in its examination of the relationship between accounting conservatism and corporate innovation investment within the unique market environment of China, taking into account its distinctive characteristics and rapidly evolving technological industry background. To quantify accounting conservatism, the research employs the C-Score and G-Score models, while employing a range of indicators to measure corporate innovation investment, including proportions of R&D expenditure, number of new products or services, patent applications, total R&D personnel, capital investments, and progress in innovation projects. This comprehensive evaluation method enhances the accuracy and reliability of the study. The contribution of this study is significant as it offers a fresh perspective on how accounting conservatism influences corporate innovation investment. By providing empirical data support, it assists investors and corporate managers in making informed financial decisions and shaping innovation strategies. Through hierarchical regression analysis, the study substantiates the detrimental impact of accounting conservatism on corporate innovation investment, thereby establishing new theoretical and practical foundations for further research and application in related fields.
More Related Videos
Related Concept Videos
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:01
Production Efficiency
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast,...
 01:12
Hindsight Biases
 01:25
Creative Thinking
Divergent thinking is the...
 01:14
Decision Making: Traditional Method
First, a specific claim about the population parameter is decided based on the research question and is stated in a simple form. Further, an opposing statement to this claim is also stated. These statements can act as null and alternative hypotheses, out of which a null hypothesis would be a...