Related Experiment Video
Updated: Jun 1, 2025


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Cross-section without factors: a string model for expected returns
Walter Distaso1, Antonio Mele2, Grigory Vilkov3
1Imperial College, South Kensington Campus, London SW7 2AZ, United Kingdom.

Abstract:
Many asset pricing models assume that expected returns are driven by common factors. We formulate a model where returns are driven by a string, and no-arbitrage restricts each expected return to capture the asset's granular exposure to all other asset returns: a correlation premium. The model predicts fresh properties for big stocks, which display higher connectivity in bad times, but also work as correlation hedges: they contribute to a negative fraction of the correlation premium, and portfolios that are more exposed to them command a lower premium. The string model performs at least as well as many existing linear factor models.

Related Concept Videos
 01:15
Expected Value
 01:19
Expected Frequencies in Goodness-of-Fit Tests
 01:19
Variation
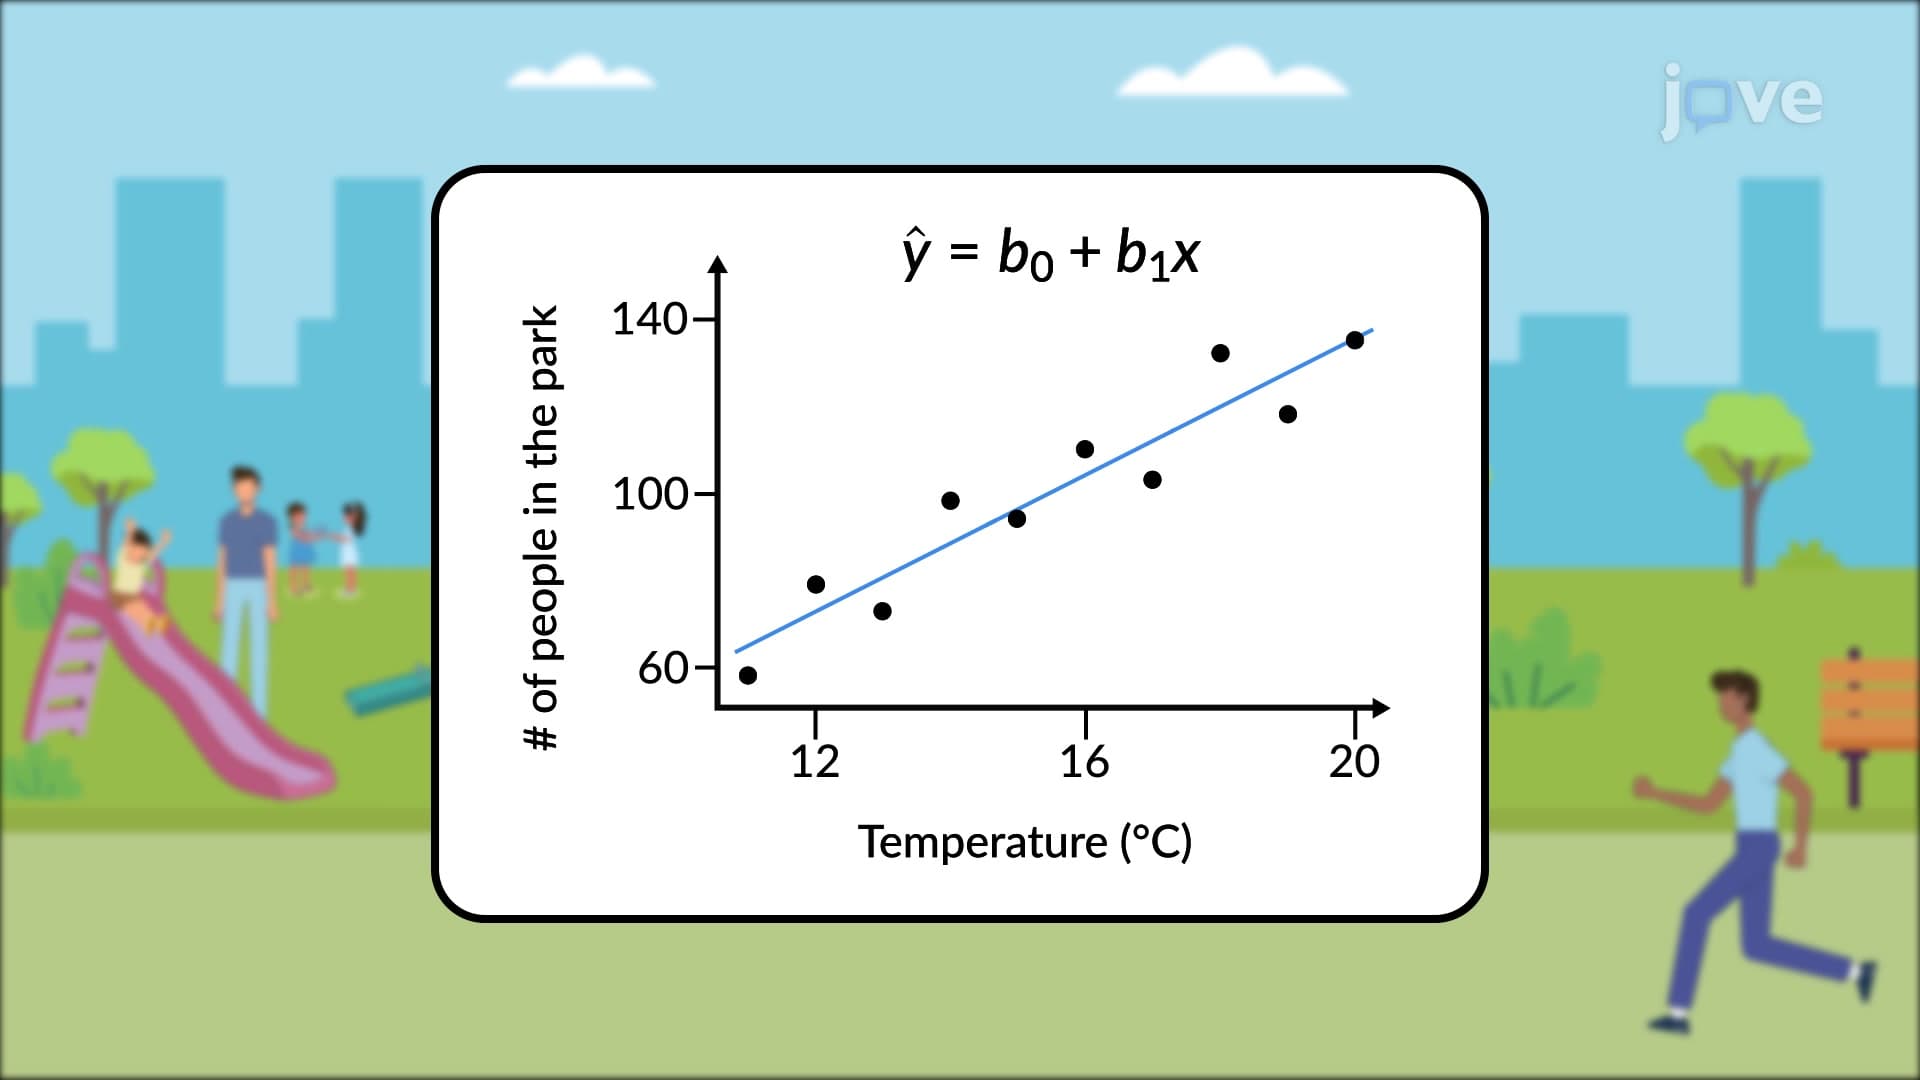
When independent and dependent variables are plotted on a scatter plot, the slope of a line is a value that describes the rate of change between the two...
 01:29
Econometric Views (EViews)
 01:23
Mechanistic Models: Compartment Models in Individual and Population Analysis
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as: