Related Experiment Video
Updated: Jun 10, 2025

Author Spotlight: Efficient Image Recognition Using Directional Gradient Histogram Technique and Support Vector Machines
Published on: January 5, 2024
DeepVol: volatility forecasting from high-frequency data with dilated causal convolutions
Fernando Moreno-Pino1,2, Stefan Zohren1,3
1Oxford-Man Institute of Quantitative Finance, University of Oxford, Oxford, UK.

Abstract:
Volatility forecasts play a central role among equity risk measures. Besides traditional statistical models, modern forecasting techniques based on machine learning can be employed when treating volatility as a univariate, daily time-series. Moreover, econometric studies have shown that increasing the number of daily observations with high-frequency intraday data helps to improve volatility predictions. In this work, we propose DeepVol, a model based on Dilated Causal Convolutions that uses high-frequency data to forecast day-ahead volatility. Our empirical findings demonstrate that dilated convolutional filters are highly effective at extracting relevant information from intraday financial time-series, proving that this architecture can effectively leverage predictive information present in high-frequency data that would otherwise be lost if realised measures were precomputed. Simultaneously, dilated convolutional filters trained with intraday high-frequency data help us avoid the limitations of models that use daily data, such as model misspecification or manually designed handcrafted features, whose devise involves optimising the trade-off between accuracy and computational efficiency and makes models prone to lack of adaptation into changing circumstances. In our analysis, we use two years of intraday data from NASDAQ-100 to evaluate the performance of DeepVol. Our empirical results suggest that the proposed deep learning-based approach effectively learns global features from high-frequency data, resulting in more accurate predictions compared to traditional methodologies and producing more accurate risk measures.
More Related Videos
Related Concept Videos
 01:24
Convolution: Math, Graphics, and Discrete Signals
To simplify the convolution integral, it is assumed that both the input signal and impulse response are zero for negative time values. The graphical convolution process...
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:17
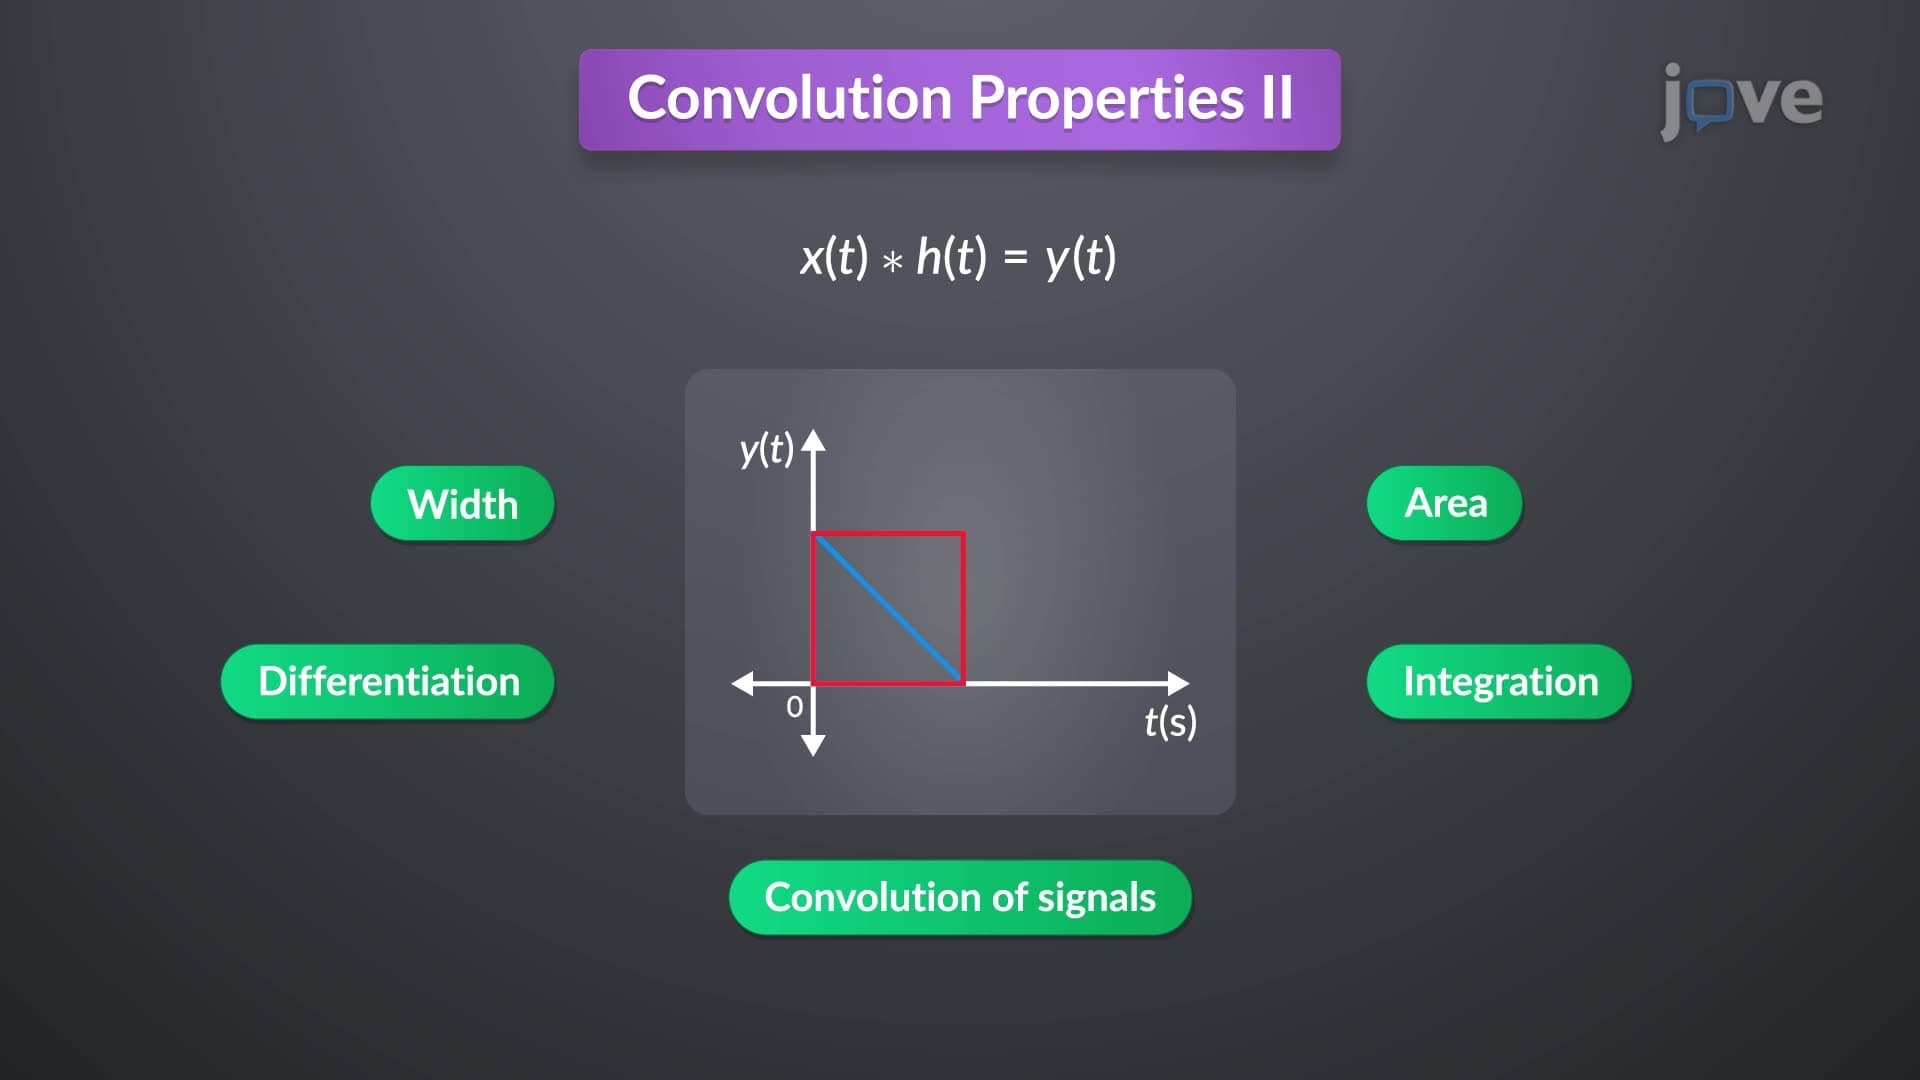
Convolution Properties II
The width property indicates that if the durations of input signals are T1 and T2, then the width of the output response equals the sum of both durations, irrespective of the shapes of the two functions. For instance, convolving two rectangular pulses with durations of 2 seconds and 1 second results in a function with a width of 3 seconds.
The area property asserts that the area under the...
 01:20
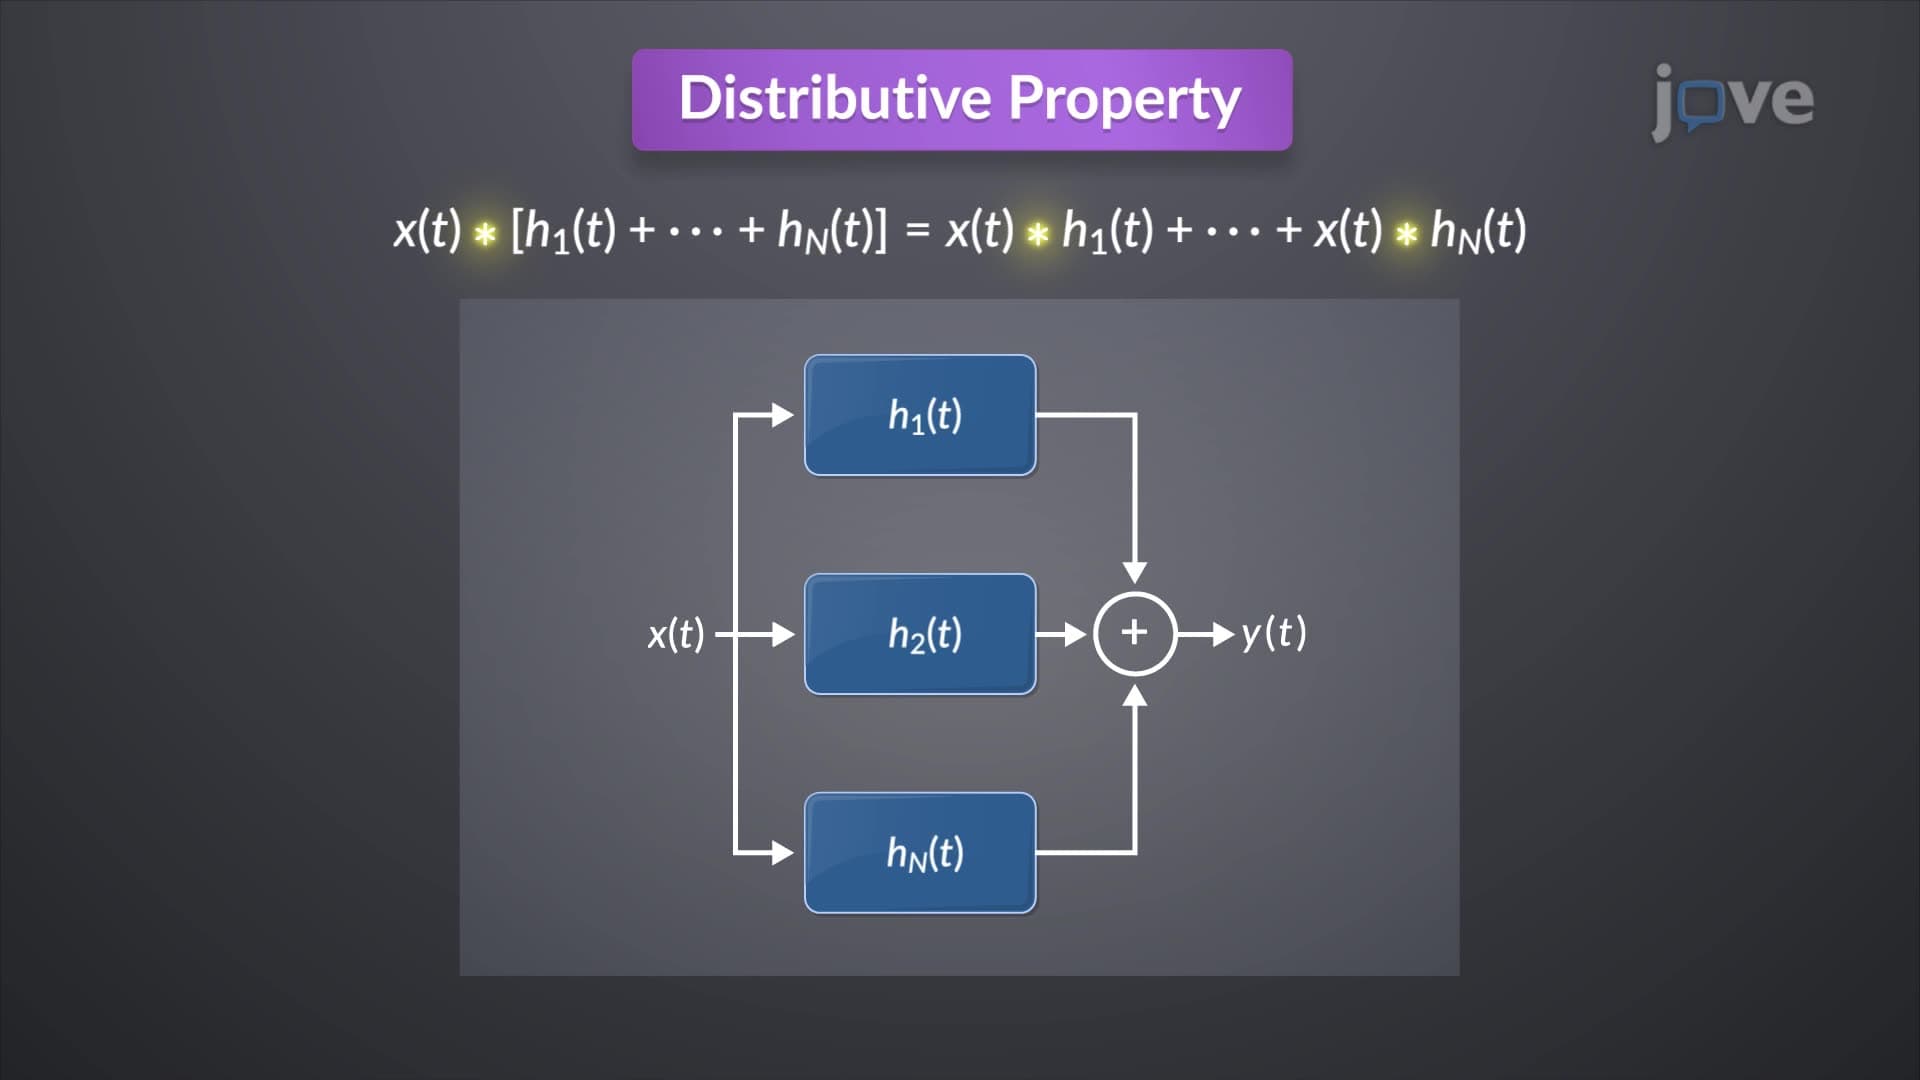
Convolution Properties I
The commutative property reveals that the input and the impulse response of an LTI (Linear Time-Invariant) system can be interchanged without affecting the output:
 01:20
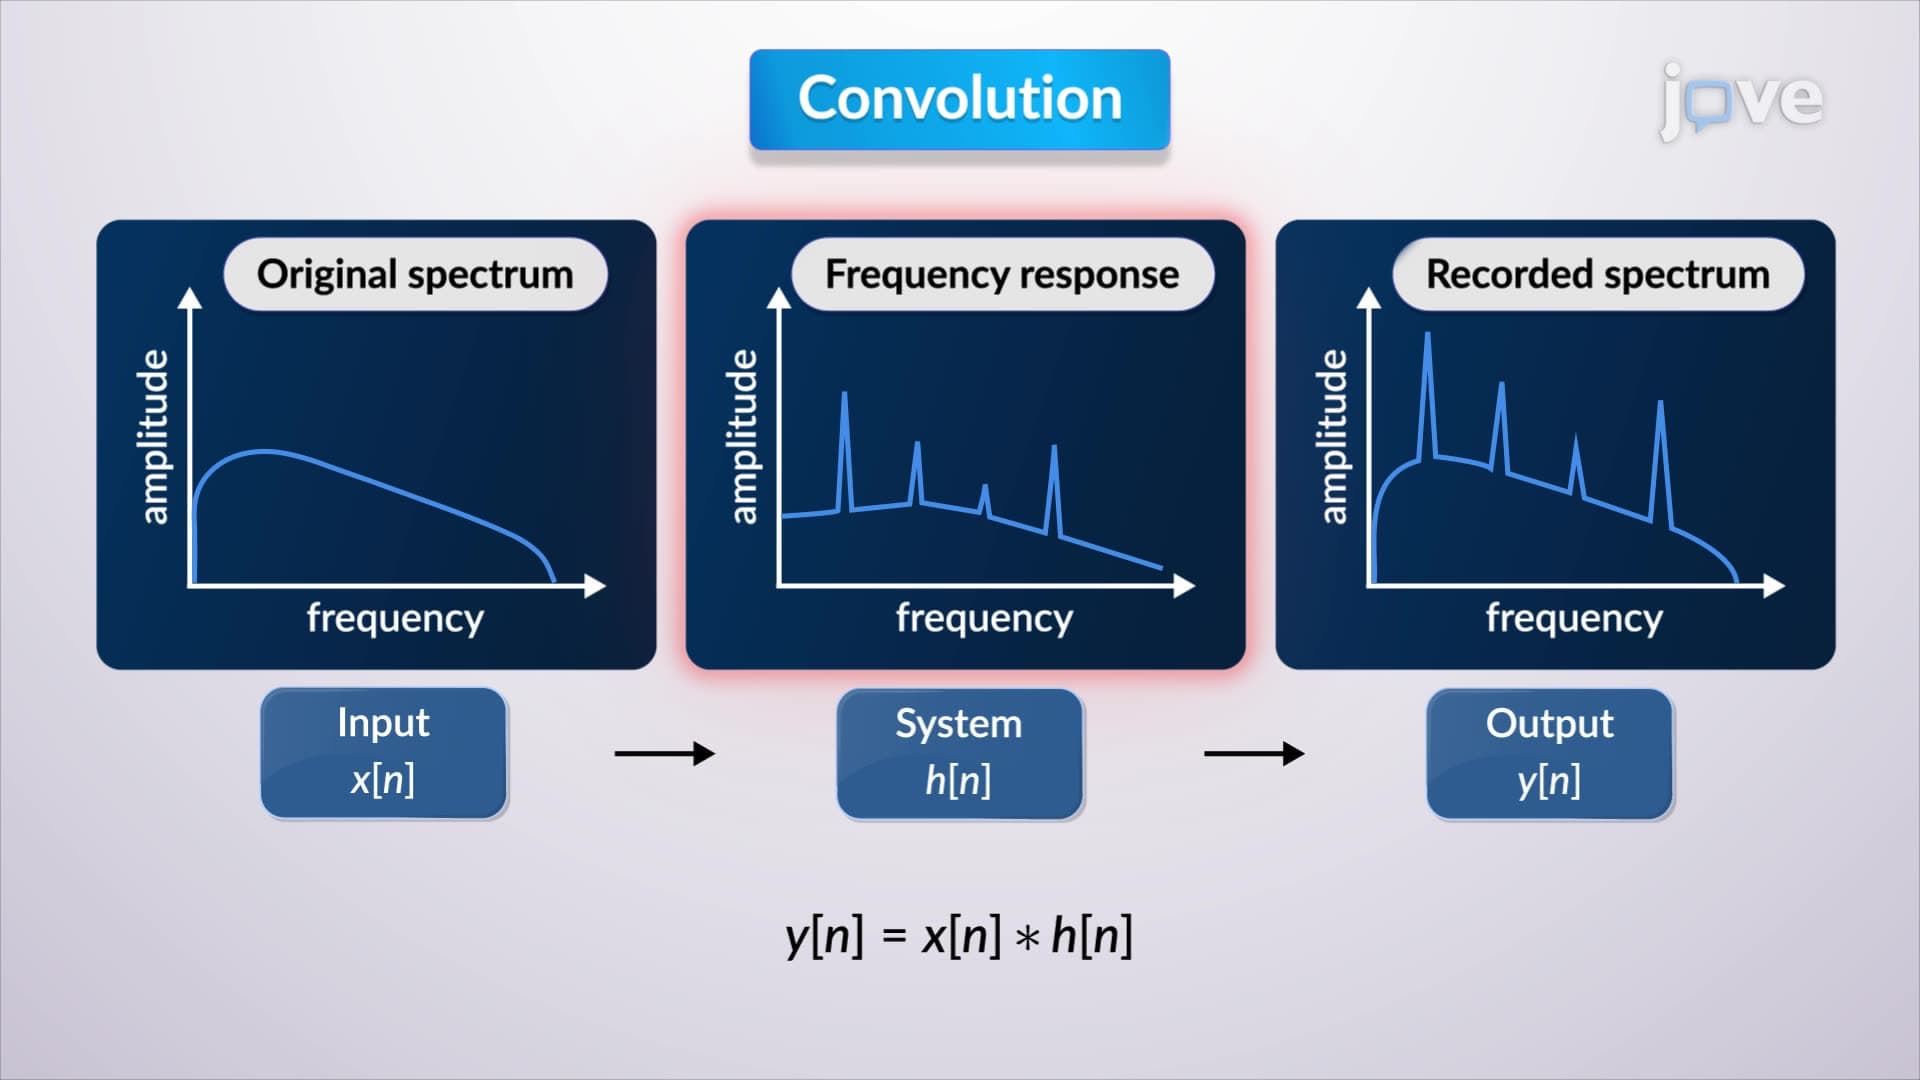
Deconvolution
Deconvolution involves several mathematical techniques to derive the impulse response. One common approach is polynomial division. In this method, the input and output sequences are treated as coefficients of...
 01:26
Linear Approximation in Frequency Domain
In contrast, nonlinear systems do not inherently possess these properties. However, for small deviations around an operating point, a nonlinear system can often be approximated as linear....