Related Experiment Video
Updated: Jan 7, 2026
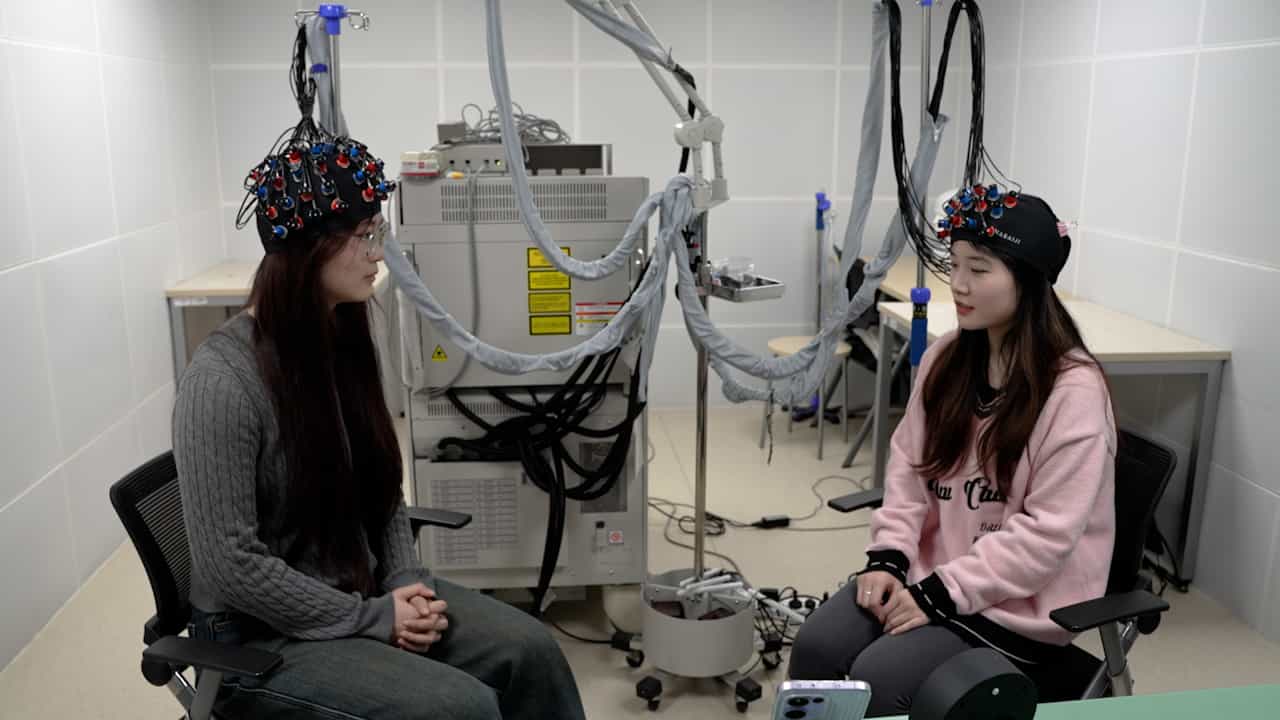

Functional Near-Infrared Spectroscopy Hyperscanning Study in Psychological Counseling
Published on: January 17, 2025
SSE forecasts based on market-sentiment dual anchoring
Lei Yang1, Bo Gan1, Xueyan Niu1
1Department of Business Administration, Shandong Labor Vocational and Technical College, Jinan, China.

Abstract:
Anchoring is widely considered one of the most robust and consistently observed effects in experimental psychology. This study employs the highest and lowest indices of the Shanghai Stock Exchange (SSE) alongside the highest and lowest bullish sentiments over a 52-week period as anchors, in conjunction with Fibonacci retracement levels, to develop a dual market-sentiment anchoring multivariate feature matrix. Based on this feature matrix, we propose a forecasting model called Market Sentiment Dual Anchoring CNN2D-ABiLSTM (MSD-CNN2D-ABiLSTM). This model employs CNN2D to extract spatial features from market and sentiment data, utilizes BiLSTM networks to process and integrate temporal features, and incorporates an attention mechanism to emphasize essential spatial and temporal information. Experimental results indicate that this model achieves a prediction accuracy exceeding 90% and an R2 value greater than 95% for lags of 1-2 trading days, enabling precise forecasting of the SSE index. Additionally, the model demonstrates effective forecasting performance for up to 10 trading days ahead, significantly outperforming traditional baseline models. Furthermore, structural sensitivity tests reveal that the extraction of local spatial features by CNN2D provides a predictive advantage over the short-term temporal features captured by CNN1D in complex market structures.
Related Concept Videos
 01:25
The Anchoring-and-Adjustment Heuristic
 01:26
Equity Theory
 01:09
First Impression
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:29
Econometric Views (EViews)
 01:12
Hindsight Biases