Related Experiment Video
Updated: Aug 27, 2026
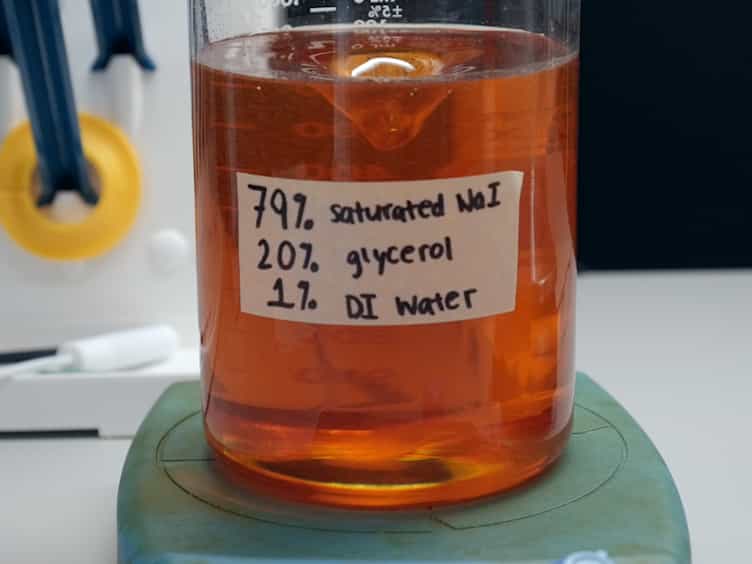

Experimental Investigation of Secondary Flow Structures Downstream of a Model Type IV Stent Failure in a 180° Curved Artery Test Section
Published on: July 19, 2016
Weak convergence of stochastic integrals on Skorokhod space in Skorokhod's J 1 and M 1 topologies
Andreas Søjmark1, Fabrice Wunderlich2
1Department of Statistics, London School of Economics, London, WC2A 2AE UK.

Abstract:
We provide criteria for Itô integration to behave continuously with respect to Skorokhod's and topologies, when the integrands and integrators converge weakly or in probability. The results are novel in the setting and unify existing theories in the case. Beyond sufficient criteria, we present an example of uniformly convergent martingale integrators for which the continuity breaks down. Moreover, we show that, for families of local martingales, tightness in fact implies tightness under a mild localised uniform integrability condition. Finally, we apply our results to study scaling limits of models of anomalous diffusion driven by continuous-time random walks. This yields new results on weak and convergence to stochastic integrals against subordinated stable processes. In the case of superdiffusive scaling, an interesting counterexample is obtained.
Related Concept Videos
 01:06
Divergence and Stokes' Theorems
 01:23
Integrals of Vector Functions
 01:26
Convergence of Sequences
 01:20
Region of Convergence of Laplace Tarnsform
Consider a decaying exponential signal that begins at a specific time. When deriving its Laplace transform, the time-domain variable is replaced with a complex variable. This substitution...
 01:27
Applications of Integration to Probability Density Functions
 01:21
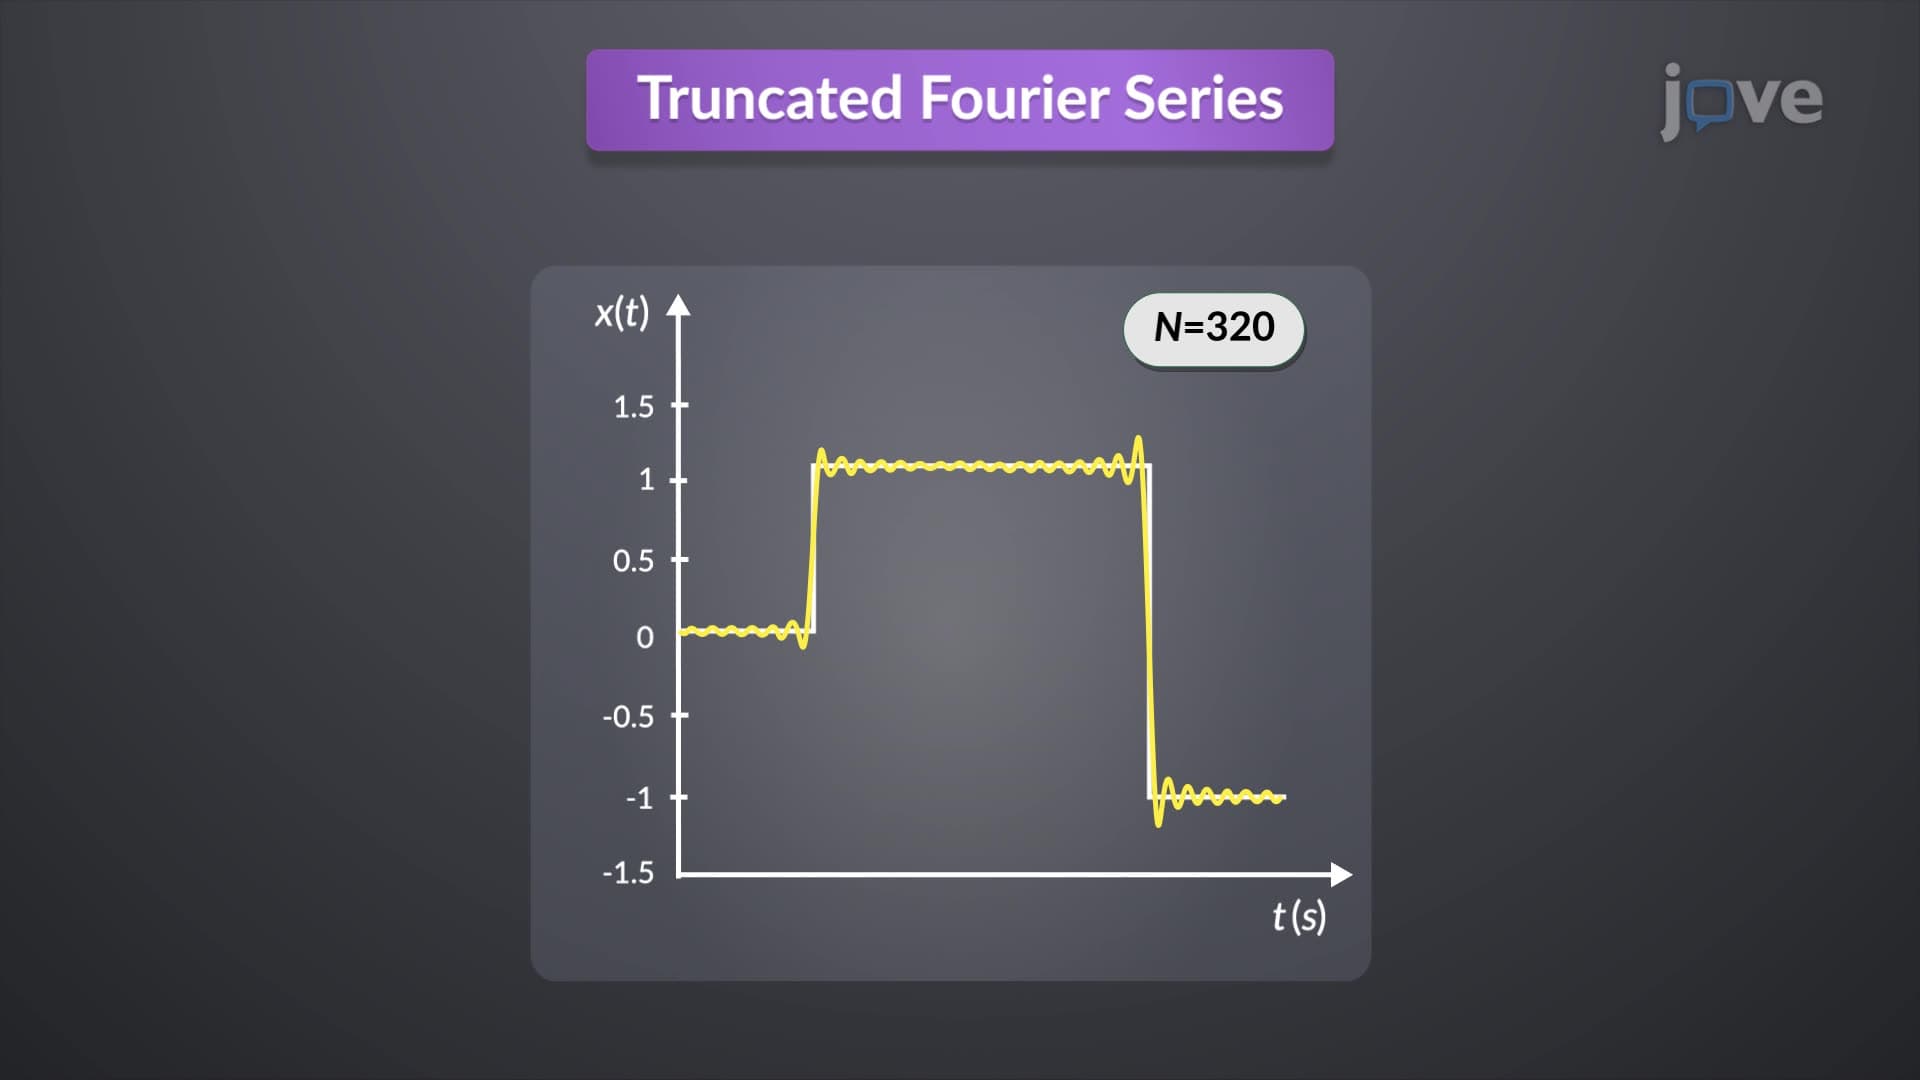
Convergence of Fourier Series
The Gibbs phenomenon refers to the persistent oscillations and overshoots that occur near discontinuities...