Related Experiment Videos
Iterative spectral methods for Hamilton-Jacobi-Bellman quasi-variational inequality in finance
1School of Mathematics, Southwestern University of Finance and Economics, Chengdu, Sichuan, China.

Abstract:
This study proposes a novel computational scheme for utility-maximization problems involving optimal stopping, formulated as Hamilton-Jacobi-Bellman quasi-variational inequalities. The methodology integrates Gauss-Lobatto-Legendre spectral discretization with a penalization method and is solved efficiently via policy iteration. We establish the convergence of the penalized scheme and verify the effectiveness and robustness of the framework through a series of numerical experiments.
Related Concept Videos
 01:28
Iterated Integrals and Fubini's Theorem
 01:28
Lagrange Multipliers: Two Constraints
 01:22
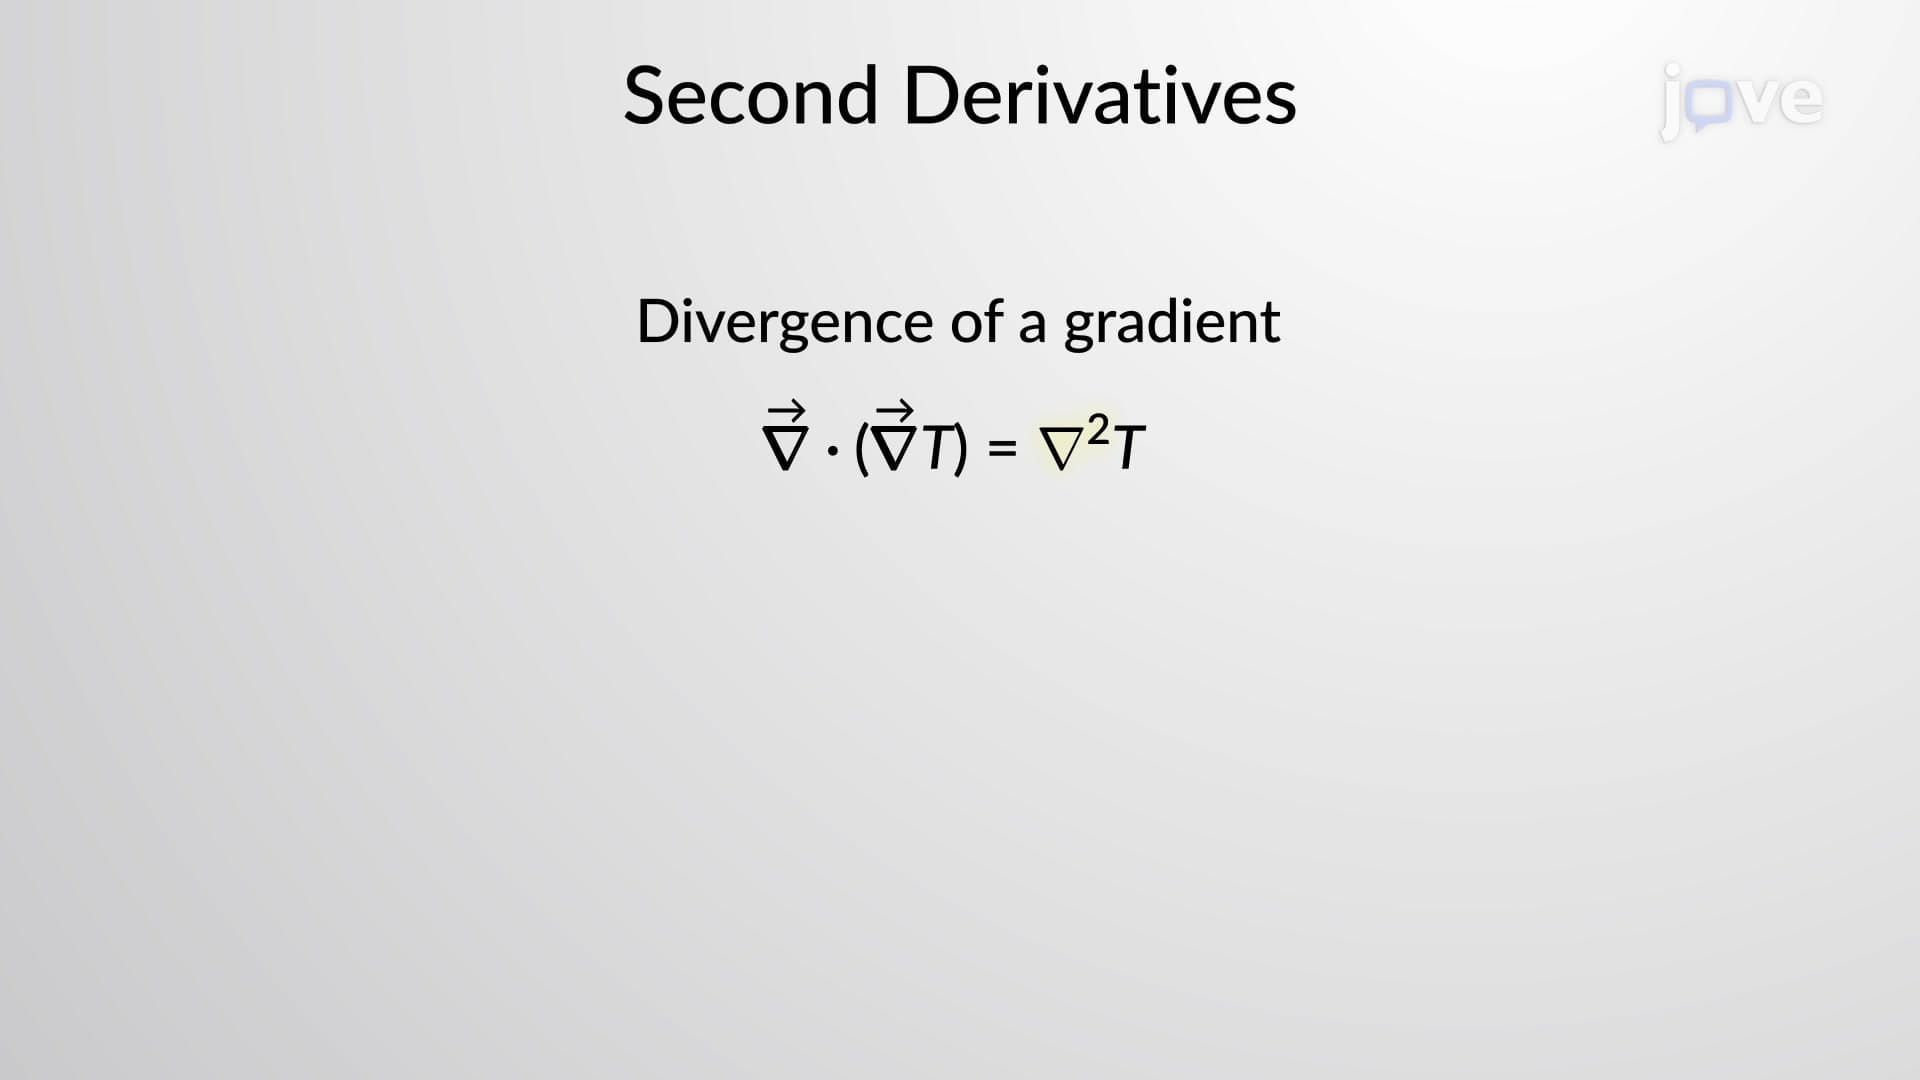
Second Derivatives and Laplace Operator
Consider a scalar function. The curl of its...
 01:30
Lagrange Multipliers: Problem Solving
 01:21
Partial Differential Equations
 01:29
Lagrange Multipliers: One Constraint