Related Experiment Videos
Faster Hamiltonian Monte Carlo by learning leapfrog scale: an offline randomized solution
Changye Wu1, Pierre Pudlo2, Christian P Robert1,3
1CEREMADE, Université Paris-Dauphine, Université PSL, CNRS, 75016 Paris, France.

Abstract:
We introduce a Hamiltonian Monte Carlo (HMC) methodology based on an offline empirical calibration of randomized leapfrog parameters. The approach, referred to as eHMC, where e stands for empirical, leverages importance sampling to construct an empirical distribution on discretization parameters, thereby eliminating the need for manual burn-in diagnostics and online adaptation. The proposal distribution used in the calibration stage is obtained via a Population Monte Carlo scheme with tempering and relies on flexible parametric variational families such as normalizing flows. Once the calibration stage complete, the resulting algorithm defines a homogeneous Markov chain via a mixture of HMC kernels with a fixed mixing distribution, and hence preserves the target distribution. Numerical experiments indicate that eHMC can achieve competitive or improved sampling efficiency compared to the No-U-Turn Sampler (NUTS) in the case useful integration times can be summarized by the offline distribution. The comparison is assessed by standard efficiency metrics normalized by the number of leapfrog steps during the post-calibration sampling phase.
Related Concept Videos
 01:24
Fast Decoupled and DC Powerflow
 01:30
Lagrange Multipliers: Problem Solving
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:13
Randomized Experiments
Simple randomization
Simple...
 01:30
Machines: Problem Solving II
 01:16
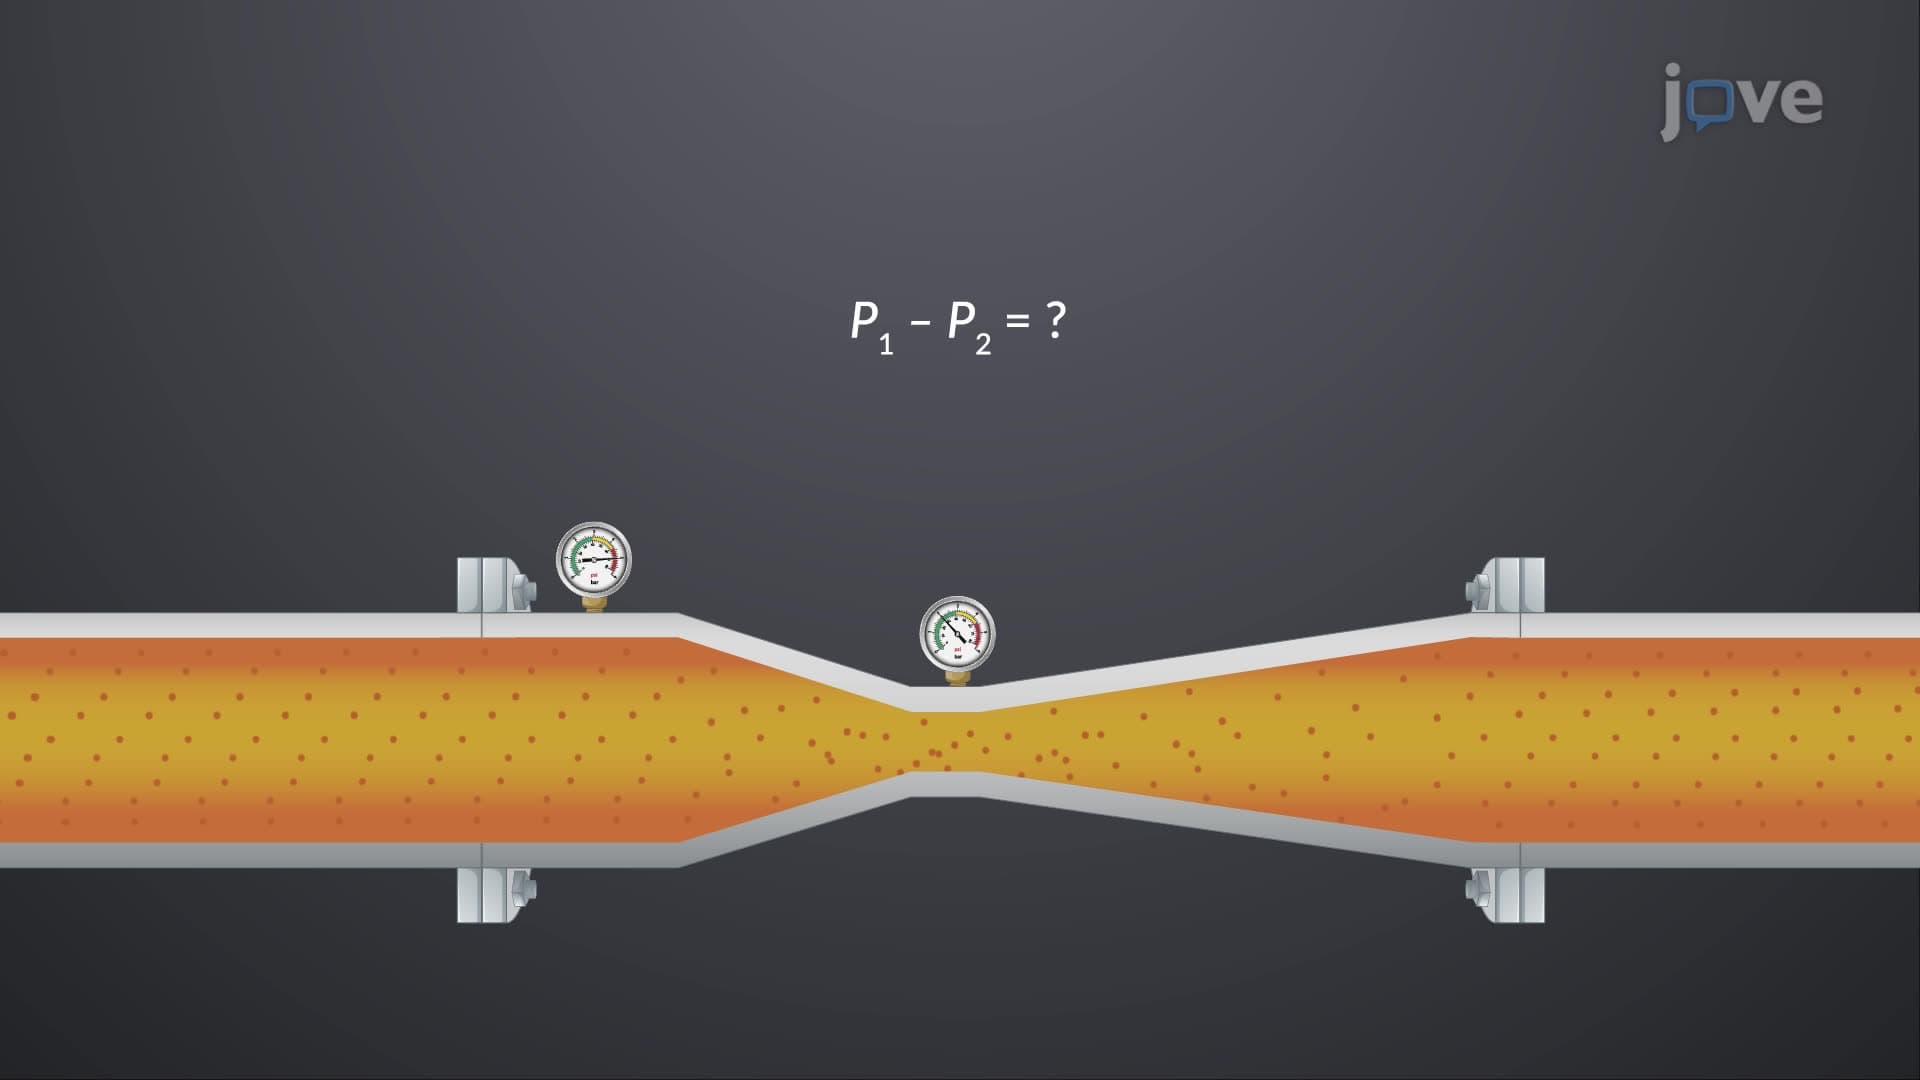
Bernoulli's Equation: Problem Solving
The first step is to compute the cross-sectional areas of the pipe and the Venturi throat to analyze the pressure difference indicated by the pressure gauge. Next, the continuity equation is...