Robust elementwise estimation of a dispersion matrix
Related Experiment Video
Updated: Aug 6, 2026
Generation and Coherent Control of Pulsed Quantum Frequency Combs
Published on: June 8, 2018
1G.D.Searle & Company, Skokie, Illinois 60077, USA.

Abstract:
Most of the existing robust methods for estimating a covariance or correlation matrix involve a multivariate approach in which matrix elements are estimated via simultaneous manipulation of all variables. These methods are generally based on complex iterative algorithms and hence are rather difficult to implement. The purpose of this article is to recommend an easy to implement noniterative robust method for estimating a dispersion matrix, based on an elementwise estimation approach. Simple expressions are provided for robust estimators of variances and covariances based, in part, on a modified A-estimator of scale discussed previously by Lax (1985, Journal of the American Statistical Association 80, 736-741). A Monte Carlo study is used to compare the performance of the proposed noniterative method with that of some iterative procedures studied in the literature. A numerical example involving robust estimation of variance components is presented as an application of the proposed methodology.
Related Concept Videos
 00:54
Distribution and Dispersion
 01:14
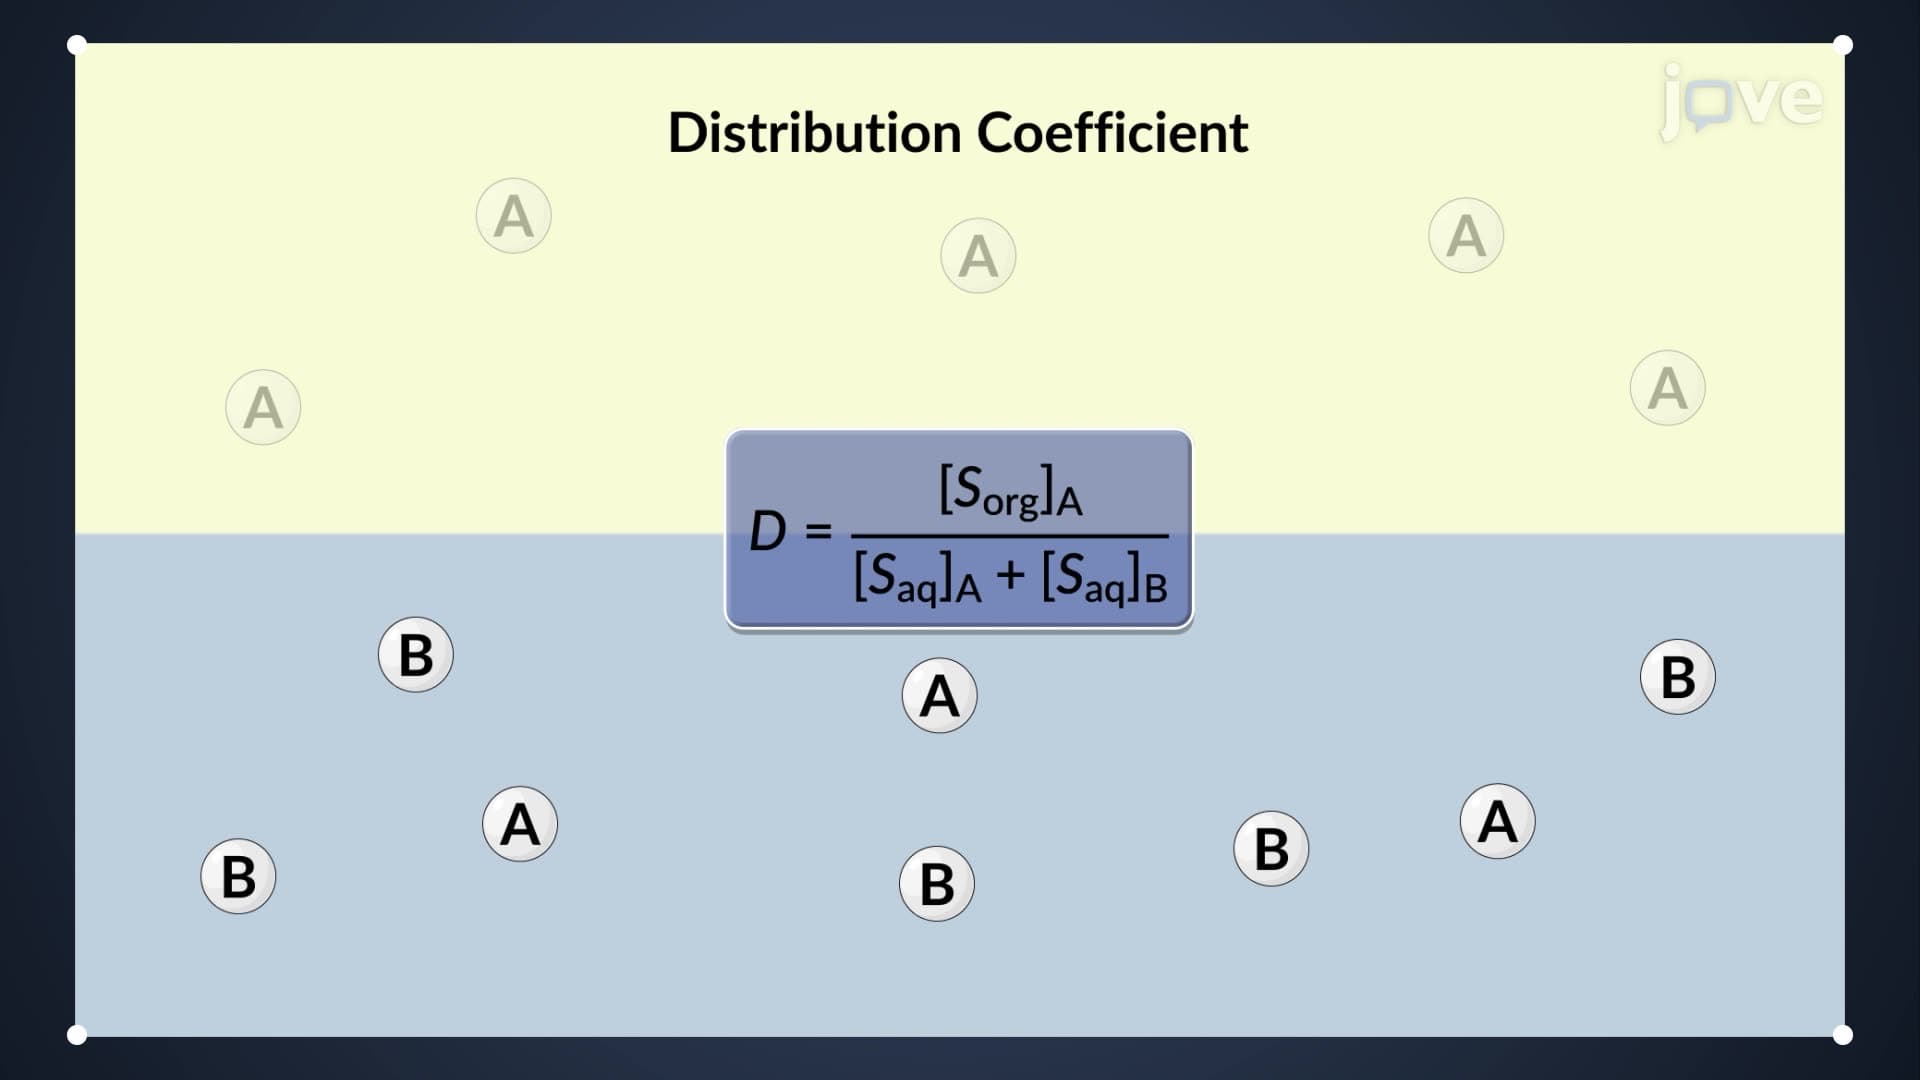
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an organic...
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...
 01:26
Estimating Population Standard Deviation
 01:05
Estimation of the Physical Quantities
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...