Orthogonal series density estimation and the kernel eigenvalue problem
Related Experiment Video
Updated: Jul 10, 2026
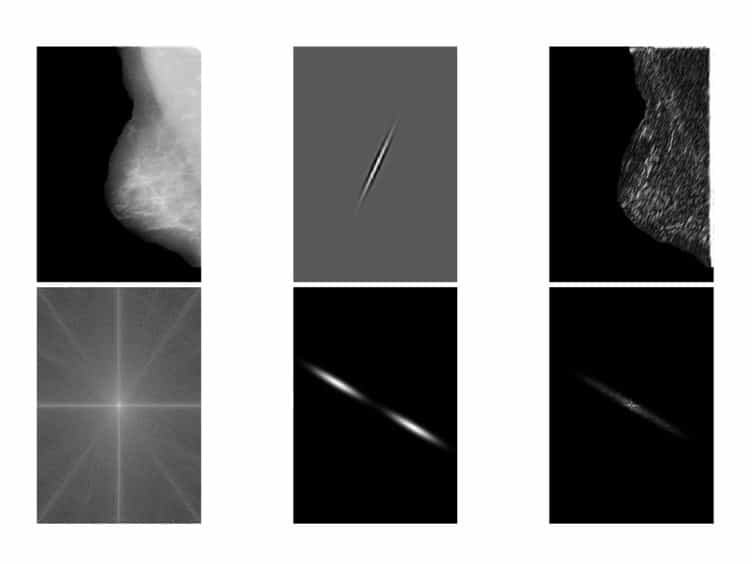
Detection of Architectural Distortion in Prior Mammograms via Analysis of Oriented Patterns
Published on: August 30, 2013

Abstract:
Kernel principal component analysis has been introduced as a method of extracting a set of orthonormal nonlinear features from multivariate data, and many impressive applications are being reported within the literature. This article presents the view that the eigenvalue decomposition of a kernel matrix can also provide the discrete expansion coefficients required for a nonparametric orthogonal series density estimator. In addition to providing novel insights into nonparametric density estimation, this article provides an intuitively appealing interpretation for the nonlinear features extracted from data using kernel principal component analysis.
Related Concept Videos
 01:15
Chebyshev's Theorem to Interpret Standard Deviation
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:21
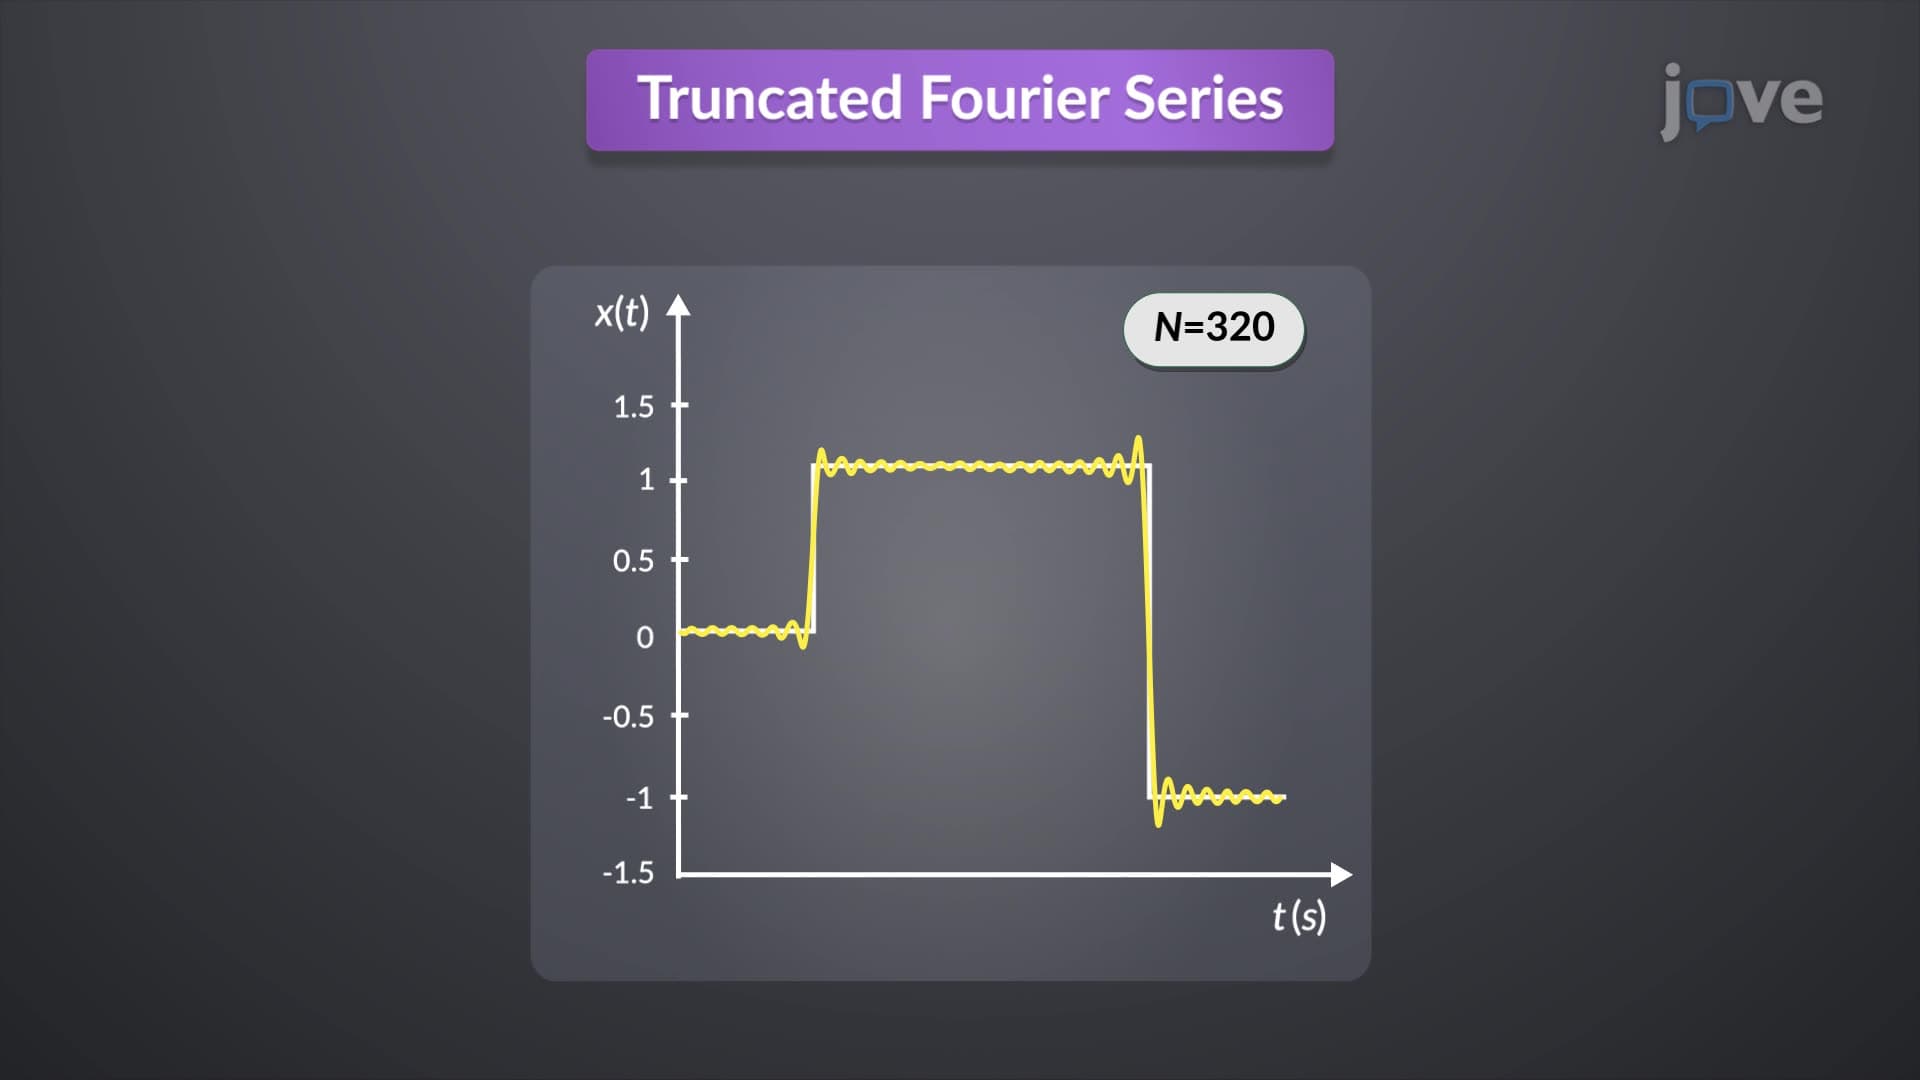
Convergence of Fourier Series
The Gibbs phenomenon refers to the persistent oscillations and overshoots that occur near discontinuities...
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:30
Gaussian Elimination: Problem Solving
 01:26
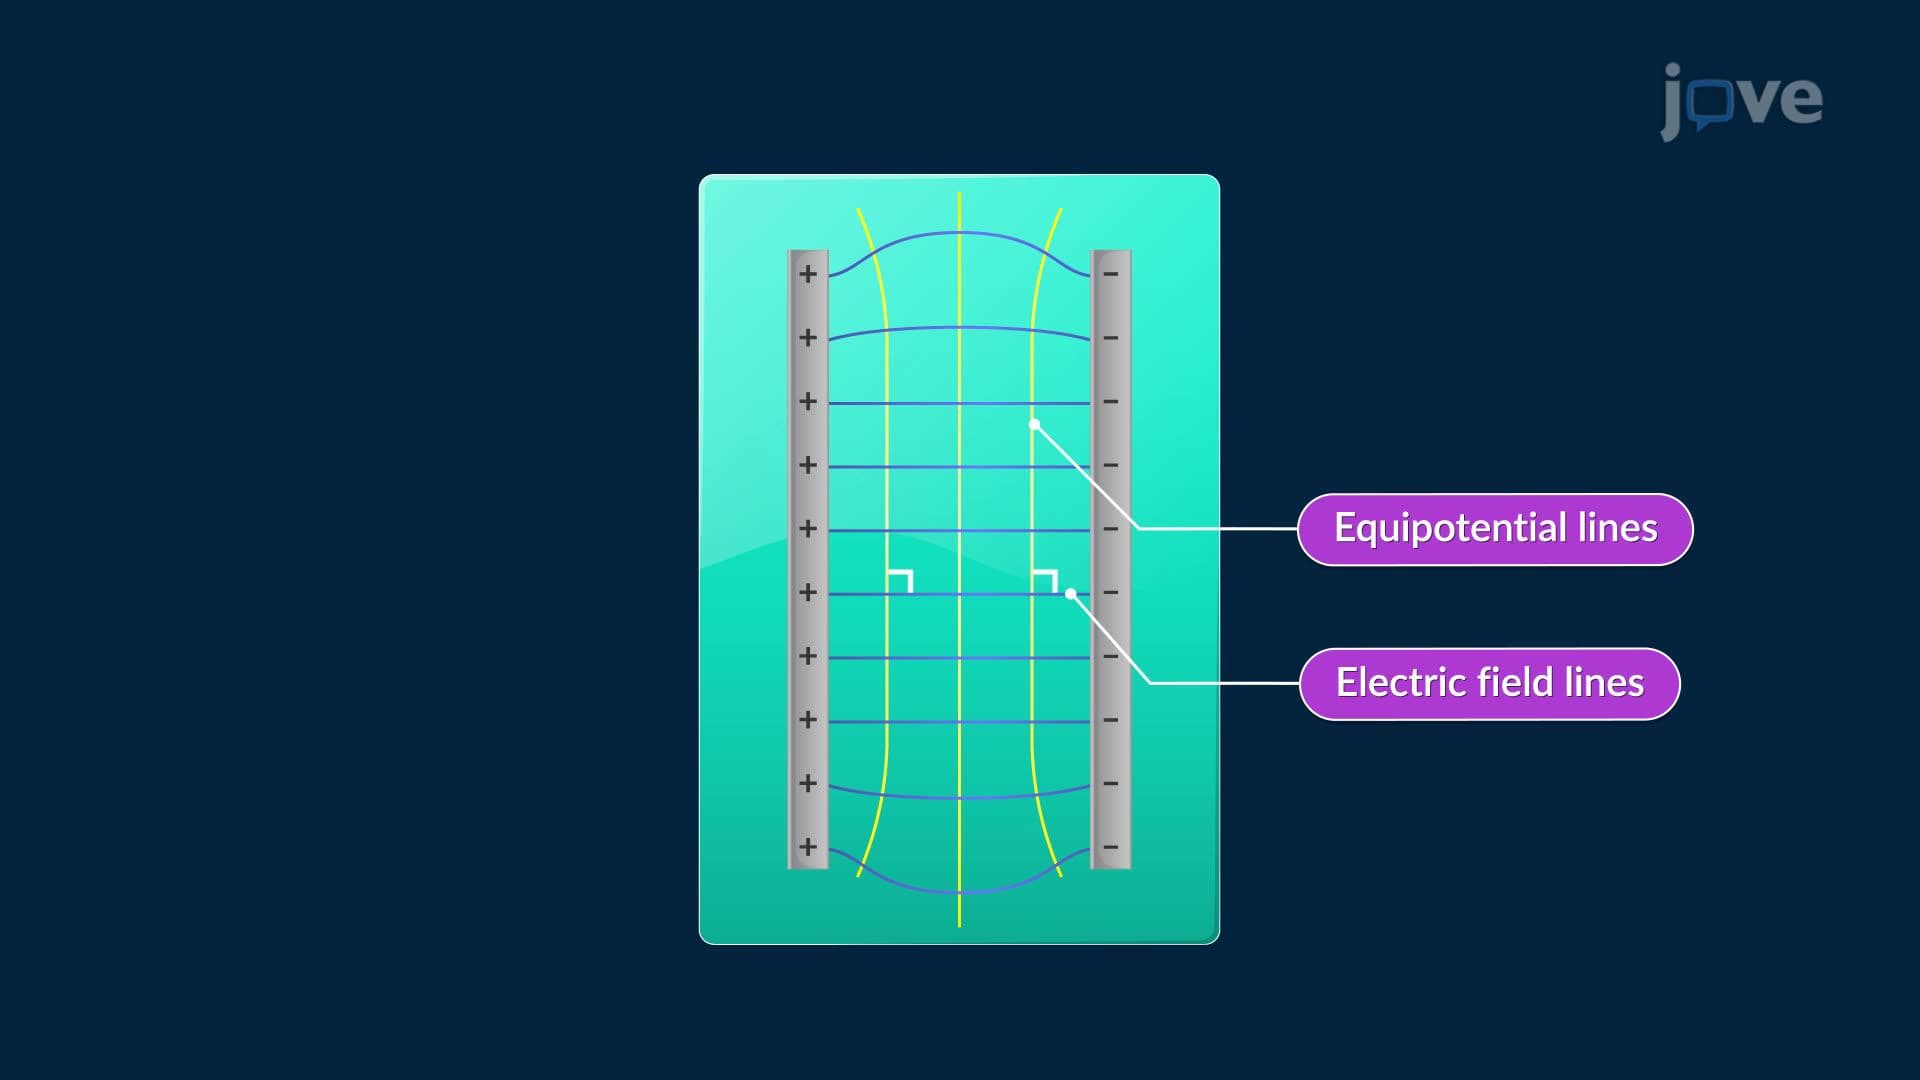
Orthogonal Trajectories