Related Experiment Video
Updated: Sep 25, 2025

A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Forecasting stock market volatility with a large number of predictors: New evidence from the MS-MIDAS-LASSO model
Xiafei Li1, Chao Liang1, Feng Ma1
1School of Economics & Management, Southwest Jiaotong University, No. 111, North 1St Section, 2nd Ring Road, Chengdu, 610031 China.

Abstract:
This paper explores the effectiveness of predictors, including nine economic policy uncertainty indicators, four market sentiment indicators and two financial stress indices, in predicting the realized volatility of the S&P 500 index. We employ the MIDAS-RV framework and construct the MIDAS-LASSO model and its regime switching extension (namely, MS-MIDAS-LASSO). First, among all considered predictors, the economic policy uncertainty indices (especially the equity market volatility index) and the CBOE volatility index are the most noteworthy predictors. Although the CBOE volatility index has the best predictive ability for stock market volatility, its predictive ability has weakened during the COVID-19 epidemic, and the equity market volatility index is best during this period. Second, the MS-MIDAS-LASSO model has the best predictive performance compared to other competing models. The superior forecasting performance of this model is robust, even when distinguishing between high- and low-volatility periods. Finally, the prediction accuracy of the MS-MIDAS-LASSO model even outperforms the traditional LASSO strategy and its regime switching extension. Furthermore, the superior predictive performance of this model has not changed with the outbreak of the COVID-19 epidemic.
More Related Videos
 04:35
Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
 13:54
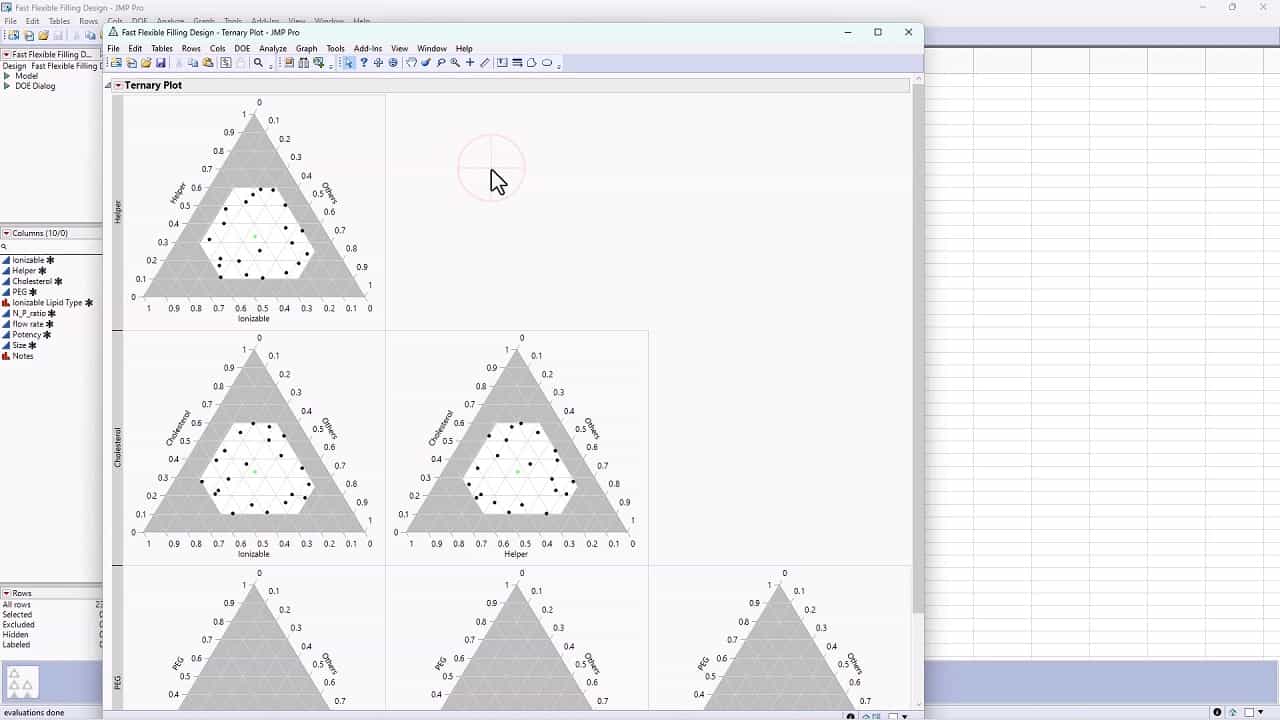
A Workflow for Lipid Nanoparticle LNP Formulation Optimization using Designed Mixture-Process Experiments and Self-Validated Ensemble Models SVEM
Published on: August 18, 2023
Related Concept Videos
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:25
Multiple Regression
Farmers can use multiple regression to determine the crop yield based on more than one factor, such as water availability, fertilizer, soil properties, etc. Here, the crop yield is the response or dependent variable as it depends on the other independent variables. The analysis requires the construction of a scatter plot...
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as:
 01:18
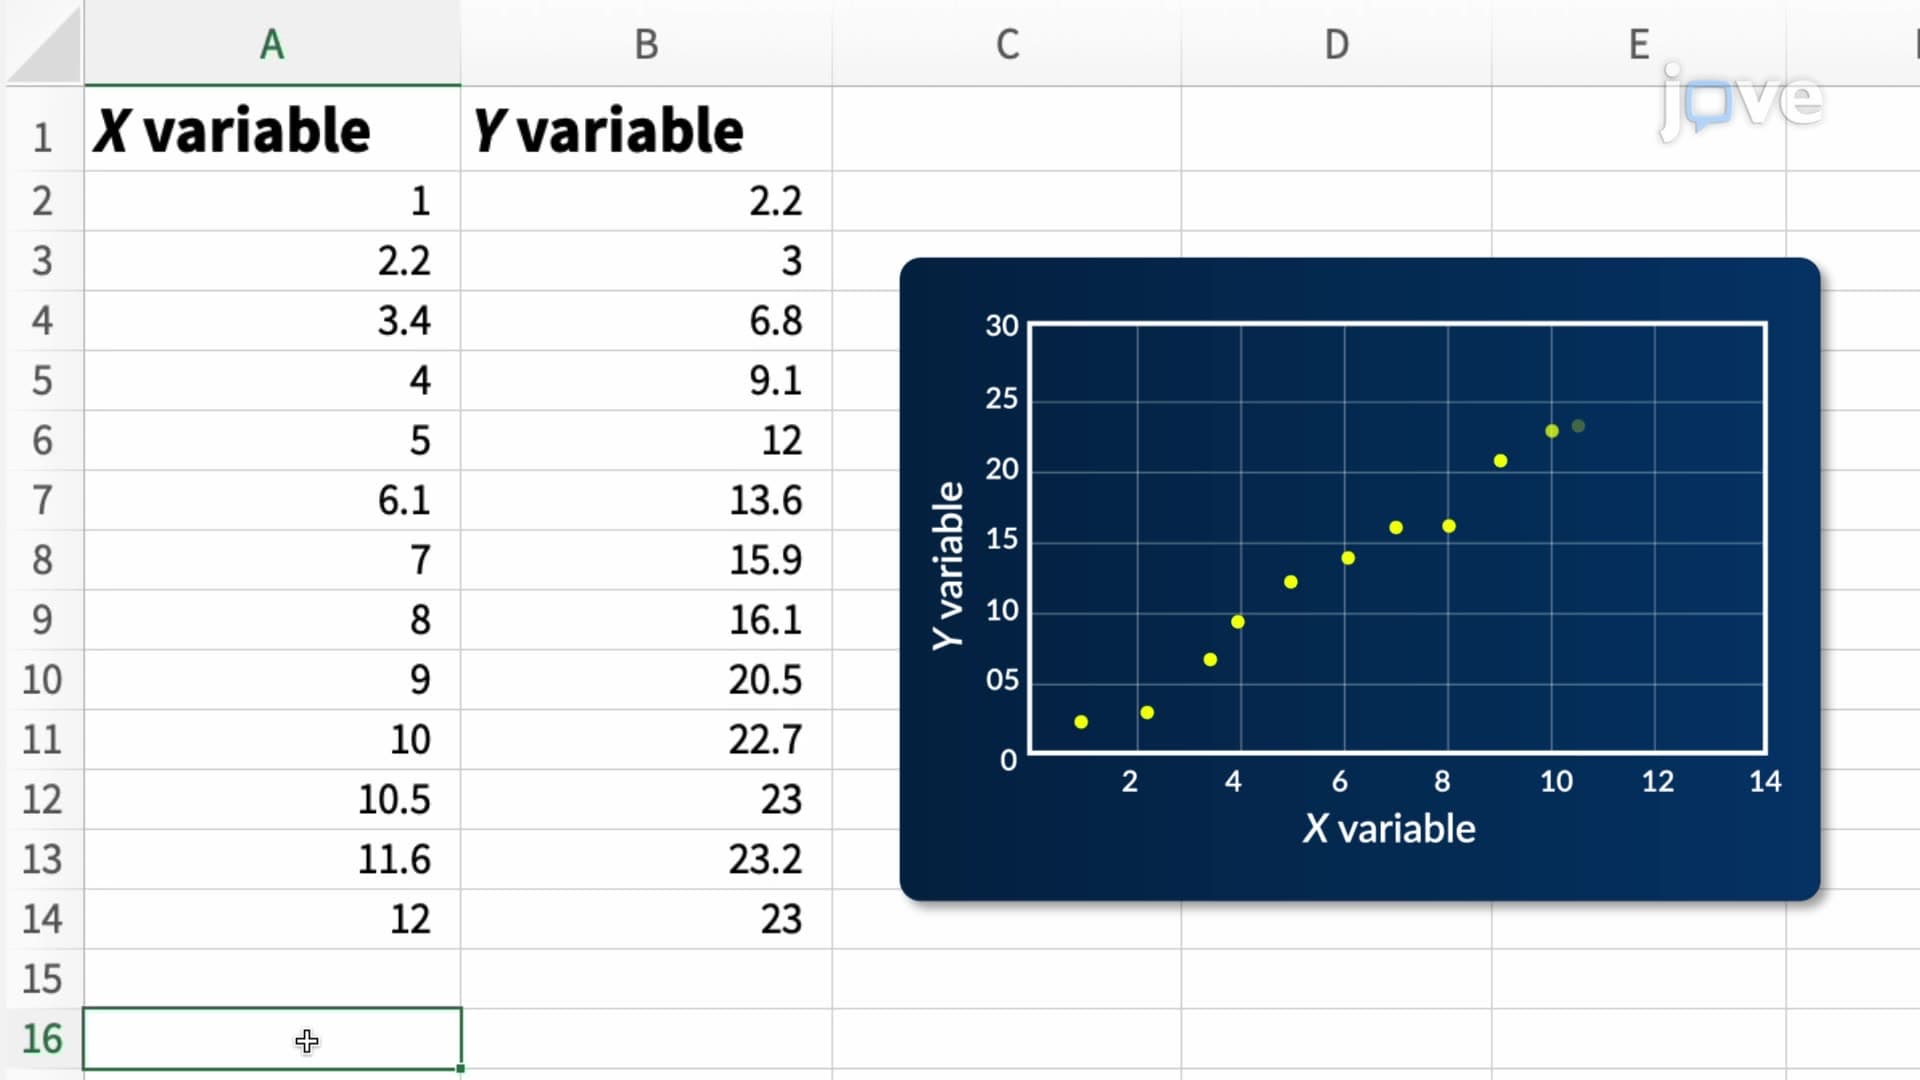
Microsoft Excel: Regression Analysis
To perform regression...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:52
Regression Toward the Mean