Related Experiment Video
Updated: Sep 8, 2025


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Time varying factor models with possibly strongly correlated noises
Mingjing Chen1, Xiangyong Tan2, Jian Wu3
1College of Mathematics and Statistics, Chongqing Technology and Business University, Chongqing, People's Republic of China.

Abstract:
In factor models, noises are often assumed to be weakly correlated; otherwise, separation of factors from noises becomes difficult, if not impossible. This paper will address this problem. We utilize an econometric idea, the so called common correlated effects (CCE) to estimate time varying factor models. We first cross sectionally average the covariates and then project the responses to the space spanned by the averaged covariates. By doing so, noises are diminished while factors are distinguished. The advantages of our new estimators are two folds. First, the convergence rates of estimated factors and loadings are independent of cross sectional dimension. Second, our new estimators are robust to the correlation of noises. Hence our new estimators can, on one hand, separate market factors for the stock data set used in this paper even if noises exhibit strong correlations within industries due to industry-specific factors and on the other hand, avoid inappropriately absorbing industry-specific factors into market factors.
More Related Videos
Related Concept Videos
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 00:56
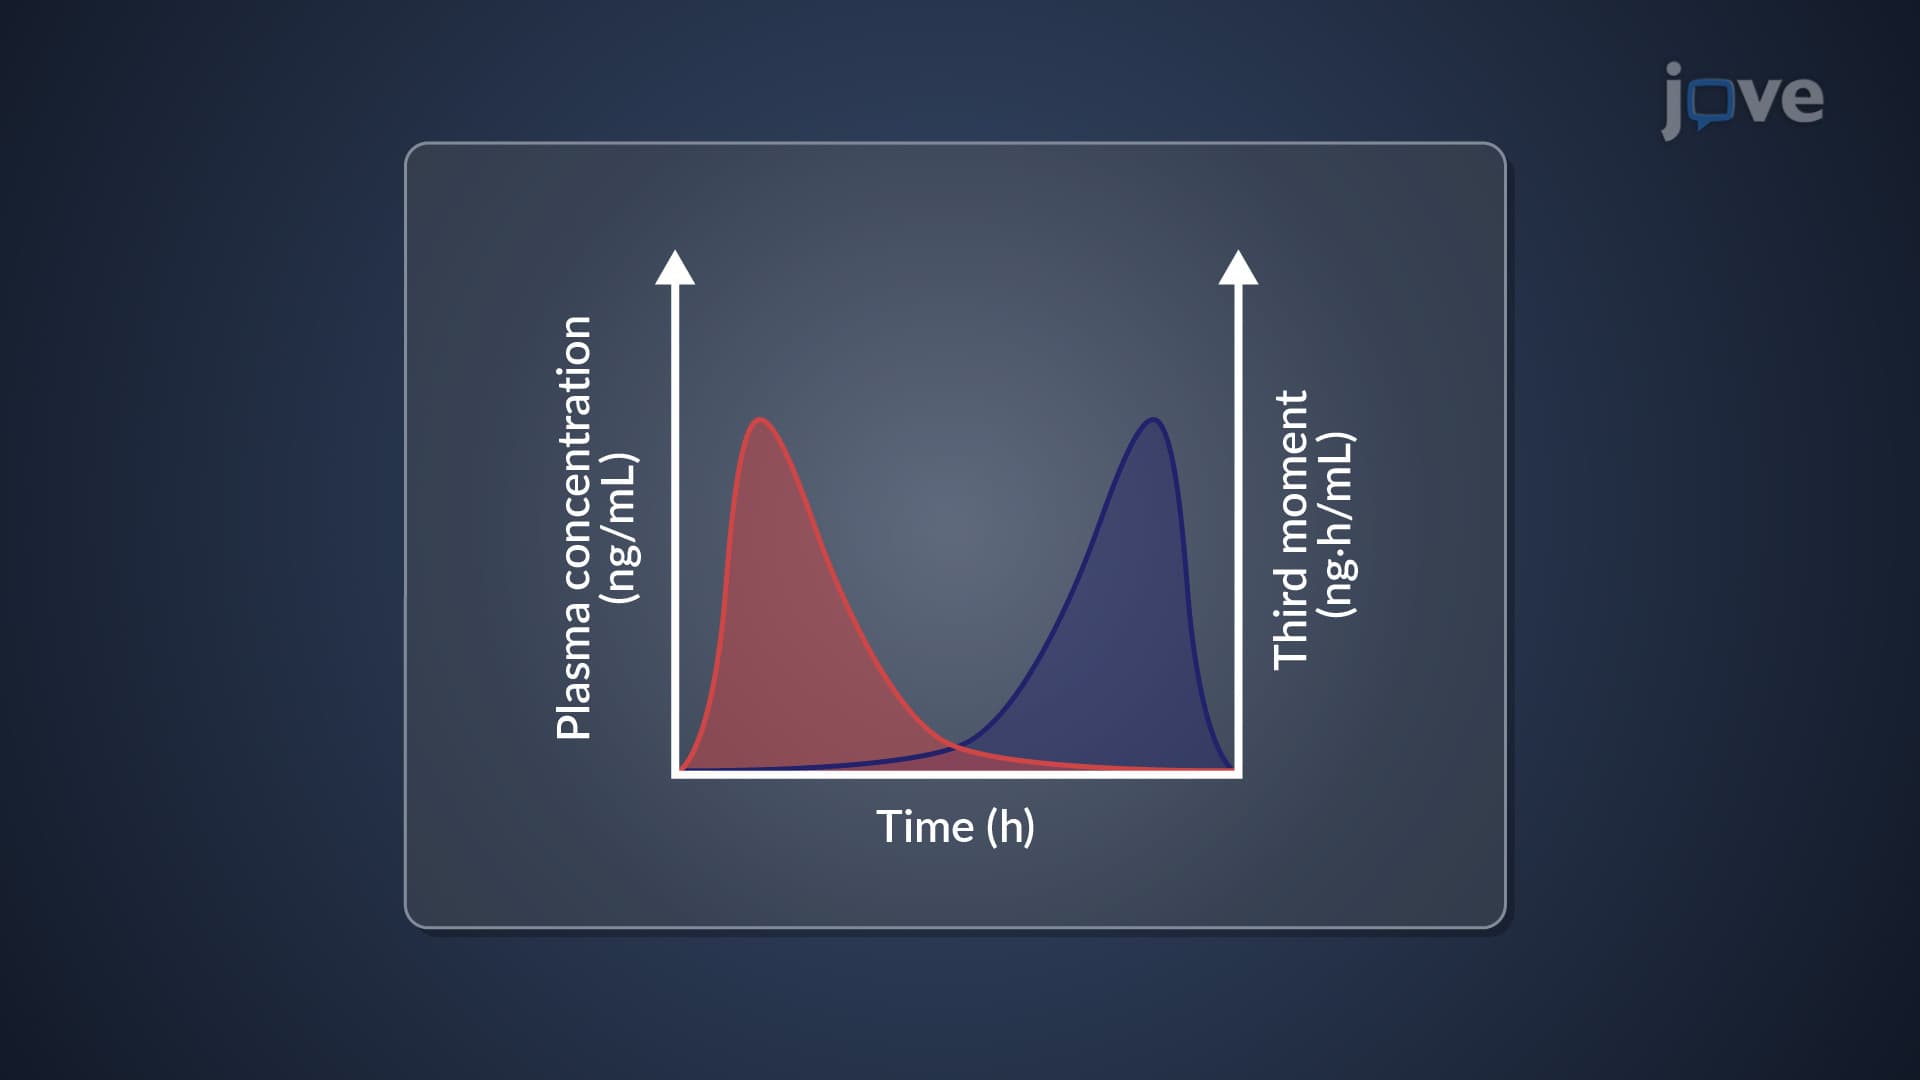
Noncompartmental Analysis: Statistical Moment Theory
 01:23
Linear time-invariant Systems
The input-output behavior of an LTI system can be fully defined by its response to an impulsive excitation at its input. Once this impulse response is known, the system's reaction to any other input can be...
 01:22
Basic Continuous Time Signals
The unit step function, denoted u(t), is zero for negative time values and one for positive time values, exhibiting a discontinuity at t=0. This function often represents abrupt changes, such as the step voltage introduced when turning a car's...
 01:21
Linear Approximation in Time Domain
For a simple pendulum with a mass evenly distributed along its length and the center of mass located at half the pendulum's length,...
 01:09
Random Variables
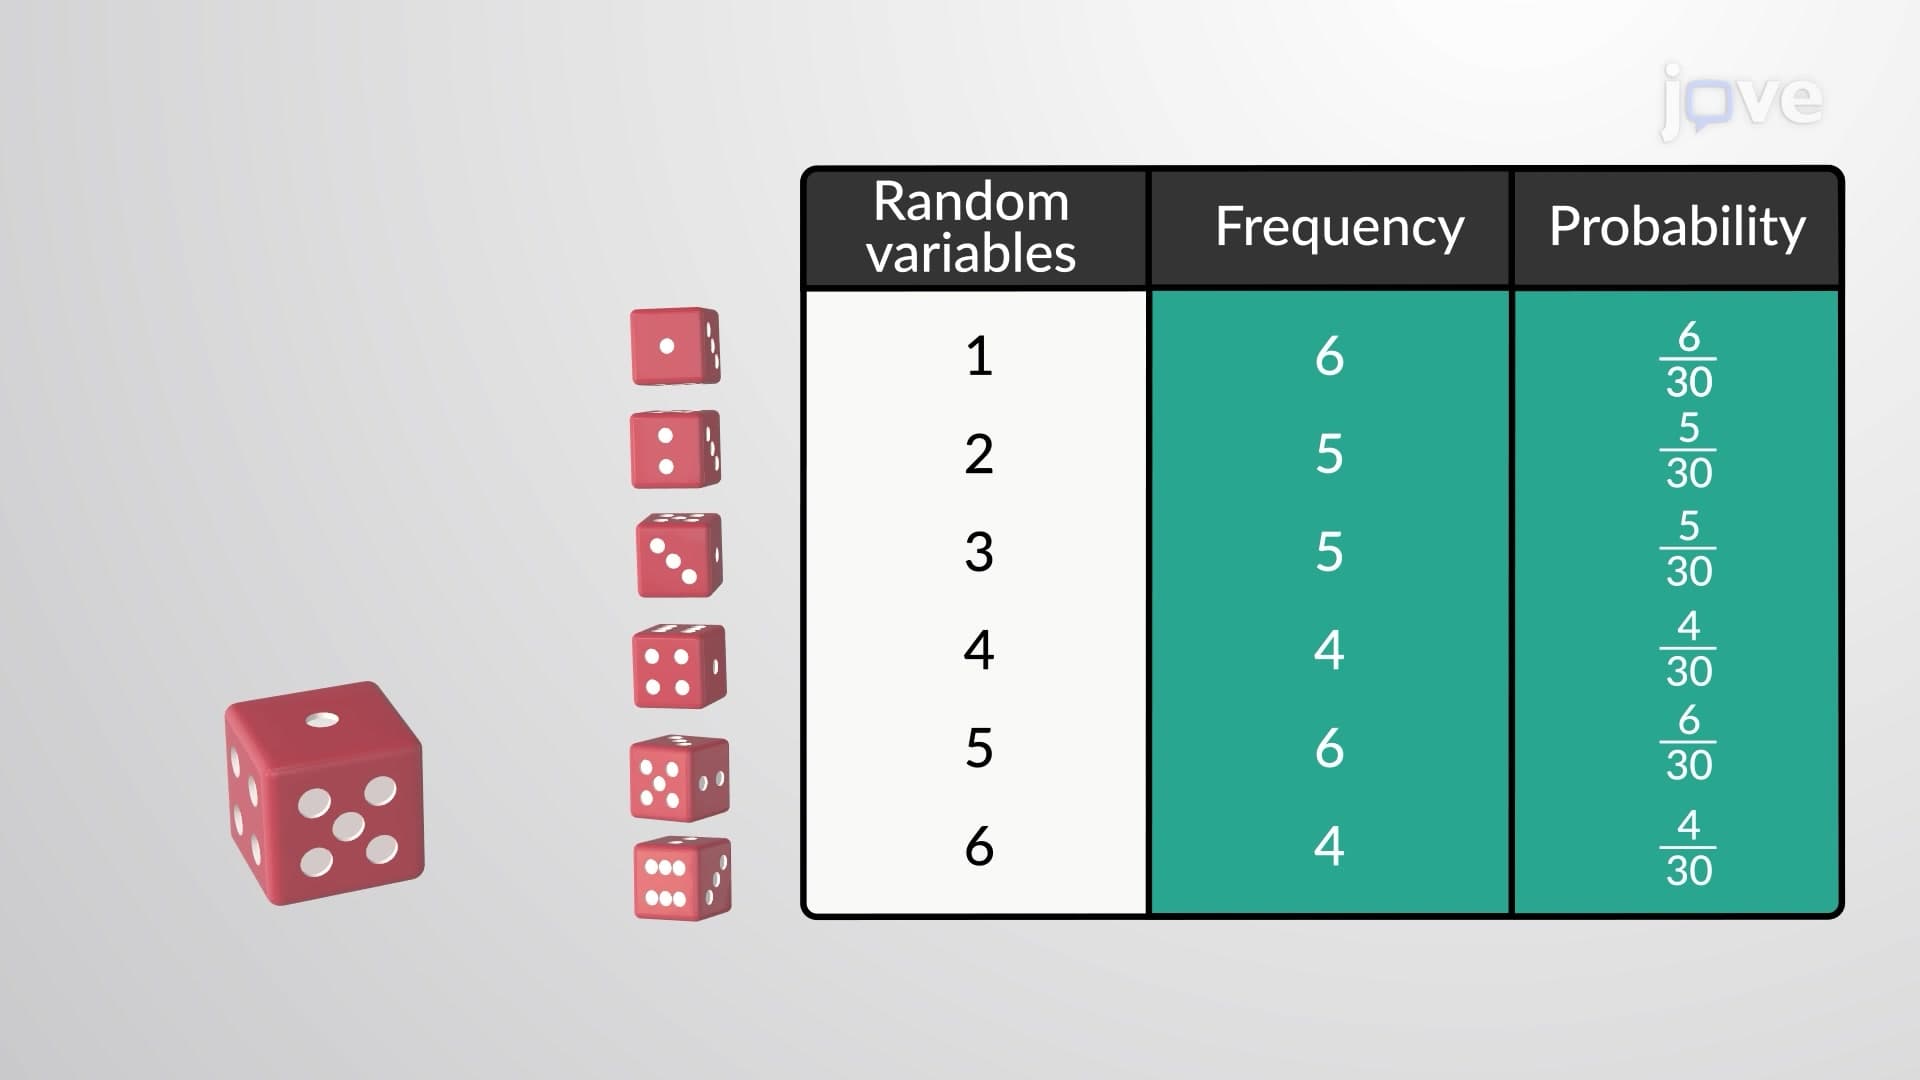
Uppercase letters such as X or Y denote a random variable. Lowercase letters like x or y denote the value of a random variable. If X is a random variable, then X is written in words, and x is given as a number.
For example, let X = the...