Related Experiment Video
Updated: Aug 30, 2025

Author Spotlight: An Efficient and Robust Software for Automated Fusion of Multiple Preclinical Imaging Modalities
Published on: October 27, 2023
Covariance estimation via fiducial inference
W Jenny Shi1, Jan Hannig2, Randy C S Lai3
1Financial Planning & Analysis, MassMutual, One Marina Park Dr., Boston, MA 02111.

Abstract:
As a classical problem, covariance estimation has drawn much attention from the statistical community for decades. Much work has been done under the frequentist and the Bayesian frameworks. Aiming to quantify the uncertainty of the estimators without having to choose a prior, we have developed a fiducial approach to the estimation of covariance matrix. Built upon the Fiducial Berstein-von Mises Theorem (Sonderegger and Hannig 2014), we show that the fiducial distribution of the covariate matrix is consistent under our framework. Consequently, the samples generated from this fiducial distribution are good estimators to the true covariance matrix, which enable us to define a meaningful confidence region for the covariance matrix. Lastly, we also show that the fiducial approach can be a powerful tool for identifying clique structures in covariance matrices.
More Related Videos

Related Concept Videos
 01:10
Calibration Curves: Correlation Coefficient
 01:20
Calibration Curves: Linear Least Squares
For data that follow a straight line, the standard method for fitting is the linear...
 01:05
Estimation of the Physical Quantities
 01:08
Fisher's Exact Test
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:19
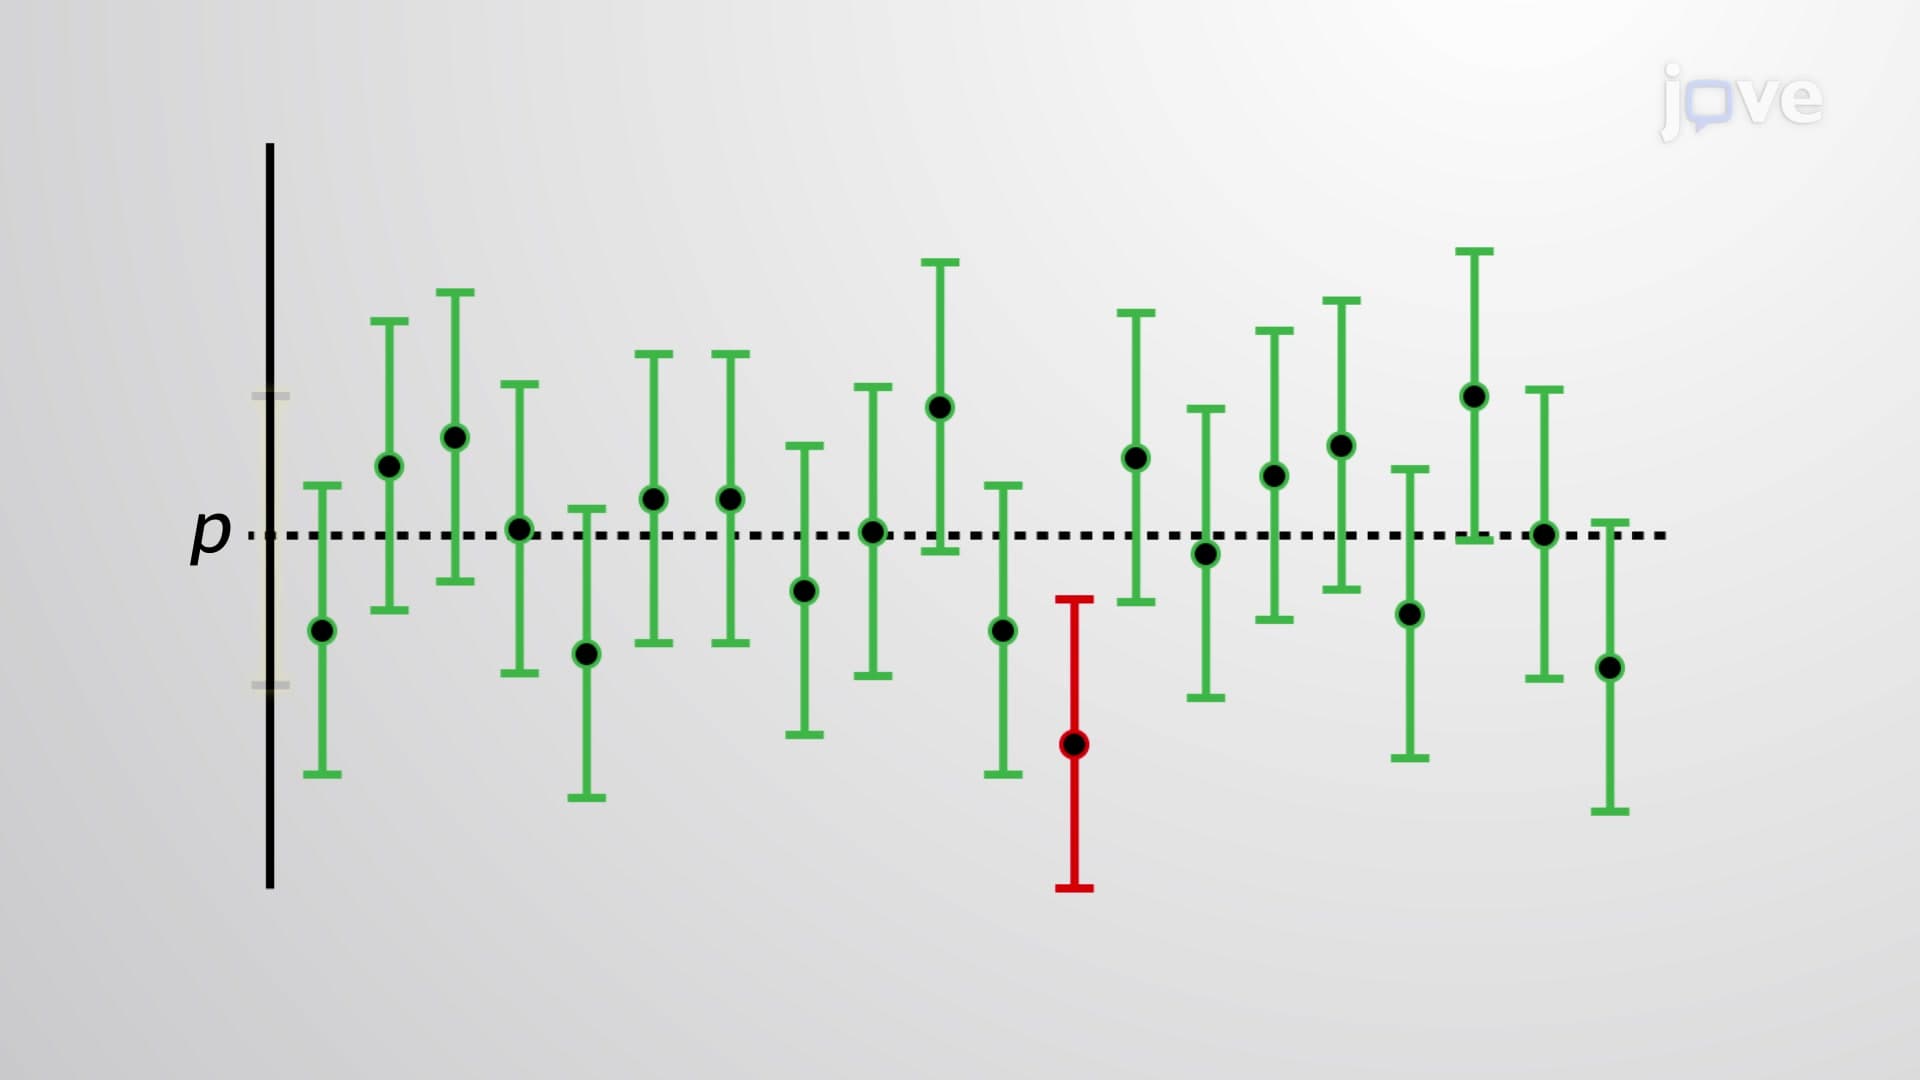
Interpretation of Confidence Intervals
Confidence intervals have confidence coefficients that are crucial for their interpretation. The most common confidence coefficients are 0.90, 0.95, and 0.99, which can be written as percentages–90%, 95%, and 99%, respectively.
Suppose a person calculates a confidence interval with a confidence coefficient of 0.95. In that case, they can...