Related Experiment Video
Updated: Aug 13, 2025
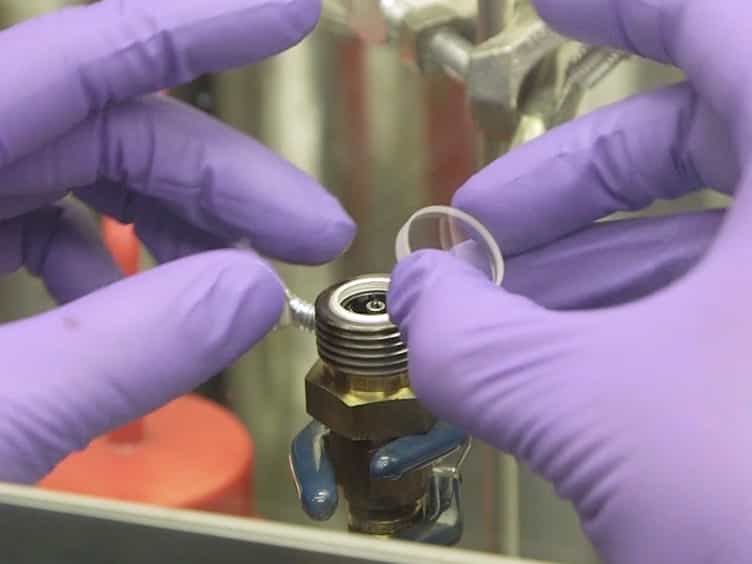

In Situ Visualization of the Phase Behavior of Oil Samples Under Refinery Process Conditions
Published on: February 21, 2017
Do U.S. economic conditions at the state level predict the realized volatility of oil-price returns? A quantile
Rangan Gupta1, Christian Pierdzioch2
1Department of Economics, University of Pretoria, Pretoria, 0002 South Africa.

Abstract:
Because the U.S. is a major player in the international oil market, it is interesting to study whether aggregate and state-level economic conditions can predict the subsequent realized volatility of oil price returns. To address this research question, we frame our analysis in terms of variants of the popular heterogeneous autoregressive realized volatility (HAR-RV) model. To estimate the models, we use quantile-regression and quantile machine learning (Lasso) estimators. Our estimation results highlights the differential effects of economic conditions on the quantiles of the conditional distribution of realized volatility. Using weekly data for the period April 1987 to December 2021, we document evidence of predictability at a biweekly and monthly horizon.
More Related Videos
Related Concept Videos
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:15
Expected Value
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:29
Econometric Views (EViews)
 00:56
Noncompartmental Analysis: Statistical Moment Theory
 01:12
Quantitative Analysis
In quantitative analysis, two key measurements are made: the sample quantity and a property proportional to the amount of the analyte (the substance being analyzed). This forms the basis of the...