Related Experiment Video
Updated: May 28, 2025

Author Spotlight: Advancing Alzheimer's Research – Exploring Early Detection and Multi-Omics Approaches
Published on: December 15, 2023
Autoencoders for Amortized Joint Maximum Likelihood Estimation of Confirmatory Item Factor Models
Dylan Molenaar1, Raoul P P P Grasman1, Mariana Cúri2
1University of Amsterdam, Amsterdam, The Netherlands.

Abstract:
Neural networks like variational autoencoders have been proposed as a statistical tool to fit item factor models to data. Advantages are that high dimensional models can be estimated more efficiently as compared to conventional approaches. In this study, we demonstrate advantages of a specific autoencoder as a tool for amortized joint maximum likelihood estimation of item factor models. Contrary to contemporary joint maximum likelihood estimation and marginal maximum likelihood estimation, no additional parameter constraints are necessary to ensure standard asymptotic theory to apply. In a simulation study, the performance of the autoencoder is compared to constrained joint maximum likelihood and various forms of marginal maximum likelihood under different distributions for the factor scores. Results show that the amortized joint maximum likelihood estimates of the factors scores are overall less biased as compared to the other approaches. We illustrate the use of the autoencoder in two real data examples.
More Related Videos
 06:48
Lexical Decision Task for Studying Written Word Recognition in Adults with and without Dementia or Mild Cognitive Impairment
Published on: June 25, 2019
 09:00
Author Spotlight: Validation of SICOLE-R for Assessing Cognitive and Reading Skills in Spanish-Speaking Children and Its Role in Personalized Education
Published on: August 16, 2024
Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:26
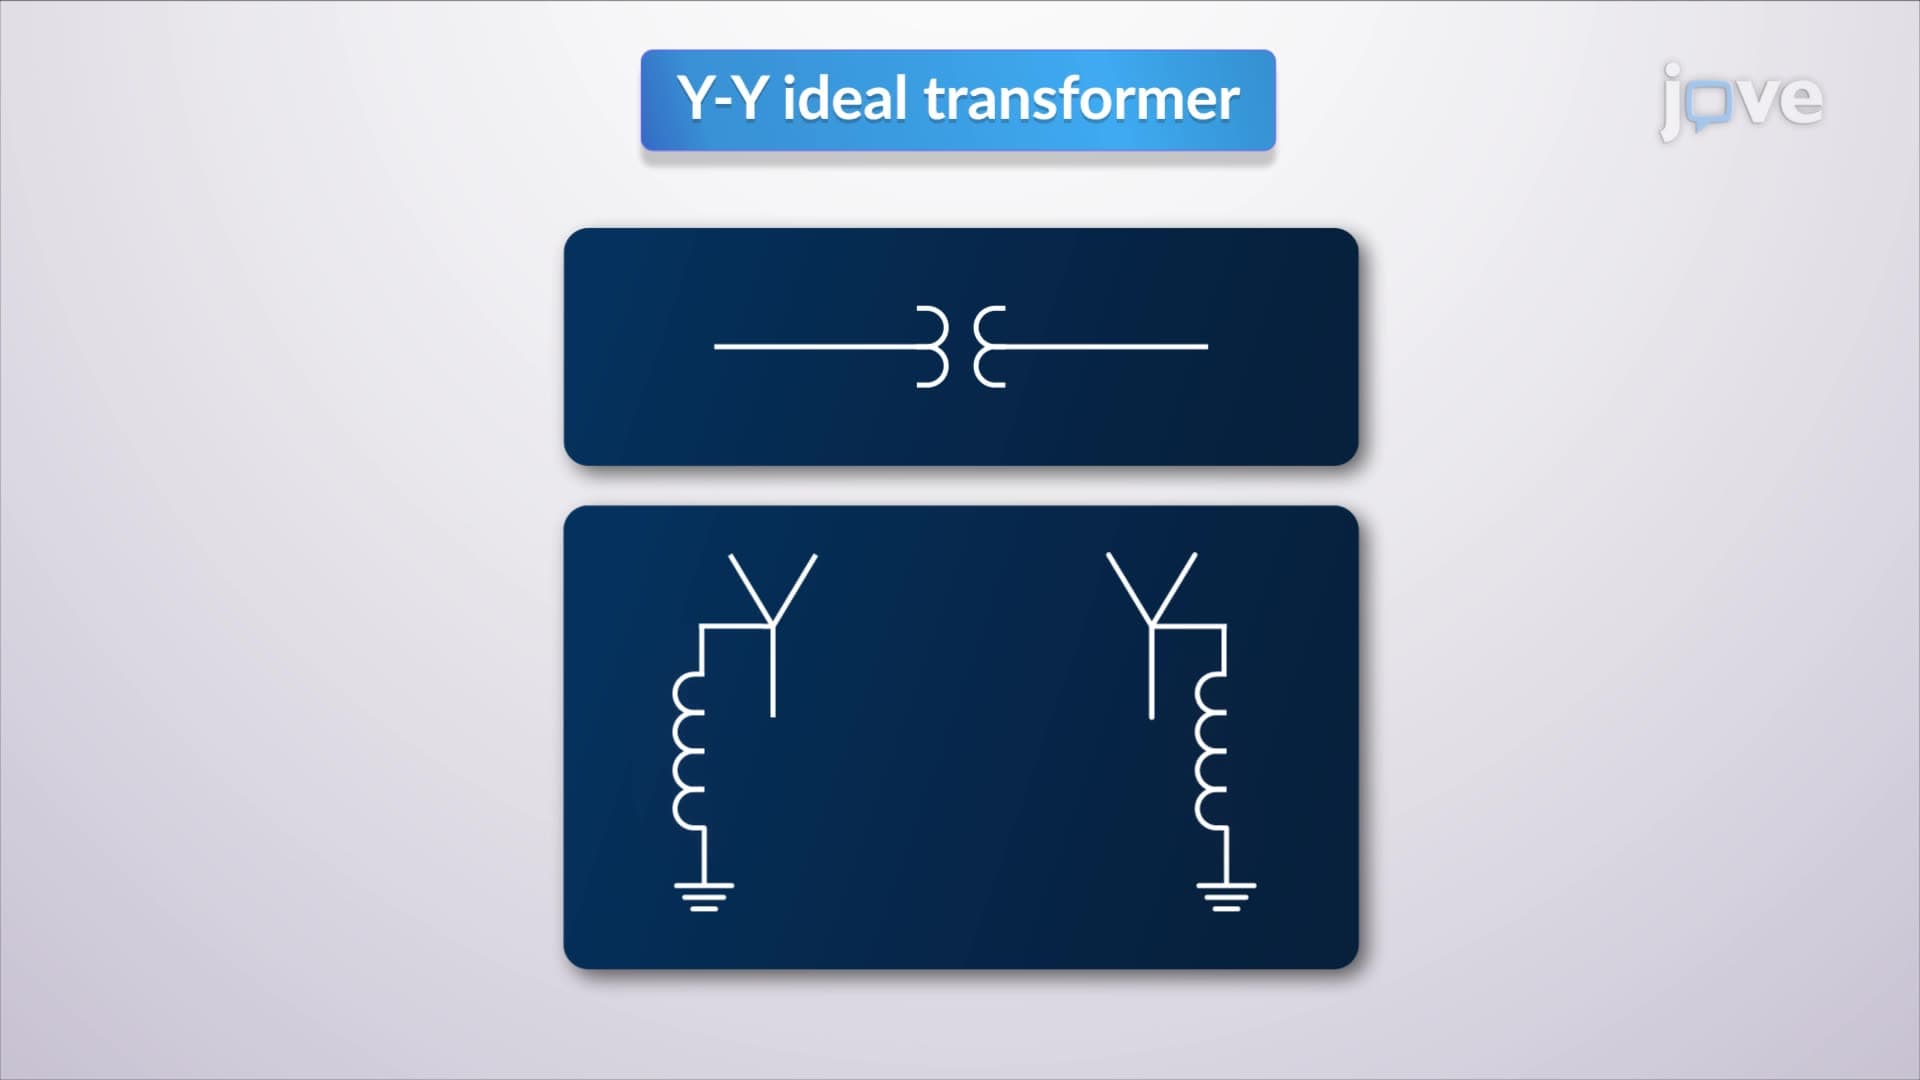
Per-Unit Sequence Models
Zero-sequence currents, which are identical in magnitude and phase, generate a neutral current, resulting in voltage drops across the neutral impedance and the low-voltage winding. If the...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:24
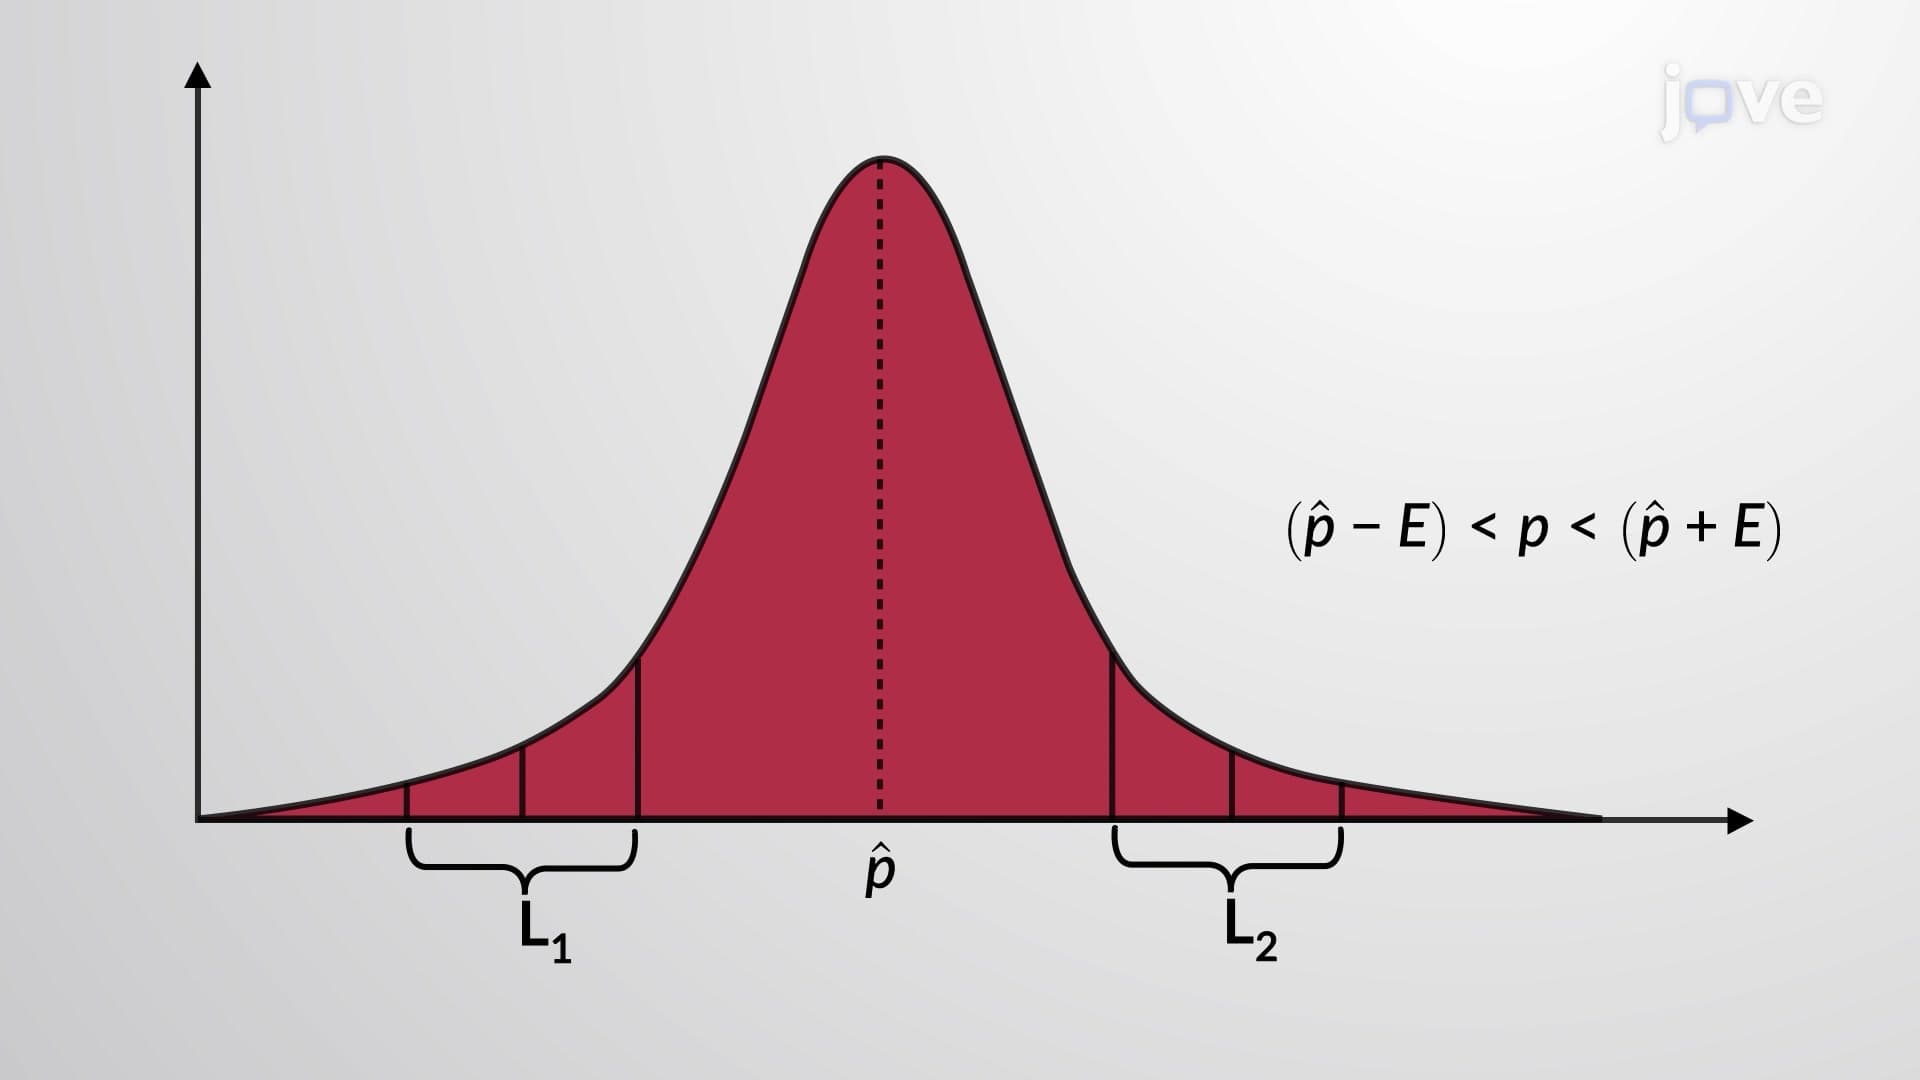
Confidence Coefficient
 01:19
Expected Frequencies in Goodness-of-Fit Tests
 01:21
Friedman Two-way Analysis of Variance by Ranks