Related Experiment Video
Updated: Sep 15, 2026

Diffusion Tensor Magnetic Resonance Imaging in the Analysis of Neurodegenerative Diseases
Published on: July 28, 2013
A divergence diagnostic for monitoring the composition of default in rating-migration matrices
1Sheffield University Management School, University of Sheffield, Conduit Road, Sheffield, S10 1FL, United Kingdom.

Abstract:
Reduced-form credit-portfolio models monitor risk through a single aggregate default rate, the exposure-weighted mean of origin-specific default rates across rating grades, sectors, or regions. That aggregate is only the level coordinate of the default-rate configuration: an origin-asymmetric shock that raises one origin's default rate and lowers another's by an offsetting amount leaves the aggregate unchanged while the composition of default reorganizes beneath it. This article describes a method to monitor that missing coordinate. From a decomposed migration matrix we form a normalized divergence statistic-a scalar for two origins and a vector for many-that is invariant to the common level and responds to composition rotations; we chart it with a scalar control limit and a Hotelling control chart on the general-K vector, bound the forecast bias a stale matrix imparts to probability of default, expected credit loss, and economic capital, and sign the rotation through a structural Merton model. We set out the two distinct central limit theorems the diagnostic rests on-one cross-sectional, governing the control limits, one temporal, governing the structural regime-and show that under a regime-switching Merton specification the reverse-hazard rate is an inverse Mills ratio, so that the direction of the rotation is itself regime-dependent. The method runs on the segment- or rating-decomposed default data institutions already report. •A normalized divergence statistic isolates the composition of default that the aggregate rate ignores. •Scalar and Hotelling control charts detect, time, and attribute origin-asymmetric default rotations. •A closed-form reverse-hazard rate signs the rotation and makes its direction regime-dependent.
Related Concept Videos
 01:19
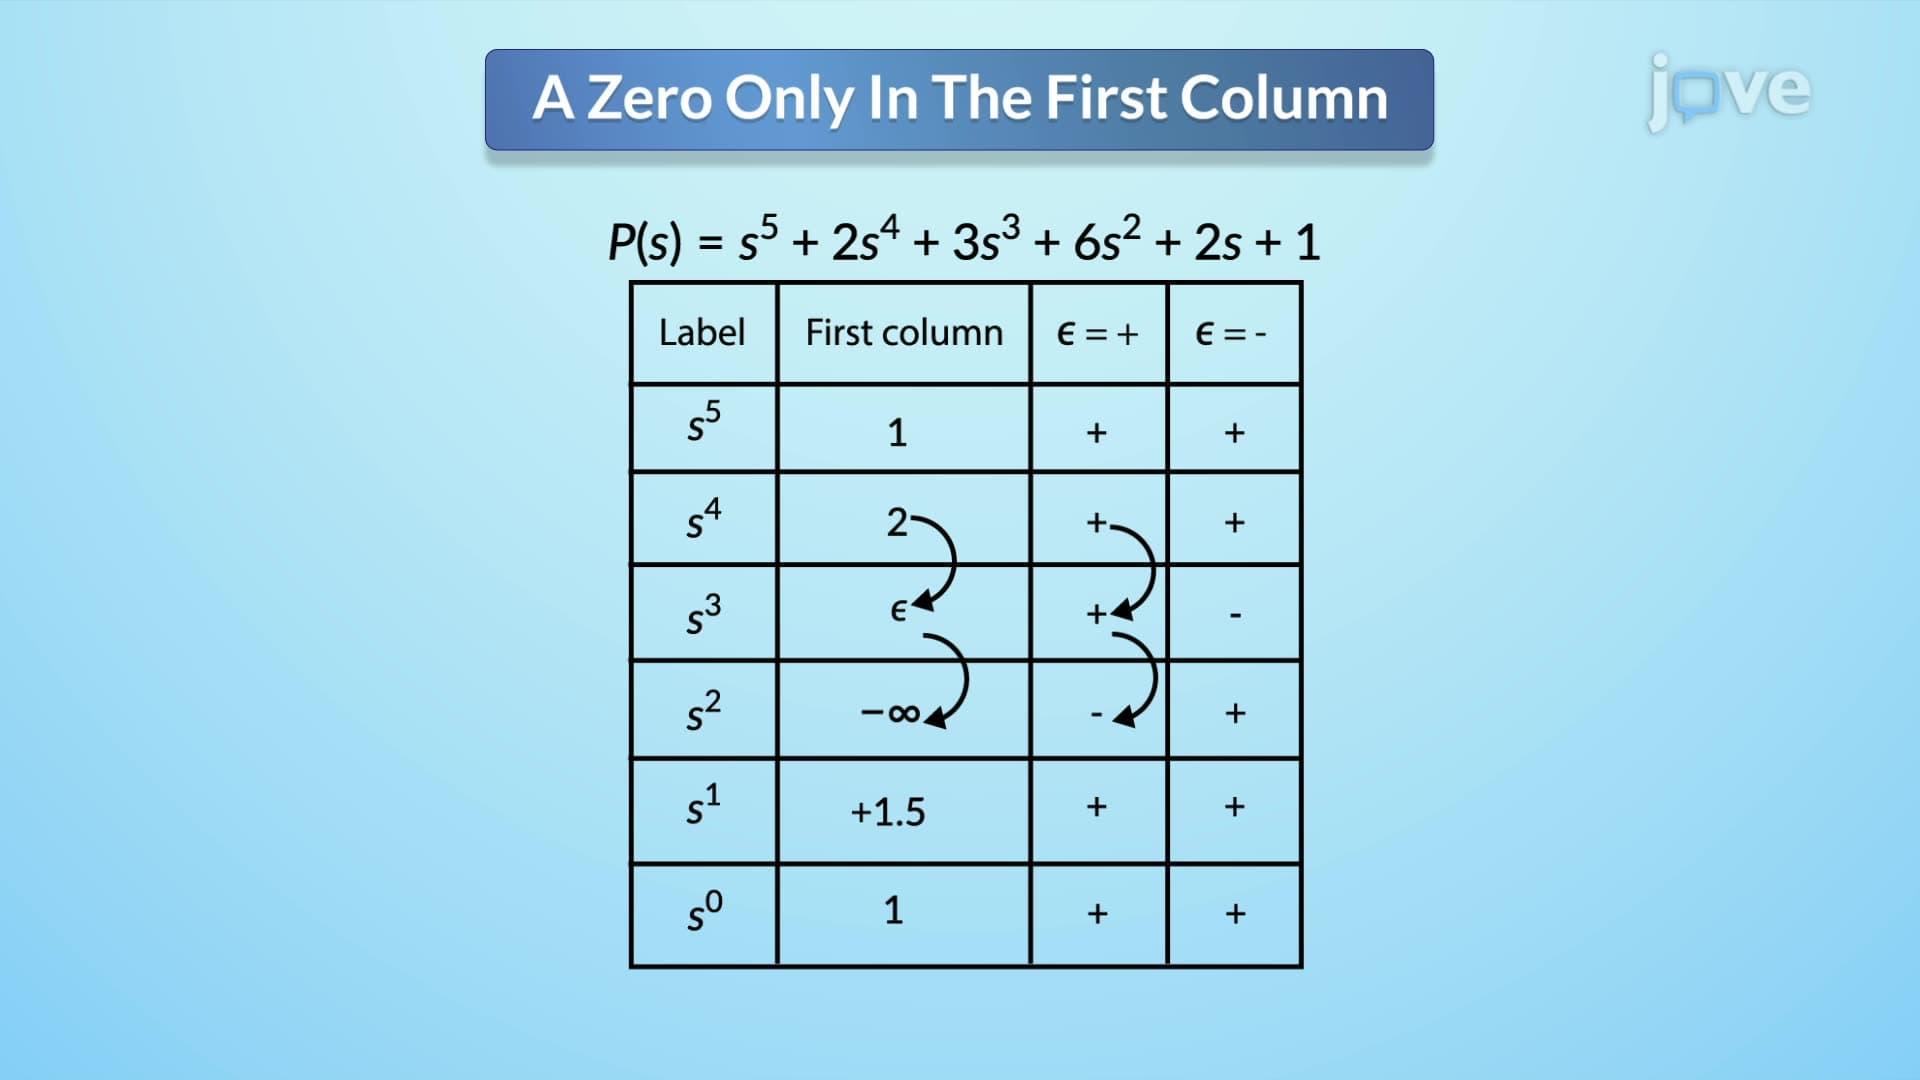
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first column of the Routh...
 01:15
Routh-Hurwitz Criterion I
To apply the Routh-Hurwitz criterion, a Routh table is constructed. The table's rows are labeled with powers of the complex frequency variable s, starting from the...
 01:22
Compacting Factor test
The procedure begins by placing concrete into the upper hopper without any compaction. Once filled, the bottom door of this hopper is opened,...
 01:14
Standard Deviation of Calculated Results
A broad Gaussian distribution curve has a wider standard deviation, representing a data set with...
 01:13
Mean Absolute Deviation
Let us consider a dataset containing the number of unsold cupcakes in five shops: 10, 15, 8, 7, and 10. Initially, calculate the sample mean. Then calculate the deviation, or the difference, between each data value and the mean. Next, the absolute values of these deviations are added and divided by the sample size to...
 01:15
Divergence and Curl